

|
시장보고서
상품코드
2114304
AIOps : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)AIOps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, AIOps 시장 규모는 2026년에 189억 5,000만 달러에 이르고, 2031년까지 377억 9,000만 달러에 이를 것으로 예측되며, CAGR은 14.8%를 나타낼 전망입니다.
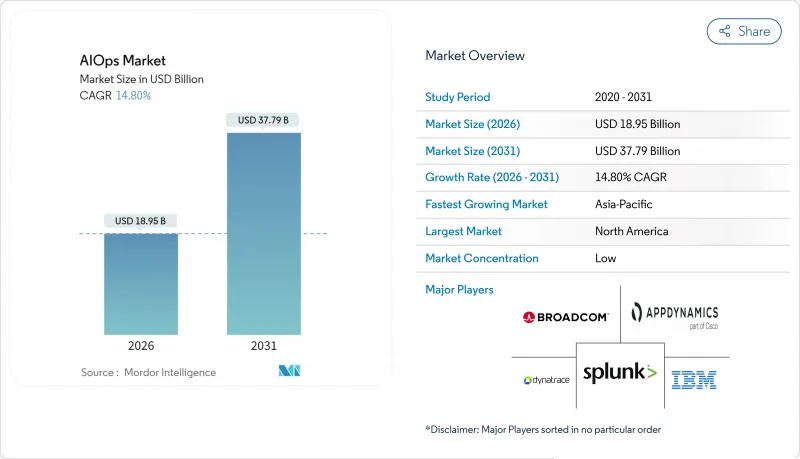
본 보고서는 구성 요소(플랫폼 및 서비스), 배포 방식(On-Premise 및 클라우드), 기업 규모(중소기업 및 대기업), 최종 사용자 산업(IT 및 통신, BFSI 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 AIOps 시장 동향 및 인사이트
AI를 활용한 가시성에 대한 수요 급증
마이크로서비스가 모놀리식 스택에 비해 10배나 많은 텔레메트리 데이터를 생성함에 따라, 2024년부터 2025년에 걸쳐 AI 기반 모니터링 도입률은 42%에서 54%로 상승했습니다. 기존의 규칙 기반 알림으로는 대응하기 어려웠기 때문에 알림 폭주가 발생했고, 당직 팀의 대응 속도가 둔화되었습니다. 현재는 머신러닝을 통한 기준선이 인프라의 노이즈를 필터링하고 사용자에게 영향을 미치는 인시던트를 식별함으로써 트리아지 대기 시간을 단축하고 있습니다. 2025년에 도입된 Datadog의 LLM 가시성 기능은 생성형 AI 워크로드의 토큰 소비량과 지연 시간을 추적합니다. 이는 고객용 용도에 대규모 언어 모델이 통합되면서 그동안 간과되기 쉬웠던 사각지대였습니다. 금융 업계의 리더는 1시간의 다운타임으로 200만 달러의 거래 손실과 규정 준수 벌금이 발생하기 때문에 모니터링 예산을 두 배로 늘리고 있습니다. 이러한 손실의 규모가 바로 AIOps 시장이 계속해서 가속화되고 있는 이유를 설명해 줍니다.
하이브리드 및 멀티클라우드 아키텍처로의 전환
기업들이 공급업체를 다각화하고 데이터 거주 요건을 준수함에 따라, 하이브리드 및 멀티클라우드 워크로드는 2023년 76%에서 2025년에는 87%로 증가했습니다. 각 하이퍼스케일러는 AWS CloudWatch, Azure Monitor, Google Cloud Operations 등 서로 다른 텔레메트리 모델을 채택하고 있기 때문에 팀은 상관 분석을 수행하기 전에 데이터를 정규화해야만 합니다. OpenTelemetry의 채택률은 클라우드 네이티브 프로젝트의 64%에 달했지만, 레거시 시스템에서는 여전히 syslog나 SNMP가 출력되고 있어 게이트웨이를 통한 변환이 필요합니다. 시스코가 AppDynamics와 Splunk를 인수한 후 통합함으로써, On-Premise와 클라우드를 모두 일원적으로 시각화하는 단일 관리 화면이 구현되었습니다. 유럽연합(EU) 및 인도의 주권 클라우드 규제에서는 리전 잠금(region-locked)된 AIOps 인스턴스가 요구되고 있으며, 이로 인해 모니터링 체제가 세분화되는 한편, 페더레이티드 애널리틱스에 대한 수요가 높아지고 있습니다.
도구의 난립과 ROI의 불확실성
많은 기업에서는 여전히 여러 모니터링 도구를 병행하여 사용하고 있으며, 이로 인해 텔레메트리 데이터가 파편화되고 라이선스 관련 비용이 증가하고 있습니다. 2025년에는 통합 움직임이 활발해졌지만, 통합의 복잡성으로 인해 투자 회수가 18개월 이상 지연될 가능성이 있습니다. 도입 첫해에 3자리 수의 투자 수익률을 달성한 조직은 극히 일부에 불과하며, 4분의 1에 해당하는 조직은 기능 활용 부족으로 인해 마이너스 수익률을 보고하고 있습니다. 용도, 로그, 네트워크 모니터링 기능의 중복으로 인해 중복된 경보가 발생하고, 운영 담당자는 수많은 경보에 파묻혀 있습니다. 중소기업은 많은 AIOps 플랫폼이 연중무휴 24시간 운영되는 사이트 신뢰성 팀을 전제로 하고 있는 반면, 이러한 팀을 구성하지 않고 있어 더 심각한 과제에 직면해 있습니다. 관리형 서비스 제공업체(MSP)가 이러한 격차를 메우는 데 도움을 줄 수 있지만, 대부분의 경우 마진이 가산되어 ROI가 희석되고 맙니다.
부문별 분석
2025년 지출 중 플랫폼 구독이 67.42%를 차지하여, 같은 해 AIOps 시장 점유율에서 가장 큰 비중을 차지했습니다. 그러나 서비스 부문은 조직이 이종 데이터의 연계, 기준선 조정 및 복구 자동화를 위해 외부 전문 지식에 의존하게 됨에 따라 2031년까지 연평균 성장률(CAGR) 16.04%를 나타낼 것으로 예측됩니다. 이러한 서비스로의 전환은 블랙박스형 알고리즘이 가치를 창출하기 전에 상황에 맞는 조정이 필요함을 여실히 보여줍니다.
전문 서비스 기업들은 도입을 가속화하기 위해 고객사 팀 내에 사이트 신뢰성 엔지니어를 배치하고 있는 반면, 관리형 서비스 제공업체들은 리테이너 계약에 기반한 ‘팔로우 더 선(Follow the Sun)’ 방식의 사고 대응 서비스를 제공합니다. 벤더의 인증 프로그램은 병행 수익원이 될 뿐만 아니라, 인재 풀을 확대하는 수단으로도 기능하고 있습니다. 플랫폼 개발은 생성형 AI 인터페이스와 엣지 추론으로 전환되고 있으며, DPU와 FPGA가 산업용 IoT 환경에서 1밀리초 미만의 이상 감지를 실현하고 있습니다. 또한 환경·사회·지배구조(ESG) 지표도 대시보드에 통합되어, 운영상의 우선순위와 지속가능성 우선순위가 나란히 표시되도록 되어 있습니다.
2025년에는 은행, 병원, 정부 기관이 기밀성이 높은 텔레메트리 데이터를 자사 데이터센터 내에서 보호함에 따라 On-Premise 도입이 도입된 환경의 56.66%를 차지했습니다. 각 하이퍼스케일러 기업이 네이티브 AIOps를 통합하고 데이터 상주법을 준수하는 소버린 리전을 제공하고 있기 때문에 클라우드 도입은 2031년까지 연평균 성장률(CAGR) 15.66%로 확대될 것으로 예측됩니다. 클라우드 구독은 자본 투자가 필요 없고, 워크로드 증가에 따라 탄력적으로 확장되어 비용과 사용량을 일치시킬 수 있다는 점에서 이러한 단계적 전환은 주목할 만합니다.
하이브리드 아키텍처는 기밀성이 높은 로그를 On-Premise에 보관하면서, 규제가 덜한 데이터는 클라우드 기반 분석으로 전송할 수 있게 해주는 현실적인 타협안으로 부상하고 있습니다. Datadog이나 New Relic과 같은 클라우드 네이티브 벤더들은 디지털 퍼스트 기업들 사이에서 압도적인 점유율을 차지하고 있으며, Datadog의 연간 영업 수익은 2025년에 20억 달러를 돌파했습니다. 유럽연합(EU)의 GDPR(EU 개인정보보호규정)에 따른 과징금과 새로운 소버린 클라우드의 등장은 규제 프레임워크가 도입 옵션에 직접적인 영향을 미칩니다는 것을 보여줍니다. 5년 단위로 볼 때, 패치 적용, 확장, 하드웨어 교체 주기 등의 이유로 인해 자체 호스팅 스택의 운영 비용은 구독형 서비스보다 상당히 높은 경우가 많습니다.
지역별 분석
북미는 성숙한 IT 운영 역량과 생성형 AI 코파일럿의 조기 도입에 힘입어 2025년 매출의 42.54%를 차지했습니다. 미국 금융 기관의 경우, 1시간당 서비스 중단으로 인한 비용의 중앙값이 200만 달러에 달하며, 이 수치는 투자의 시급성을 뒷받침합니다. 이 지역에서는 벤더 통합이 가장 두드러지며, 대기업들은 감사 및 내결함성 요건을 충족하기 위해 풀 스택 제품군의 표준화를 추진하고 있습니다.
아시아태평양은 공공 부문의 디지털화 프로그램과 데이터 현지화 법으로 인해 다국적 기업들이 지역 고유의 가시성 스택을 도입할 수밖에 없게 됨에 따라, 2031년까지 연평균 성장률(CAGR) 16.22%라는 가장 높은 성장률을 나타낼 것으로 예측됩니다. 인도의 ‘디지털 인디아(Digital India)’ 이니셔티브, 중국의 ‘제14차 5개년 계획’, 일본의 ‘사회 5.0’ 구상은 합쳐서 수십억 단위의 자금을 클라우드 인프라와 IoT에 투입하고 있으며, 자동화된 상관 분석이 필요한 새로운 텔레메트리 데이터를 생성하고 있습니다. 알리바바 클라우드와 텐센트 클라우드와 같은 지역 벤더들은 서유럽 소프트웨어에 대한 의존도를 낮추기 위해 자사 서비스에 AIOps를 통합하고 있습니다.
유럽은 여전히 중요한 기여자이지만, 엄격한 개인정보 보호 및 AI 거버넌스 체제로 인해 그 성장세는 완만해지고 있습니다. EU의 AI 법은 중요 인프라에 적용되는 AIOps를 ‘고위험’으로 분류하고, 투명성과 인간의 감독을 의무화하고 있습니다. 또한, GDPR(EU 개인정보보호규정) 시행에 따라 동의 없이 텔레메트리 데이터가 국경을 넘는 경우, 여전히 막대한 벌금이 부과되고 있습니다. 라틴아메리카, 중동 및 아프리카는 도입 초기 단계에 있지만, 정부의 현대화 및 통신망 확장 프로젝트를 통해 진전을 보이고 있으며, 이러한 움직임들이 향후 보급을 위한 토대를 마련하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the AIOps market size stands at USD 18.95 billion in 2026 and is projected to reach USD 37.79 billion by 2031, reflecting a 14.8% CAGR.
This report is Segmented by Component (Platform, and Services), Deployment Mode (On-Premises, and Cloud), Organization Size (Small and Medium Enterprises, and Large Enterprises), End-User Industry (IT and Telecom, BFSI, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global AIOps Market Trends and Insights
AI-Driven Observability Demand Surge
Enterprises moved from 42% to 54% adoption of AI-powered monitoring between 2024 and 2025 as microservices generated tenfold more telemetry than monolithic stacks. Traditional rule-based alerts could not cope, producing storms that desensitized on-call teams. Machine-learning baselines now filter infrastructure noise and surface user-impacting incidents, shrinking triage queues. Datadog's LLM Observability, introduced in 2025, tracks token consumption and latency in generative AI workloads, a blind spot as customer-facing applications embed large language models. Finance leaders have doubled monitoring budgets because a single hour of downtime costs USD 2 million in lost transactions and compliance penalties. The magnitude of these losses explains why the AIOps market continues to accelerate.
Shift to Hybrid and Multi-Cloud Architectures
Hybrid and multi-cloud workloads climbed to 87% in 2025, up from 76% in 2023, as firms diversify suppliers and comply with data-residency rules. Every hyperscaler exposes a different telemetry model - AWS CloudWatch, Azure Monitor and Google Cloud Operations - forcing teams to normalize data before correlation. OpenTelemetry adoption reached 64% of cloud-native projects, but legacy systems still emit syslog and SNMP, prompting gateway translation. Cisco's post-acquisition fusion of AppDynamics and Splunk created a single pane for on-premise and cloud visibility. Sovereign-cloud regulations in the European Union and India require region-locked AIOps instances, fragmenting oversight while driving demand for federated analytics.
Tool Sprawl and ROI Uncertainty
Most enterprises still juggle multiple monitoring tools, fragmenting telemetry and inflating licensing overhead. Consolidation efforts intensified in 2025, yet integration complexity can postpone payback beyond eighteen months. Only a small subset of organizations achieved triple-digit return on investment inside the first year, while a quarter reported negative returns due to underused features. Overlaps among application, log and network monitoring create redundant alerts that drown operators in noise. Small and medium enterprises face sharper friction because many AIOps platforms assume 24/7 site reliability teams that these firms do not staff. Managed service providers help close gaps but often add margin, diluting ROI.
Other drivers and restraints analyzed in the detailed report include:
- Need for Faster MTTR and SRE Adoption
- Gen-AI Copilots for Ops Automation
- Shortage of AIOps-Savvy Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Platform subscriptions captured 67.42% of 2025 spending, the largest slice of the AIOps market share for that year. The services segment, however, is projected to grow at a 16.04% CAGR to 2031 as organizations rely on external expertise to connect heterogeneous data feeds, tune baselines and automate remediation. This drift toward services underscores how black-box algorithms need context-specific calibration before they deliver value.
Professional services firms are embedding site reliability engineers inside client teams to accelerate adoption, while managed service providers offer follow-the-sun incident response priced on retainer. Vendor certification programs have become a parallel revenue stream and a way to expand the talent pool. Platform development is turning toward generative AI interfaces and edge inference, with DPUs and FPGAs driving sub-millisecond anomaly detection in industrial IoT environments. Environmental, social and governance metrics are also being woven into dashboards so that operational and sustainability priorities appear side by side.
On-premise implementations represented 56.66% of installed environments in 2025 as banks, hospitals and government agencies guarded sensitive telemetry within their own data centers. Cloud deployments are forecast to expand at a 15.66% CAGR through 2031 as hyperscalers embed native AIOps and offer sovereign regions that satisfy residency laws. The gradual shift is notable because cloud subscriptions eliminate capital outlays and scale elastically with workload growth, aligning cost with usage.
Hybrid architectures are emerging as a pragmatic compromise, retaining sensitive logs on-premise while allowing less-restricted data to flow into cloud-based analytics. Cloud-native vendors such as Datadog and New Relic enjoy outsized share among digital-first companies; Datadog's annual recurring revenue surpassed USD 2 billion in 2025. The European Union's GDPR fines and new sovereign clouds demonstrate how regulatory frameworks directly influence deployment choices. Over a five-year horizon, operating self-hosted stacks often costs considerably more than subscription services due to patching, scaling and hardware refresh cycles.
Complete Report Scope:
- By Component
- Platform
- Services
- By Deployment Mode
- On-Premise
- Cloud
- By Organization Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Industry
- IT and Telecom
- BFSI
- Healthcare
- Retail and E-Commerce
- Media and Entertainment
- Manufacturing
- Government and Public Sector
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America commanded 42.54% of 2025 revenue, driven by mature IT operations capabilities and early-stage adoption of generative AI copilots. Financial institutions in the United States experience median outage costs of USD 2 million per hour, a figure that reinforces investment urgency. Vendor consolidation is most visible here, where large enterprises are standardizing on full-stack suites to satisfy audit and resilience mandates.
Asia Pacific is forecast to register the fastest 16.22% CAGR to 2031 as public-sector digitization programs and data-localization laws compel multinational firms to deploy region-specific observability stacks. India's Digital India initiative, China's 14th Five-Year Plan and Japan's Society 5.0 blueprint collectively pour billions into cloud infrastructure and IoT, generating new telemetry that requires automated correlation. Regional vendors such as Alibaba Cloud and Tencent Cloud embed AIOps in their services to cut reliance on Western software.
Europe remains a significant contributor, though growth is moderated by stringent privacy and AI governance regimes. The EU AI Act classifies AIOps applied to critical infrastructure as high risk, obliging transparency and human oversight. GDPR enforcement continues to impose hefty penalties when telemetry traverses borders without consent. Latin America, the Middle East and Africa are earlier in their adoption curve but are progressing through government modernization and telecom expansion projects that plant seeds for future uptake.
- IBM Corporation
- Cisco Systems, Inc. (AppDynamics, LLC)
- Splunk LLC
- Dynatrace, Inc.
- Broadcom Inc. (including VMware, INC.: CA, Inc.)
- BMC Software, Inc.
- BigPanda, Inc.
- Moogsoft, Inc.
- Elastic N.V.
- New Relic, Inc.
- Datadog, Inc.
- PagerDuty, inc.
- ServiceNow, Inc. (Loom Systems, Inc.)
- ExtraHop Networks, Inc.
- StackState B.V.
- OpsRamp, Inc. (a Hewlett Packard Enterprise company)
- Juniper Networks, Inc. (Mist Systems, Inc.)
- Microsoft Azure Monitor (Microsoft Corporation)
- Amazon DevOps Guru (Amazon Web Services, Inc.)
- Google Cloud AIOps (Operations Suite, Google LLC)
- SolarWinds Worldwide, LLC
- ScienceLogic, Inc.
- LogicMonitor, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-Driven Observability Demand Surge
- 4.2.2 Shift to Hybrid and Multi-Cloud Architectures
- 4.2.3 Need for Faster MTTR and SRE Adoption
- 4.2.4 Gen-AI Copilots for Ops Automation
- 4.2.5 FPGA and DPU Acceleration at the Edge
- 4.2.6 Rise of ESG-Linked "Green Ops" Compliance
- 4.3 Market Restraints
- 4.3.1 Tool Sprawl and ROI Uncertainty
- 4.3.2 Shortage of AIOps-Savvy Talent
- 4.3.3 Data-Sovereignty and AI-Governance Hurdles
- 4.3.4 Vendor Black-Box Algorithms and Lock-In Risk
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Platform
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By Organization Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-User Industry
- 5.4.1 IT and Telecom
- 5.4.2 BFSI
- 5.4.3 Healthcare
- 5.4.4 Retail and E-Commerce
- 5.4.5 Media and Entertainment
- 5.4.6 Manufacturing
- 5.4.7 Government and Public Sector
- 5.4.8 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.4.1 IBM Corporation
- 6.4.2 Cisco Systems, Inc. (AppDynamics, LLC)
- 6.4.3 Splunk LLC
- 6.4.4 Dynatrace, Inc.
- 6.4.5 Broadcom Inc. (including VMware, INC.: CA, Inc.)
- 6.4.6 BMC Software, Inc.
- 6.4.7 BigPanda, Inc.
- 6.4.8 Moogsoft, Inc.
- 6.4.9 Elastic N.V.
- 6.4.10 New Relic, Inc.
- 6.4.11 Datadog, Inc.
- 6.4.12 PagerDuty, inc.
- 6.4.13 ServiceNow, Inc. (Loom Systems, Inc.)
- 6.4.14 ExtraHop Networks, Inc.
- 6.4.15 StackState B.V.
- 6.4.16 OpsRamp, Inc. (a Hewlett Packard Enterprise company)
- 6.4.17 Juniper Networks, Inc. (Mist Systems, Inc.)
- 6.4.18 Microsoft Azure Monitor (Microsoft Corporation)
- 6.4.19 Amazon DevOps Guru (Amazon Web Services, Inc.)
- 6.4.20 Google Cloud AIOps (Operations Suite, Google LLC)
- 6.4.21 SolarWinds Worldwide, LLC
- 6.4.22 ScienceLogic, Inc.
- 6.4.23 LogicMonitor, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


