

|
시장보고서
상품코드
2114323
자동차 통풍 시트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Ventilated Seats - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 자동차 통풍 시트 시장 규모는 2025년에 99억 2,000만 달러로 평가되었습니다. 2026년 105억 6,000만 달러에서 2031년까지 144억 1,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 6.41%를 나타낼 전망입니다.
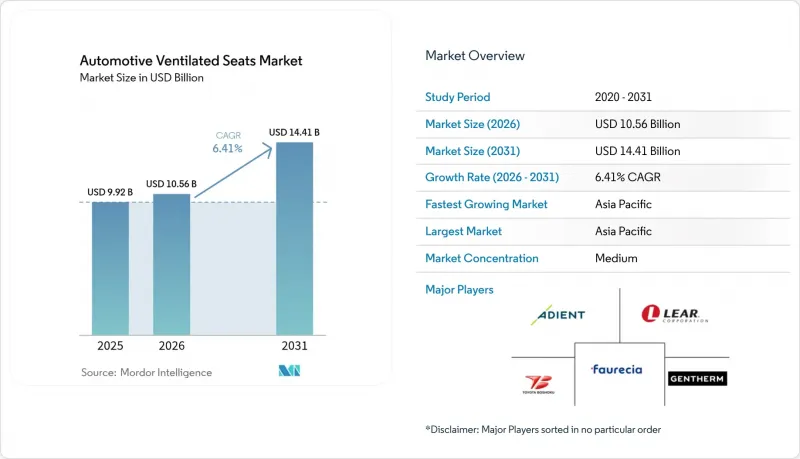
본 보고서는 차량 유형(승용차, 소형 상용차 등), 구동 방식(내연기관 등), 판매 채널(OEM 및 애프터마켓), 시트 트림 소재(천연 가죽 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 자동차 통풍 시트 시장 동향 및 인사이트
차내 쾌적성 향상에 대한 소비자 수요 증가
자동차가 이동식 생활 공간이 됨에 따라 차량 내부에 대한 기대도 변화하고 있습니다. 더운 기후 지역의 구매 의향 조사에서 통풍 시트는 현재 가장 많이 요청되는 편의 사양 상위 3위 안에 들었으며, 소유 기간이 10년을 넘는 경향도 업그레이드 수요를 뒷받침하고 있습니다. 고온 지역에서는 국소적인 시트 냉각이 기존 에어컨보다 더 신속하게 쾌적함을 제공하기 때문에 판매 쇼룸에서 중요한 차별화 요소가 되고 있습니다. 라이드셰어 이용자들도 가격대에 관계없이 프리미엄 사양이 당연시되면서 추가적인 압박을 가하고 있습니다. 이러한 요인들이 복합적으로 작용하여 쾌적성이 브랜드 충성도 전략의 핵심으로 자리 잡으면서, 통기식 시트의 대상 시장이 확대되고 있습니다.
중급 모델에서의 OEM 기능 차별화
2만 5,000-4만 달러 가격대의 자동차 제조업체들은 고급 브랜드 로고를 달지 않고도 판매 가격을 인상하기 위해 통기식 시트를 기본 사양으로 장착하고 있습니다. 2025년 양산 시작이 예정된 Lear사의 ‘ComfortMax’ 모듈은 열 반응 속도를 40% 향상시키는 동시에 시트 부품 수를 절반으로 줄여 조립의 복잡성을 경감시킵니다. 모듈식 키트를 통해 폭넓은 모델 라인업에 대응할 수 있게 되었으며, 가치를 중시하는 소비자가 구체적인 편의성에 대해 적정한 가격 프리미엄을 수용하는 아시아태평양에서 보급이 가속화되고 있습니다.
높은 시스템 비용과 복잡한 통합
공장에서의 초기 장착에는 전용으로 설계된 시트 프레임, 배선 및 소프트웨어 보정이 필요하기 때문에 신흥 시장용 모델의 경우 단위 비용이 높은 수준을 유지하고 있습니다. 사후 장착 키트의 경우, 통기 경로의 배선이나 컨트롤러의 CAN 버스 적응과 같은 과제가 추가됩니다. 연방 자동차 안전 기준(FMVSS) 207에 따른 안전 인증에서는 통풍 모듈을 탑재할 때마다 구조적 무결성을 확인해야 하므로, 이로 인해 검증 주기가 길어지고 통풍 시트 시장의 확대가 제약받고 있습니다.
부문별 분석
2025년에는 승용차가 시장 점유율의 대부분을 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.05%를 나타낼 전망 속에서 통기식 시트 시장 점유율의 64.80%를 차지했습니다. 스포츠 유틸리티 차량(SUV)은 인기 있는 트림 팩에 이 기능을 탑재함으로써 판매 대수를 견인하고 있습니다. 통근 시간의 길어짐과 운전 보조 패키지에 대한 관심 증가로 인해, 특히 여름 폭염이 장기화되는 지역에서 시트 단위의 공조 제어에 대한 수요가 높아지고 있습니다. 소형 상용 밴의 차량 운영 사업자들은 피로 완화 효과를 평가하기 시작했지만, 초기 비용 차이로 인해 대형 트럭이나 버스에서의 도입은 여전히 주춤하고 있습니다.
이 부문의 성장세는 중형 세단 및 소형 SUV에 프리미엄 부품을 재활용한 가성비 좋은 모듈이 도입됨에 따라, 통풍 시트 시장 전체의 규모를 확대할 것으로 전망됩니다. 전문 공급업체들은 대대적인 재설계가 필요 없이 여러 차체 스타일에 그대로 통합할 수 있는 확장 가능한 플랫폼을 제공함으로써 시장 출시까지의 시간을 단축하고 있습니다. 예측 기간 동안, 운전자의 건강 증진을 목적으로 한 지역별 규제로 인해 상용 승객 셔틀 및 라이드셰어 차량의 도입률이 상승하여 승용차 부문의 주도적 지위가 더욱 공고해질 가능성이 있습니다.
2025년 시점에서는 내연기관 플랫폼이 여전히 78.60%를 차지하며 주도적인 위치를 유지했지만, 배터리 전기자동차(BEV)는 2031년까지 연평균 성장률(CAGR) 12.10%라는 급격한 성장 궤도에 올라 있습니다. BEV의 성장을 뒷받침하는 요인은 공조(HVAC)로 인한 주행 거리 감소를 완화해야 할 필요성이며, 이에 따라 시트 환기 및 배터리 열 관리 전략의 통합이 진행되고 있습니다. Yanfeng사의 ‘Smart Cabin Seats’는 개별적인 미기후를 조성하여, 주 HVAC가 작동하기 전에 차량 내부의 열 축적을 줄여줍니다. 이는 BEV의 패키징 유연성이 통풍식 시트 설계에 어떻게 기여하고 있는지를 보여주는 좋은 예입니다. 하이브리드차 및 플러그인 하이브리드차 모델은 과도기적인 역할을 수행하며, 각 OEM 업체에게 순수 전기차의 제약 없이 첨단 쾌적성 알고리즘을 시험할 수 있는 기회를 제공합니다.
BEV의 급속한 성장에 따라, 전동 구동계와 관련된 통기성 시트 시장 규모는 전체 시장을 능가하는 속도로 확대될 전망입니다. 송풍기의 소형화를 실현하고, 난방, 냉방, 햅틱 피드백을 하나의 모듈에 통합할 수 있는 공급업체는 전기차의 엄격한 패키징 요구 사항 속에서 우위를 점할 수 있습니다. 에너지 효율이 높은 HVAC를 장려하는 규제 인센티브로 인해, 개발 예산은 BEV에 더욱 최적화된 시트 시스템으로 집중될 것입니다.
지역별 분석
아시아태평양은 2025년 통풍 시트 시장의 45.00%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.45%로 성장하고 있습니다. 중국이 이 지역 수요를 주도하고 있습니다. 중국에서는 이미 전기차가 신차 판매의 45%를 차지하고 있으며, QIANZE와 같은 현지 공급업체들이 매월 1,000세트의 통풍 시트를 공급함으로써 각 OEM 업체의 비용 절감에 기여하고 있습니다. 일본 및 한국의 기업들은 기술적 깊이를 더하고 있습니다. 예를 들어, 현대트랜시스는 통기성을 높이는 VOC(휘발성 유기 화합물) 저감 패드에 대해 국가 인증을 획득했습니다. 고온 다습한 동남아시아의 기후는 소비자들에게 더욱 큰 매력을 주고 있으며, 에너지 절약 부품에 대한 정부의 보조금도 통기성 시트의 보급을 뒷받침하고 있습니다.
북미에서는 승용차 시장이 성숙기에 접어들어, 편의 사양이 하위 부문으로 확산됨에 따라 꾸준한 교체 수요가 발생하고 있습니다. 차량 소유 기간이 장기화됨에 따라 사후 장착 시장도 활성화되고 있습니다. 또한, 제너럴 모터스와 리아 코퍼레이션의 공동 프로그램을 통해 모듈식 ‘ComfortMax’ 유닛이 대량 생산되는 주요 차종에 채택되고 있습니다. 상용차 플릿 부문에서는 향후 도입될 피로 관리 지침 준수를 목적으로 통기성 운전석 도입을 검토하고 있어, 새로운 판매 기회가 창출되고 있습니다.
유럽에서는 프리미엄 통합 기능과 수명 주기 배출량에 초점이 맞추어져 있습니다. FORVIA사의 트럭용 시트 솔루션은 CO2 배출량을 40% 감축하여, 이 지역의 지속가능성 노력의 진화를 상징하고 있습니다. 재활용 가능성에 대한 법적 규제의 압박으로 인해, 사용 후 폐기물을 원료로 한 폼 및 커버 소재의 채택이 진행되고 있으며, 유럽의 각 OEM 업체들은 시트 부품의 순환형 조달 분야에서 최전선에 서 있습니다.
라틴아메리카, 중동 및 아프리카의 신흥 시장에서는 잠재적 수요가 나타나고 있으나, 가격에 대한 민감성과 서비스 네트워크 부족으로 인해 시장 침투가 지연되고 있습니다. 예측 기간 후반에는 현지 조립 파트너십을 통해 이러한 장벽이 완화될 것으로 전망됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, the automotive ventilated seats market size was valued at USD 9.92 billion in 2025 and estimated to grow from USD 10.56 billion in 2026 to reach USD 14.41 billion by 2031, at a CAGR of 6.41% during the forecast period (2026-2031).
This report is Segmented by Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Propulsion (Internal Combustion Engine and More), Sales Channel (OEM and Aftermarket), Seat Trim Material (Genuine Leather and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Ventilated Seats Market Trends and Insights
Rising Consumer Demand for Enhanced Cabin Comfort
Cabin expectations have shifted as cars become mobile living spaces. Ventilated seats now rank among the three most requested comfort features in hot-climate purchase surveys, and ownership cycles extending beyond a decade reinforce demand for upgrades. In high-temperature regions, localized seat cooling delivers faster relief than conventional air-conditioning, making it a critical differentiator in retail showrooms. Ride-sharing passengers add further pressure by normalizing premium amenities across price segments. Collectively, these factors place comfort at the center of brand-loyalty strategies and extend the addressable ventilated seats market.
OEM Feature-Differentiation in Mid-Range Models
Automakers in the USD 25,000-40,000 bracket are bundling ventilated seats to raise transaction prices without a luxury-brand badge. Lear's ComfortMax modules, reaching production in 2025, deliver 40% quicker thermal response while cutting seat part count by half, lowering assembly complexity. Modular kits allow wider model-mix coverage, accelerating penetration in Asia-Pacific, where value-conscious buyers accept moderate price premiums for tangible comfort.
High System Cost and Complex Integration
Factory installations require tailored seat frames, wiring, and software calibration, keeping unit costs elevated for emerging-market models. Retrofit packages add hurdles such as air-path routing and controller CAN bus adaptation. Safety certification under Federal Motor Vehicle Safety Standard 207 mandates structural integrity checks whenever ventilation modules are inserted, prolonging validation cycles and constraining the ventilated seats market's reach.
Other drivers and restraints analyzed in the detailed report include:
- Surge in EV Sales Enabling Seat-Level HVAC
- Cost Decline in Micro-Blower and Perforated-Foam Technologies
- Reliability and Maintenance Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger cars generated the majority share in 2025, capturing 64.80% of the ventilated seats market share amid an 8.05% CAGR outlook through 2031. Sport Utility Vehicle drive volume by bundling the feature in popular trim packs. Extended commute times and growing interest in driver-assistance packages amplify demand for seat-level climate control, especially where summer heatwaves lengthen. Fleet operators of light commercial vans are beginning to evaluate reduced fatigue benefits, yet upfront price gaps continue restraining adoption in heavy trucks and buses.
The segment's momentum is set to expand the overall ventilated seats market size as mid-range sedans and compact Sport Utility Vehicles introduce value-grade modules that reuse premium components. Specialist suppliers are offering scalable platforms that drop into multiple body styles without major redesign, accelerating time to market. Over the forecast period, regional mandates targeting driver wellness could lift penetration in commercial passenger shuttles and ride-hailing fleets, reinforcing the passenger-car segment's leadership.
Internal-combustion platforms still dominate at 78.60% in 2025, yet battery electric vehicles are on a steeper trajectory with a 12.10% CAGR to 2031. The BEV tacker is propelled by the need to mitigate HVAC-induced range loss, prompting integration of seat ventilation with battery-thermal strategies. Yanfeng's Smart Cabin Seats create individual micro-climates to cut cabin heat-soak before the main HVAC starts, exemplifying how BEV packaging flexibility benefits ventilated seat design. Hybrid and plug-in hybrid models play a transitional role, offering OEMs a testbed for advanced comfort algorithms without full EV constraints.
Rapid BEV growth means the ventilated seats market size linked to electric drivetrains is set to outpace the overall market. Suppliers that can miniaturize blowers and unify heating, cooling, and haptic feedback into one module stand to gain from tight EV packaging envelopes. Regulatory incentives that reward energy-efficient HVAC will further tilt development budgets toward BEV-optimized seating systems.
Complete Report Scope:
- By Vehicle Type
- Passenger Cars
- Hatchback
- Sedan
- Sport Utility Vehicle
- Multi-Purpose Vehicle
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Buses and Coaches
- Passenger Cars
- By Propulsion Type
- Internal Combustion Engine (ICE)
- Hybrid & Plug-in Hybrid
- Battery Electric Vehicle (BEV)
- By Sales Channel
- OEM
- Aftermarket
- By Seat-Trim Material
- Genuine Leather
- Synthetic Leather (PU, PVC)
- Fabric
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 45.00% of the ventilated seats market in 2025 and is expanding at an 8.45% CAGR through 2031. China anchors regional demand: electric vehicles already comprise 45% of its new-car sales, and localized suppliers such as QIANZE deliver 1,000 ventilated seat sets each month, helping OEMs contain costs. Japanese and South-Korean firms add technology depth; Hyundai Transys, for example, earned national certification for VOC-reduced padding that enhances airflow. Hot and humid Southeast-Asian climates further boost user appeal, while government subsidies on energy-efficient components align with ventilated seat adoption.
North America's mature passenger-car parc fosters steady replacement demand as comfort features migrate down-segment. Extended vehicle ownership cycles encourage retrofit activity, and collaborative programs between General Motors and Lear Corporation bring modular ComfortMax units to high-volume nameplates. Commercial fleets are evaluating ventilated driver seats to comply with forthcoming fatigue-management guidelines, creating new volume opportunities.
Europe focuses on premium integration and life-cycle emissions. FORVIA's truck seat solution trimming CO2 impact by 40% is emblematic of regional sustainability evolution. Legislative pressure on recyclability drives adoption of foam and cover stocks derived from post-consumer waste, positioning European OEMs at the forefront of circular seat component sourcing.
Emerging markets across Latin America, the Middle East, and Africa show latent demand, but price sensitivity and service-network gaps slow penetration; localized assembly partnerships are expected to ease these hurdles by the late forecast years.
- Faurecia SE
- Adient PLC
- Lear Corporation
- Toyota Boshoku Corporation
- TS Tech Co. Ltd.
- Hyundai Transys
- Magna International Inc.
- Continental AG
- Gentherm Inc.
- Brose Fahrzeugteile
- Denso Corporation
- NHK Spring Co.
- Tachi-S Co.
- Yanfeng Automotive Interiors
- Hanon Systems
- Marelli Corporation
- ebm-papst Group
- Grammer AG
- Johnson Electric Holdings
- Proseat GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Consumer Demand For Enhanced Cabin Comfort
- 4.2.2 OEM Feature-Differentiation in Mid-Range Models
- 4.2.3 Surge In EV Sales Enabling Seat-Level HVAC
- 4.2.4 Cost Decline in Micro-Blower and Perforated-Foam Technologies
- 4.2.5 Fatigue Health Regulations
- 4.2.6 Premium Shared-Mobility Fleet Upgrades
- 4.3 Market Restraints
- 4.3.1 High System Cost and Complex Integration
- 4.3.2 Reliability and Maintenance Concerns
- 4.3.3 EV Range Anxiety Over HVAC Energy Draw
- 4.3.4 Cabin Acoustic Targets Limiting Fan Noise Levels
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Cars
- 5.1.1.1 Hatchback
- 5.1.1.2 Sedan
- 5.1.1.3 Sport Utility Vehicle
- 5.1.1.4 Multi-Purpose Vehicle
- 5.1.2 Light Commercial Vehicles
- 5.1.3 Medium and Heavy Commercial Vehicles
- 5.1.4 Buses and Coaches
- 5.1.1 Passenger Cars
- 5.2 By Propulsion Type
- 5.2.1 Internal Combustion Engine (ICE)
- 5.2.2 Hybrid & Plug-in Hybrid
- 5.2.3 Battery Electric Vehicle (BEV)
- 5.3 By Sales Channel
- 5.3.1 OEM
- 5.3.2 Aftermarket
- 5.4 By Seat-Trim Material
- 5.4.1 Genuine Leather
- 5.4.2 Synthetic Leather (PU, PVC)
- 5.4.3 Fabric
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Faurecia SE
- 6.4.2 Adient PLC
- 6.4.3 Lear Corporation
- 6.4.4 Toyota Boshoku Corporation
- 6.4.5 TS Tech Co. Ltd.
- 6.4.6 Hyundai Transys
- 6.4.7 Magna International Inc.
- 6.4.8 Continental AG
- 6.4.9 Gentherm Inc.
- 6.4.10 Brose Fahrzeugteile
- 6.4.11 Denso Corporation
- 6.4.12 NHK Spring Co.
- 6.4.13 Tachi-S Co.
- 6.4.14 Yanfeng Automotive Interiors
- 6.4.15 Hanon Systems
- 6.4.16 Marelli Corporation
- 6.4.17 ebm-papst Group
- 6.4.18 Grammer AG
- 6.4.19 Johnson Electric Holdings
- 6.4.20 Proseat GmbH


