

|
시장보고서
상품코드
2114653
고유량 비강 캐뉼라 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)High-flow Nasal Cannula - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
고유량 비강 캐뉼라 시장 규모는 2025년에 80억 7,000만 달러, 2026년 89억 1,000만 달러에서 2031년까지 146억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 10.45%를 기록할 전망입니다.
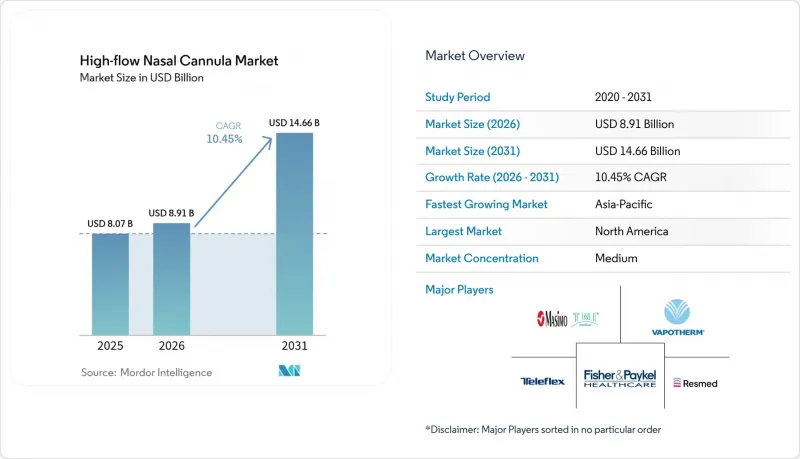
본 보고서는 구성 부품(공기·산소 혼합기, 능동형 가습기, 단일 가열 튜브 등), 최종 사용자(병원·중환자실 등), 용도(급성 호흡 부전 등), 환자 연령대(신생아·소아, 성인 등) 및 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 고유량 비강 캐뉼라 시장 동향 및 인사이트
전 세계 급성 및 만성 호흡기 질환 유병률 증가
2024년에는 2억 명이 발병하고 320만 명이 사망한 만성폐쇄성폐질환(COPD)의 부담으로 인해, 임상의들은 기존의 산소 투여법을 뛰어넘는 치료법의 도입을 요구받고 있습니다. 전 세계 천식 환자 수는 3억 5,000만 명을 넘어섰으며, 한편 북반구의 감시 결과에서는 계절성 인플루엔자가 여전히 가장 많이 검출되는 병원체로 나타났습니다. 이러한 역학적 압박으로 인해 재입원율을 낮추고 건강 관련 삶의 질(QOL) 점수를 향상시키는 고유량 요법에 대한 수요가 높아지고 있으며, 고유량 비강 캐뉼라 시장은 현대 호흡기 치료의 필수적인 축으로서의 위상을 확립하고 있습니다.
가온 가습 및 통합형 유량 모니터링 분야의 기술적 진보
주요 기기를 비교한 벤치 테스트에서 AIRVO 2, bellavista 1000 및 HUMID-BH는 37°C에서 공칭 이슬점에 가까운 값을 실현하여 점막 보호와 분비물 제거를 촉진하는 것으로 나타났습니다. 전산유체역학(CFD) 모델링을 통해, 최적화된 캐뉼라 형상이 비인두 내에서 거의 100%의 상대 습도를 유지하고 기도 폐쇄를 억제한다는 것이 확인되었습니다. 이러한 혁신을 통해 유량과 FiO2의 실시간 조정이 가능해져, 치료 범위가 중환자실(ICU)의 범위를 넘어 확대됨과 동시에 고유량 비강 캐뉼라 시장에서 각 제품의 차별화가 이루어지고 있습니다.
기존 산소 공급 방식에 비해 높은 초기 투자 및 운영 비용
HFNC 시스템의 초기 투자 비용은 표준 산소 공급의 3-5배에 달할 수 있으며, 일회용 회로로 인해 지속적인 비용이 발생합니다. 소아 기관지염에 대한 비용 대비 효과 분석에서 CPAP 비용은 1만 7,574달러인 반면, HFNC는 2만 9,421달러였으나, QALY(질 조정 생존 연수)는 약간 더 높았습니다. 예산 제약이나 불안정한 전력 공급 등 인프라 측면의 과제로 인해 개발도상국에서의 보급이 지연되고 있으며, 이는 고유량 비강 캐뉼라 시장의 성장세를 저해하고 있습니다.
부문 분석
액티브 가습기는 점막을 보호하는 체온과 동등한 습도로 가스를 공급하는 중요한 역할을 수행하고 있어, 2025년에는 부품 매출의 33.82%를 차지했습니다. 차세대 기종에는 알고리즘에 기반한 이슬점 제어 기능이 탑재됨에 따라, 액티브 가습기 고유량 비강 캐뉼라 시장 규모는 2031년까지 연평균 성장률(CAGR) 9.03%로 꾸준히 확대될 전망입니다. 이어, 전자 차트 연동에 대응한 정밀한 FiO2 조절에 대한 수요에 힘입어 공기·산소 혼합 장치가 성장하고 있습니다. 비강 캐뉼라 부품은 욕창을 완화하고 소아용 크기에 대응하는 설계 개선을 반영하여 연평균 성장률(CAGR) 13.33%로 이 부문을 견인할 전망입니다. 제조업체들은 이러한 부품을 독자적인 생태계에 통합하는 경향이 강해지고 있으며, 이는 고유량 비강 캐뉼라 시장에서 고객 충성도를 높이고 있습니다.
설계 개선은 가스 분배를 더욱 원활하게 하고 계면 전단을 감소시킨다는 것이 입증된 전산유체역학(CFD) 연구 결과를 기반으로 합니다. 단일 가열 튜브는 경보나 치료 중단을 유발할 수 있는 결로를 최소화하기 때문에 보급이 확대되고 있습니다. 가습기, 블렌더, 회로, 캐뉼라를 단일 브랜드 아래 통합하는 제품 전략은 주요 공급업체들이 고유량 비강 캐뉼라 시장에서 가격 책정과 이익률을 유지하는 데 도움이 되고 있습니다.
2025년에는 HFNC가 비강 캐뉼라에서 인공호흡기로의 단계적 전환 알고리즘에서 표준이 됨에 따라, 병원 및 중환자실(ICU)이 전 세계 매출의 47.30%를 차지했습니다. 1만 230명의 환자를 대상으로 한 메타분석에서는 기존 산소 요법에 비해 이후 침습적 인공호흡으로 전환될 위험이 0.85인 것으로 확인되어, 병원에서 수요가 더욱 증가하고 있습니다. 장기 요양 시설에서는 고령 입소자의 만성 저산소혈증을 관리하기 위해 HFNC를 도입하고 있으며, 이동식 트롤리 탑재형 장치가 이를 지원하는 데 일조하고 있습니다.
재택 간호 분야는 COPD로 인한 재입원 감소에 대한 증거와 원격 호흡 관리 대시보드의 발전에 힘입어, 최종 사용자별로는 가장 높은 연평균 성장률(CAGR) 12.57%로 확대될 것으로 예측됩니다. 가정용 고유량 비강 캐뉼라 시장 규모는 2025년 11억 달러에서 2031년까지 22억 3,000만 달러로 확대될 것으로 예측됩니다. 소아에 대한 후향적 데이터에 따르면, 상기도 폐쇄나 CO2 제거를 이유로 HFNC를 사용하여 퇴원한 소아의 합병증 발생률은 낮은 것으로 밝혀졌습니다. 원격 모니터링 비용을 보상하는 새로운 지불자 모델이 도입을 더욱 촉진하여, 고유량 비강 캐뉼라 시장의 수익원 다각화로 이어지고 있습니다.
지역별 분석
북미는 선진적인 보험 환급 제도와 미국 내 2,500만 건의 천식 진단 사례에 힘입어 2025년에 매출 점유율 37.45%로 1위를 차지했습니다. 기관지염 치료 지원의 성공으로 2013년부터 2022년까지 소아용 고유량 비강 캐뉼라(HFNC) 사용이 4.8배 증가했으며, 고유량 요법은 중환자실(ICU)에서 일반 병동으로 전환되었습니다. 이 지역의 재택 간호용 고유량 비강 캐뉼라 시장 규모는 보험사들의 원격 호흡 관리 번들 도입이 확대됨에 따라 2031년까지 15억 8,000만 달러를 넘어설 것으로 전망됩니다.
아시아태평양은 호흡기 질환 유병률 상승, 인프라 투자, 그리고 세계 공급업체들의 현지화 추진에 힘입어 연평균 성장률(CAGR) 10.86%라는 가장 높은 성장률을 보일 것으로 전망됩니다. WHO의 2024년판 개요서에서는 자원이 부족한 병원의 신생아 병동을 대상으로 한 ‘PremieBreathe’와 같은 저비용 솔루션이 소개되었습니다. 중국과 인도에서 비침습적 인공호흡기에 대한 보조금 지급을 포함하는 정부 프로그램은 2차 의료시설에서의 보급을 더욱 촉진할 것으로 예측됩니다.
유럽에서는 확고한 임상시험을 통해 치료 효과가 입증된 서유럽 의료 시스템에서 HFNC 도입이 지속적으로 진행되고 있습니다. 동유럽에서는 호흡 치료의 현대화를 위한 EU의 자금 지원에 힘입어 도입이 확대되고 있습니다. 중동 및 아프리카 및 남미는 아직 발전 단계에 있지만, 미래 성장 잠재력이 높다고 할 수 있습니다. 대상에 맞춘 의료 종사자 교육 프로그램과 불안정한 전력 공급에 적합한 모듈식 HFNC 시스템을 통해, 예측 기간 동안 고유량 비강 캐뉼라 시장이 가속화될 것으로 전망됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.26According to Mordor Intelligence, the high-flow nasal cannula market size was valued at USD 8.07 billion in 2025 and estimated to grow from USD 8.91 billion in 2026 to reach USD 14.66 billion by 2031, at a CAGR of 10.45% during the forecast period (2026-2031).
This report is Segmented by Component (Air/Oxygen Blender, Active Humidifier, Single Heated Tube, and More), End-User (Hospitals & Intensive Care Units, and More), Application (Acute Respiratory Failure, and More), Patient Age Group (Neonatal & Pediatric, Adult, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global High-flow Nasal Cannula Market Trends and Insights
Rising Global Prevalence of Acute & Chronic Respiratory Diseases
The burden of COPD, which affected 200 million people and caused 3.2 million deaths in 2024, is pushing clinicians to escalate beyond conventional oxygen delivery methods. Asthma cases exceeded 350 million worldwide, while seasonal influenza remained the most detected pathogen in northern hemisphere surveillance. These epidemiological pressures have elevated demand for high-flow therapy that lowers readmissions and improves health-related quality-of-life scores, positioning the high-flow nasal cannula market as an essential pillar of modern respiratory care.
Technological Advancements in Heated Humidification & Integrated Flow Monitoring
Bench studies comparing leading devices showed that AIRVO 2, bellavista 1000, and HUMID-BH delivered closer to nominal dew-point at 37 °C, enhancing mucosal protection and secretion clearance. Computational fluid-dynamics modeling confirmed that optimized cannula geometry supports near-100% relative humidity in the nasopharynx, limiting airway obstruction. These innovations allow real-time titration of flow and FiO2, extend therapy beyond ICU walls, and differentiate offerings within the high-flow nasal cannula market.
High Capital & Operating Costs Versus Conventional Oxygen Delivery
Initial HFNC system investment can be 3-5 times the price of standard oxygen, and disposable circuits add recurring expenses. Cost-utility analysis in pediatric bronchiolitis showed CPAP costing USD 17,574 versus USD 29,421 for HFNC while yielding marginally higher QALYs. Budget constraints and infrastructure gaps, such as erratic power supply, slow uptake in developing economies and temper the high-flow nasal cannula market trajectory.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Applications of HFNC Beyond ICU into Emergency & Peri-operative Settings
- Growing Adoption of Home-based Oxygen Therapy & Tele-respiratory Care
- Limited Skilled Personnel & Training Gaps in Developing Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Active Humidifiers captured 33.82% of component revenue in 2025 thanks to their critical role in delivering gas at body-temperature humidity that protects mucosa. The high-flow nasal cannula market size for Active Humidifiers is set to rise at a steady 9.03% CAGR through 2031 as next-generation units embed algorithm-based dew-point control. Air/Oxygen Blenders follow, driven by demand for precise FiO2 titration compatible with electronic health-record integration. Nasal Cannula components will pace the segment with a 13.33% CAGR, reflecting design improvements that reduce pressure ulcers and support pediatric sizing. Manufacturers increasingly lock these components into proprietary ecosystems, reinforcing stickiness within the high-flow nasal cannula market.
Design refinements stem from computational fluid-dynamics work demonstrating smoother gas distribution and reduced interface shear. Single Heated Tubes gain traction as they minimize condensation, which can trigger alarms and therapy interruptions. Integrative product strategies that combine humidifier, blender, circuit, and cannula under a single brand umbrella are helping major vendors defend pricing and margins within the high-flow nasal cannula market.
Hospitals & Intensive Care Units commanded 47.30% of global revenue in 2025 as HFNC became standard in escalation algorithms from nasal prongs to ventilation. Meta-analysis of 10,230 patients confirmed a relative risk of 0.85 for subsequent invasive ventilation versus conventional oxygen, reinforcing hospital demand. Long-term Care Centers are adding HFNC to manage chronic hypoxemia in elderly residents, aided by portable trolley-mounted units.
Home-care Settings are projected to expand at a 12.57% CAGR, the fastest across end-users, buoyed by evidence of fewer COPD readmissions and advances in tele-respiratory dashboards. The high-flow nasal cannula market size for domiciliary use is expected to climb from USD 1.1 billion in 2025 to USD 2.23 billion by 2031. Pediatric retrospective data reveal low complication rates in children discharged on HFNC for upper-airway obstruction and CO2 clearance. Emerging payor models that reimburse remote monitoring further stimulate adoption, diversifying revenue streams in the high-flow nasal cannula market.
Complete Report Scope:
- By Component
- Air/Oxygen Blender
- Active Humidifier
- Single Heated Tube
- Nasal Cannula
- Other Consumables
- By End-user
- Hospitals & Intensive Care Units
- Long-term Care Centers
- Home-care Settings
- Other End-users
- By Application
- Acute Respiratory Failure
- Chronic Obstructive Pulmonary Disease
- Acute Heart Failure
- Other Applications
- By Patient Age Group
- Neonatal & Pediatric (0-17 yrs)
- Adult (18-64 yrs)
- Geriatric (65 yrs +)
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with 37.45% revenue share in 2025, buoyed by advanced reimbursement and 25 million diagnosed asthma cases in the United States. High-flow therapy migrated from ICUs to general wards, as bronchiolitis support successes drove a 4.8-fold rise in pediatric HFNC utilization between 2013 and 2022. The high-flow nasal cannula market size for home-care in the region is on track to exceed USD 1.58 billion by 2031 amid insurer acceptance of tele-respiratory bundles.
Asia Pacific is set for the fastest 10.86% CAGR, propelled by rising respiratory disease incidence, infrastructure investment, and localization by global vendors. WHO's 2024 compendium highlighted low-cost solutions such as PremieBreathe aimed at neonatal wards in low-resource hospitals. Government programs in China and India that subsidize non-invasive ventilation equipment will likely spur wider adoption in secondary-tier facilities.
Europe continues to adopt HFNC across Western health systems where robust clinical trials validate outcomes. Eastern European uptake is growing thanks to EU funding for respiratory care modernization. The Middle East & Africa and South America remain nascent yet promising; targeted clinician-training initiatives and modular HFNC systems suited to erratic electricity supply are expected to accelerate the high-flow nasal cannula market over the forecast horizon.
- Fisher & Paykel Healthcare
- Teleflex
- Resmed
- Vapotherm Inc.
- Masimo Corp. (TNI medical AG)
- Hamilton Medical
- Smiths Group
- Flexicare Medical
- Devatec S.A.
- Great Group Medical Co., Ltd.
- Medline Industries
- FisherBiotech GmbH
- Teijin Pharma Ltd.
- HEYER Medical AG
- BD (Becton, Dickinson & Co.)
- Cardinal Health
- GE HealthCare Technologies Inc.
- Koninklijke Philips
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Prevalence of Acute & Chronic Respiratory Diseases
- 4.2.2 Technological Advancements in Heated Humidification & Integrated Flow Monitoring
- 4.2.3 Expanding Applications of HFNC Beyond ICU into Emergency & Peri-operative Settings
- 4.2.4 Growing Adoption of Home-based Oxygen Therapy & Tele-respiratory Care
- 4.2.5 Favorable Reimbursement & Clinical Guidelines Supporting Non-invasive Oxygenation
- 4.2.6 Increase in Pre-term Birth Rates Necessitating Neonatal HFNC
- 4.3 Market Restraints
- 4.3.1 High Capital & Operating Costs Versus Conventional Oxygen Delivery
- 4.3.2 Limited Skilled Personnel & Training Gaps in Developing Regions
- 4.3.3 Infection-Control & Aerosol-Generation Concerns During Pandemics
- 4.3.4 Competitive Pressure from Alternative Non-invasive Ventilation (CPAP/BiPAP)
- 4.4 Regulatory Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Component
- 5.1.1 Air/Oxygen Blender
- 5.1.2 Active Humidifier
- 5.1.3 Single Heated Tube
- 5.1.4 Nasal Cannula
- 5.1.5 Other Consumables
- 5.2 By End-user
- 5.2.1 Hospitals & Intensive Care Units
- 5.2.2 Long-term Care Centers
- 5.2.3 Home-care Settings
- 5.2.4 Other End-users
- 5.3 By Application
- 5.3.1 Acute Respiratory Failure
- 5.3.2 Chronic Obstructive Pulmonary Disease
- 5.3.3 Acute Heart Failure
- 5.3.4 Other Applications
- 5.4 By Patient Age Group
- 5.4.1 Neonatal & Pediatric (0-17 yrs)
- 5.4.2 Adult (18-64 yrs)
- 5.4.3 Geriatric (65 yrs +)
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.4.1 Fisher & Paykel Healthcare Ltd.
- 6.4.2 Teleflex Incorporated
- 6.4.3 ResMed Inc.
- 6.4.4 Vapotherm Inc.
- 6.4.5 Masimo Corp. (TNI medical AG)
- 6.4.6 Hamilton Medical AG
- 6.4.7 Smiths Medical (ICU Medical)
- 6.4.8 Flexicare Medical Ltd.
- 6.4.9 Devatec S.A.
- 6.4.10 Great Group Medical Co., Ltd.
- 6.4.11 Medline Industries LP
- 6.4.12 FisherBiotech GmbH
- 6.4.13 Teijin Pharma Ltd.
- 6.4.14 HEYER Medical AG
- 6.4.15 BD (Becton, Dickinson & Co.)
- 6.4.16 Cardinal Health Inc.
- 6.4.17 GE HealthCare Technologies Inc.
- 6.4.18 Koninklijke Philips N.V.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


