

|
시장보고서
상품코드
2114737
해독제 의약품 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Alexipharmic Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
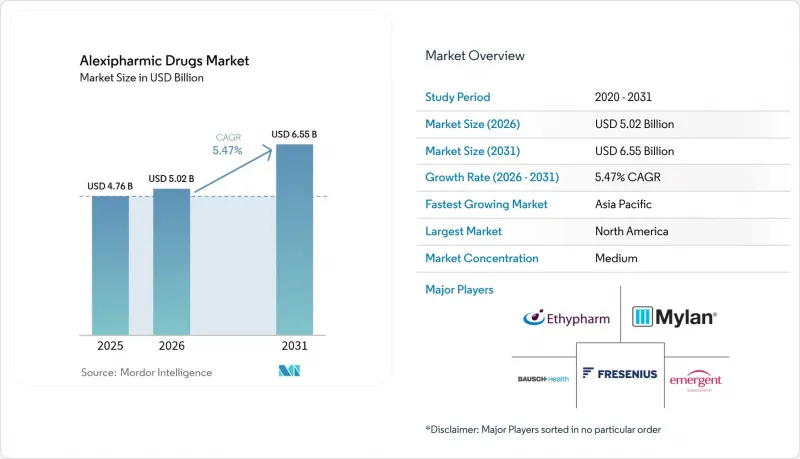
에 의하면, 2026년 해독제 의약품 시장 규모는 50억 2,000만 달러로 추정되고 2025년 47억 6,000만 달러에서 성장하여 2031년에는 65억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.47%를 기록하며 성장할 것으로 전망됩니다.
본 보고서는 약물 분류별(오피오이드 길항제, 벤조디아제핀 길항제, 기타), 투여 경로별(비경구, 기타), 제형별(용액, 자동 주사기, 기타), 유통 채널별(병원 약국, 기타),지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 해독제 의약품 시장 동향 및 인사이트
향정신성 약물 및 마약에 대한 의존도 증가
펜타닐의 효능을 능가하는 합성 오피오이드가 현재 미국과 유럽의 암시장에서 유통되고 있어, 과다 복용의 중증도 범위를 넓히고, 고용량 나록손 키트에 대한 수요를 높이고 있습니다. 신속 검출 기술의 미비로 인해 우발적 노출 위험이 증폭되면서, 병원과 구급대원들은 더 많은 재고를 확보할 수밖에 없는 상황입니다. 라틴아메리카와 동남아시아의 유통 네트워크는 북미의 소비 패턴을 반영하기 시작했으며, 해독제 수요 증가 추세는 앞으로도 지속될 것으로 보입니다. 제약사들은 수용체 포화를 극복하는 고농도 제제를 공동 개발함으로써 이러한 수요에 대응하고 있습니다. 새로운 유사 물질을 검출할 수 있는 테스트 스트립의 접근성이 확대됨에 따라 조기 개입이 촉진될 것으로 기대되지만, 단기적으로는 나록손 수요를 감소시키지는 않을 것으로 보입니다.
약물 보조 치료(MAT)에 대한 규제적 지원
2024년 FDA가 나르칸(Narcan) 비강 스프레이를 일반의약품(OTC)으로 재분류한 결정에 따라, 처방전이라는 장벽이 제거되어 약국, 학교, 공공시설에서 의료진의 감독 없이도 이 해독제를 비축할 수 있게 되었습니다. 현재 42개 주에서 메디케어와 메디케이드가 나록손 비용을 최소한의 본인 부담금으로 상환하고 있으며, 정기적인 구매 주문이 공공 예산에 포함되어 있습니다. 유럽에서도 유사한 움직임이 나타나고 있으며, 유럽의약품청(EMA)의 일원화된 승인으로 인해 새로운 비강 제제 시장 출시까지 걸리는 리드타임이 단축되고 있습니다. 이러한 움직임에 따라 지역 사회의 해로운 영향 감소(해악 감소) 노력은 보조금에 의존하는 일시적인 사업에서 영구적인 공중보건 정책으로 변모하고 있습니다. 더 많은 국가가 나록손의 보험 적용을 국가 의약품 목록에 포함함에 따라, 알렉시팜 시장은 광범위한 경제 사이클에 좌우되지 않는 예측 가능한 수량의 성장 기반을 확보하게 될 것입니다.
높은 치료비 및 입원비
미국에서는 시판되는 나록손 2정 팩의 본인 부담금이 평균 44달러로, 이로 인해 무보험 가구의 구매가 저해되고 있습니다. 병원의 구매 담당자는 해독제 재고 보충과 대량으로 취급되는 제네릭 의약품 간의 균형을 고려하여, 회전율이 불확실한 제품에 대해서는 주문량을 적게 잡는 경향이 있습니다. 특수한 시안화물용 해독제는 성인 1회분당 1,200달러를 초과하기도 하여, 지방 의료기관이 전체 치료 과정에 필요한 재고를 확보하는 것을 주저하게 만들고 있습니다. 주별 보험 환급액의 격차가 이러한 불균형을 더욱 확대시켜, 24시간 체제로 해독제를 이용할 수 없는 카운티가 곳곳에 산재해 있습니다. 메디케이드(Medicaid)의 본인 부담금 편차는 구매력을 더욱 세분화시키고, 수요의 균일성을 저해하며, 해독제 의약품 시장의 연평균 성장률(CAGR)을 끌어내리고 있습니다.
부문별 분석
오피오이드 길항제는 2025년 매출의 68.94%를 차지했으며, 선진국 전역의 임상 뉴스를 휩쓸고 있는 합성 오피오이드 위기의 심각성을 여실히 드러내고 있습니다. 나록손이 OTC(일반의약품)로 전환됨에 따라 주유소에서 대학 캠퍼스에 이르기까지 소비자의 접점이 비약적으로 증가하여, 이 부문의 우위가 확고해졌습니다. 시안화물 해독제는 틈새 시장이지만, 산업 규제 당국이 전기도금 공장 및 화학 물질 창고에 상비 키트 설치를 의무화함에 따라 8.33%라는 가장 높은 연평균 성장률(CAGR)을 보이고 있습니다. 벤조디아제핀 길항제는 선택적 수술 건수와 연동되어 한 자릿수 중반대의 성장률을 보이고 있습니다. 중금속 킬레이트제는 환경 사고 발생 시 일시적으로 수요가 증가하지만, 안정적인 기초 매출에 기여하고 있습니다. 경쟁 구도는 다양합니다. 오피오이드 길항제는 가격을 낮추는 제네릭 의약품 시장 진입에 직면한 반면, 시안화물 해독제는 특허로 보호받는 제제의 혜택을 받아 높은 이익률을 실현하고 있습니다.
다회 투여용 블리스터 팩이나 유아가 열기 어려운 비강용 어플리케이터로의 제품 확대는 포장 혁신이 가정, 직장, 응급 현장 등 폭넓은 환경에서의 이용 확대를 어떻게 뒷받침하고 있는지를 보여줍니다. 각 제조업체는 엄격한 조달 기준을 충족하는 유통기한 연장 및 변조 방지 씰을 통해 차별화를 꾀하고 있습니다.
2025년 매출의 61.25%를 비경구 제제가 차지했습니다. 이는 응급 부문에서 수분 이내에 혈장 중 농도 피크에 도달하는 정맥 내 투여를 우선시하고 있기 때문입니다. 한편, 비강 투여 제품은 특히 임상 인력이 없는 공공 장소에서 일반인이 스스로 투여할 수 있는 스프레이가 규제 당국의 승인을 받으면서 연평균 성장률(CAGR) 7.55%로 성장을 지속하고 있습니다. 경구 및 설하 투여는 급성기 증상의 역전보다는 유지 요법을 대상으로 하고 있기 때문에 규모는 작지만 꾸준한 틈새 시장을 형성하고 있습니다.
병원에서는 변동이 심한 냉장 조건하에서도 바이알의 안정성이 지속적으로 요구되고 있어, 내열성 제제의 연구 개발이 진행되고 있습니다. 한편, 지역 의료 프로그램에서는 ‘딸깍’ 소리가 나며 투여를 확인할 수 있는 스프레이 장치의 평가가 진행되고 있으며, 이를 통해 교육의 복잡성과 실수 위험이 줄어들고 있습니다. 새롭게 대두되고 있는 고효능 오피오이드의 위협에 대응한 투여량을 설정하고 있는 제조업체는 의약품 목록에서 우선순위가 높아지고 있습니다.
지역별 분석
북미는 2025년에도 전 세계 매출의 38.92%를 차지하며 계속해서 주도적인 위치를 유지했습니다. BARDA(생물 의학 연구 개발국)의 5년간 나록손 기본 협정 등 연방 정부의 투자는 예측 가능한 수거량을 확보하고, 공장의 생산 능력 계획을 안정화시키고 있습니다. 해악 감소(해악 경감) 전략의 일환으로 순찰차와 공공 도서관에 해독제가 배치되어, 임상 현장 이외의 이용 거점이 확대되고 있습니다. 2023년부터 2024년에 걸쳐 과다 복용으로 인한 사망률은 27% 감소했습니다. 이는 광범위한 배포의 효과를 시사하는 것이지만, 니타젠의 지속적인 존재로 인해 대량 주문은 유지되고 있습니다. 캐나다의 국가 계획에서는 고위험 처방에 대해 나록손을 무상으로 제공하는 데 자금이 배정되고 있으며, 멕시코의 새로운 산업 안전 규정에서는 금광 지역에서 시안화물 해독제 키트 소지가 의무화되어 있어, 이러한 조치들이 매출의 점진적인 증가에 기여하고 있습니다.
아시아태평양은 8.76%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있으며, 2031년까지 유럽을 추월할 전망입니다. 산업의 확장에 따라 금속 표면 처리 공정에서 시안화물에 대한 노출이 증가하고 있으며, 각국의 노동부는 현장에서 해독제를 비축할 것을 의무화하고 있습니다. 일본에서는 2024년에 디아제팜 비강 스프레이가 승인되어, 비주사제 형태에 대한 수용이 확대되고 있음을 시사합니다. 한편, 중국에서는 제네릭 의약품 파이프라인이 충실해지면서, 지방 자치단체의 비상 비축에 따른 가격 장벽이 낮아지고 있습니다. 인도는 API(원료의약품)의 주요 생산국으로서의 역할을 수행하고 있으며, 국내 기업들은 전 세계적인 공급 부족을 보완하고 수출 연계형 인센티브를 통해 부가가치를 창출할 수 있는 위치에 있습니다. 동남아시아 신흥 경제국에서는 위조 의약품 유입으로 인해 지역 사회 내 나록손 수요가 증가하고 있으며, 인도적 지원 예산이 해독제 조달에 배정되고 있습니다.
유럽에서는 신제제의 국경 간 유통을 원활하게 하는 EMA(유럽의약품청)의 집중 심사 절차에 힘입어 한 자릿수 중반대의 꾸준한 성장을 유지하고 있습니다. 브렉시트 이후의 재조정으로 인해 영국 중심의 허브에서 유럽 대륙의 창고로 일부 유통량이 이동했으나, 한편으로는 현지 충전·완제품 생산 라인을 활용하는 신규 진출기업도 유치되었습니다. 지역의 녹색 전환 정책은 시안화물 배출량 감축을 목표로 하고 있으며, 이로 인해 복구 프로젝트에서 해독제에 대한 수요가 간접적으로 증가하고 있습니다. 남용 방지 기능이 탑재된 오피오이드의 채택률은 스칸디나비아 시장에서 가장 높으며, 이는 장기적으로 나록손의 수량을 억제할 가능성이 있지만, 총 수량에 실질적인 영향을 미치기까지는 수년이 걸릴 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, alexipharmic drugs market size in 2026 is estimated at USD 5.02 billion, growing from 2025 value of USD 4.76 billion with 2031 projections showing USD 6.55 billion, growing at 5.47% CAGR over 2026-2031.
This report is Segmented by Drug Class (Opioid Antagonists, Benzodiazepine Antagonists, and More), Route of Administration (Parenteral, and More), Formulation (Solution, Auto-Injector, and More), Distribution Channel (Hospital Pharmacies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Alexipharmic Drugs Market Trends and Insights
Rising Dependence on Psychoactive & Narcotic Drugs
Synthetic opioids that exceed fentanyl potency now circulate in United States and European street markets, widening the overdose severity spectrum and prompting demand for higher-dose naloxone kits. Gaps in rapid detection technology amplify accidental exposure risks, pushing hospitals and first responders to maintain larger inventories. Distribution networks in Latin America and Southeast Asia are beginning to mirror North American consumption patterns, suggesting the upward trend in antidote volumes will persist. Pharmaceutical firms answer the need by co-developing concentrated formulations that overcome receptor saturation. Broader availability of test strips for new analogs is expected to support earlier intervention yet will not reduce naloxone demand in the short term.
Regulatory Backing for Medication-Assisted Treatment (MAT)
The 2024 FDA decision reclassifying Narcan nasal spray to over-the-counter status erased prescription barriers, allowing pharmacies, schools, and public venues to stock the antidote without clinician oversight. Medicare and Medicaid now reimburse naloxone with minimal copay in 42 states, embedding recurring purchase orders into public budgets. Europe follows similar cues with centralized EMA approvals that shorten lead times for new intranasal launches. These moves transform community harm-reduction initiatives from grant-funded pilots into permanent public health fixtures. As more countries embed naloxone coverage into national formularies, the alexipharmic market gains a predictable baseline of volume growth independent of broader economic cycles.
High Therapy & Hospitalization Costs
Out-of-pocket charges for a two-pack OTC naloxone carton average USD 44 in the United States, deterring purchase among uninsured households. Hospital buyers weigh antidote restocking against high-volume generics and may under-order products with uncertain turnover. Specialized cyanide antidotes can exceed USD 1,200 per adult dose, discouraging rural facilities from keeping full treatment courses. Insurance reimbursement disparities across states deepen gaps, leaving clusters of counties without 24-hour antidote access. Varying co-payment levels under Medicaid further fragment purchasing power, reducing the uniformity of demand and dampening the alexipharmic market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Escalating Synthetic-Opioid Fatalities in Lower-Income Regions
- Surge in Counterfeit-Drug Poisonings Triggering Naloxone Demand
- Rising Popularity of Abuse-Deterrent Opioid Formulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Opioid antagonists commanded 68.94% of 2025 revenue, underscoring the synthetic opioid emergency that dominates clinical headlines across developed economies. Naloxone's switch to OTC status multiplied consumer touchpoints, from gas stations to college campuses, cementing the segment's lead. Cyanide antidotes, while niche, exhibit the fastest 8.33% CAGR because industrial regulators now require on-site kits at electroplating plants and chemical warehouses. Benzodiazepine reversal agents show mid-single-digit growth tied to elective surgery volumes. Heavy-metal chelators gain episodically during environmental incidents yet contribute steady baseline turnover. Competitive profiles vary: opioid antagonists face generic entrants that suppress price, whereas cyanide antidotes benefit from patent-protected formulations, enabling premium margins.
Product expansion into multi-dose blister packs and child-resistant nasal applicators illustrates how packaging innovation supports broader user adoption across home, workplace, and first-responder settings. Manufacturers differentiate through shelf-life extensions and tamper-evident seals that satisfy stringent procurement criteria.
Parenteral formats represent 61.25% of 2025 sales because emergency departments prioritize intravenous onset that achieves peak plasma levels within minutes. Intranasal products, however, log a 7.55% CAGR as regulators approve self-administered sprays for layperson use, especially in public venues lacking clinical staff. Oral and sublingual deliveries address maintenance therapy rather than acute reversal and thus carve a smaller but steady niche.
Hospitals continue to demand vial stability under variable refrigeration conditions, prompting R&D into heat-tolerant formulations. Meanwhile, community health programs evaluate spray devices that provide audible click confirmation, reducing training complexity and error risk. Manufacturers that align dose strengths with emerging high-potency opioid threats gain formulary preference.
Complete Report Scope:
- By Drug Class
- Opioid Antagonists
- Benzodiazepine Antagonists
- Cyanide Antidotes
- Heavy-Metal Chelators
- Others
- By Route of Administration
- Parenteral
- Intranasal
- Oral & Sublingual
- By Formulation
- Solution
- Auto-Injector
- Nasal Spray
- Tablets & Capsules
- By Distribution Channel
- Hospital Pharmacies
- Retail & Community Pharmacies
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retains leadership with 38.92% of global sales in 2025. Federal investments such as BARDA's five-year naloxone framework agreement deliver predictable offtake that stabilizes factory capacity planning. Harm-reduction strategies embed antidotes into police cruisers and public libraries, expanding non-clinical utilization points. Overdose mortality eased 27% from 2023 to 2024, signaling effectiveness of widespread distribution, yet the persistence of nitazenes sustains bulk ordering. Canada's national plan funds free naloxone for high-risk prescriptions, and Mexico's new industrial safety code mandates cyanide antidote kits in gold-mining districts, contributing incremental upticks.
Asia Pacific posts the fastest 8.76% CAGR and is poised to surpass Europe by 2031. Industrial build-out raises cyanide exposure in metal finishing, prompting local labor ministries to enforce on-site antidote inventory. Japan approved diazepam nasal spray in 2024, signaling broader acceptance of non-injectables, while China's generics pipeline lowers price barriers for municipal emergency stockpiles. India's role as API powerhouse positions domestic firms to backfill global shortages and capture value through export-linked incentives. Emerging economies in Southeast Asia face counterfeit-drug influxes that increase community naloxone demands, steering humanitarian aid budgets toward antidote procurement.
Europe maintains steady mid-single-digit growth anchored by EMA's centralized procedure that eases cross-border circulation of new formulations. Post-Brexit recalibration diverted some volume from UK-centric hubs to continental warehouses, but also invited new entrants that leverage local fill-finish lines. Regional green-transition policies target reduction of cyanogenic emissions, indirectly boosting demand for detoxification agents during remediation projects. Abuse-deterrent opioid uptake is highest in Scandinavian markets, which could temper long-term naloxone volumes yet will take several years to materially influence totals.
- Emergent Bio Solutions
- Hikma Pharmaceuticals
- Pfizer
- Mylan N.V. (Viatris)
- Bausch Health
- Alkermes
- Amphastar Pharma
- Indivior
- Hikma (Ethypharm)
- Fresenius
- Mallinckrodt Pharmaceuticals
- SG Pharma
- Teva Pharma
- B. Braun
- Takeda (ANTIZOL)
- Merck
- Johnson & Johnson
- Novartis
- Glenmark Pharmaceuticals
- Cipla
- Dr. Reddy's
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Dependence on Psychoactive & Narcotic Drugs
- 4.2.2 Regulatory Backing for Medication-Assisted Treatment (MAT)
- 4.2.3 Escalating Synthetic-Opioid Fatalities in Lower-Income Regions
- 4.2.4 Surge in Counterfeit-Drug Poisonings Triggering Naloxone Demand
- 4.2.5 Government-Funded Community Naloxone Programs
- 4.2.6 Venture Funding in Intranasal & Auto-Injector Delivery Tech
- 4.3 Market Restraints
- 4.3.1 High Therapy & Hospitalization Costs
- 4.3.2 Rising Popularity of Abuse-Deterrent Opioid Formulations
- 4.3.3 Stigma Limiting Patient Access & Prescription Fill Rates
- 4.3.4 Supply-Chain Shocks for Key Antidotes' APIs
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Drug Class
- 5.1.1 Opioid Antagonists
- 5.1.2 Benzodiazepine Antagonists
- 5.1.3 Cyanide Antidotes
- 5.1.4 Heavy-Metal Chelators
- 5.1.5 Others
- 5.2 By Route of Administration
- 5.2.1 Parenteral
- 5.2.2 Intranasal
- 5.2.3 Oral & Sublingual
- 5.3 By Formulation
- 5.3.1 Solution
- 5.3.2 Auto-Injector
- 5.3.3 Nasal Spray
- 5.3.4 Tablets & Capsules
- 5.4 By Distribution Channel
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail & Community Pharmacies
- 5.4.3 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Emergent BioSolutions
- 6.3.2 Hikma Pharmaceuticals
- 6.3.3 Pfizer Inc.
- 6.3.4 Mylan N.V. (Viatris)
- 6.3.5 Bausch Health Companies Inc.
- 6.3.6 Alkermes
- 6.3.7 Amphastar Pharma
- 6.3.8 Indivior PLC
- 6.3.9 Hikma (Ethypharm)
- 6.3.10 Fresenius Kabi
- 6.3.11 Mallinckrodt
- 6.3.12 SG Pharma
- 6.3.13 Teva Pharma
- 6.3.14 B. Braun Melsungen
- 6.3.15 Takeda (ANTIZOL)
- 6.3.16 Merck & Co.
- 6.3.17 Johnson & Johnson
- 6.3.18 Novartis (Sandoz)
- 6.3.19 Glenmark
- 6.3.20 Cipla
- 6.3.21 Dr. Reddy's
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


