

|
시장보고서
상품코드
2114999
경화제 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Curing Agent - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 경화제 시장 규모는 2025년 75억 4,000만 달러에서 2026년에는 79억 2,000만 달러로 확대되어 2026년부터 2031년까지 CAGR 5.09%로 성장을 지속하여, 2031년에는 101억 6,000만 달러에 이를 것으로 예측됩니다.
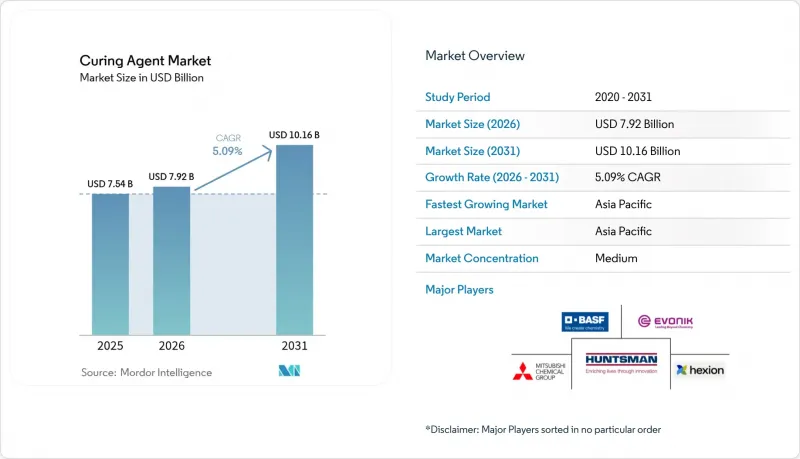
본 보고서에서는 산업을(에폭시, 폴리우레탄, 고무,아크릴, 기타)유형별, 용도별(페인트 및 코팅, 건축 및 건설, 접착제 및 실란트, 복합재료, 전기 및 전자, 기타), 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류하고 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계 경화제 시장 동향 및 인사이트
페인트 및 코팅 분야 수요 급증
현재, 건축용 및 보호용 도막의 조달 사양에서는 저VOC 및 수성 도료가 주류를 이루고 있으며, 이에 따라 배합 개발자들은 배출 상한치를 초과하지 않으면서도 경도, 자외선 저항성 및 부식 방지성을 발휘하는 경화제를 지정해야 합니다. EPIKURE 6874-WZ-50과 같은 새로운 수성 폴리아미드 화학 물질은 염수 분무 시험에서 성능을 유지하면서 분산 안정성을 향상시킵니다. 인프라 개보수로 인해 부식 방지 프라이머 수요가 증가하고 있으며, IoT를 활용한 표면 진단 기술로 인해 개보수 주기가 가속화되어 수요가 더욱 확대되고 있습니다. 지속가능성에 대한 소비자 인식이 높아짐에 따라, 수지 제조업체들은 기계적 성능이 뒤지지 않는 바이오 경화제의 활용을 추진하고 있습니다. 이러한 요인들로 인해 전 세계 경화제 시장 전반 수요가 지속적으로 상승하고 있습니다.
인프라 붐이 건축 및 건설용 복합재 시장을 견인
아시아태평양의 정부 주도 메가 프로젝트에서는 교량 데크판, 파사드, 철근에 섬유 강화 폴리머가 채택되고 있습니다. 이러한 소재는 시공 노동력을 절감하고 부식으로 인한 비용을 줄이기 위함입니다. 미국에서는 초당파적인 인프라 자금 조달을 통해 복합재 거더 교체에 대한 보조금이 마련되었으며, 고습도 환경에서의 경화 일정에 최적화된 반응성 아민계 제품의 수주가 증가하고 있습니다. 인도가 2025년까지 화학제품 생산액 3,000억 달러를 목표로 하는 노력에 따라 특수 아민 및 촉진제의 국내 공급이 강화되어 지역의 자급자족이 촉진되고 있습니다. 급속한 도시화로 인해 구조용 접착제 소비가 지속되고 있으며, 이는 경화제 시장을 더욱 부양하고 있습니다.
아민 및 무수물에 대한 엄격한 VOC 및 REACH 규제
유럽의 2025년 REACH 개정안에서는 PFAS 규제가 확대되고 배출 기준치가 하향 조정됨에 따라, 배합 제조업체들은 보다 안전한 촉진제를 사용하여 에폭시 및 폴리우레탄계 제품을 재설계해야만 합니다. 디이소시아네이트에 대한 교육 의무화로 간접 비용이 증가하고 있으며, 2025년 1월 SVHC 갱신에 따라 아민 유도체에 대한 문서화 요건이 강화될 예정입니다. 미국 EPA의 NMP에 대한 유사한 움직임은 도료 수출업체들에게 복잡성을 가중시키고 있습니다. 하류 시장에서는 자동차 OEM 각사가 현재 재료 정보의 완전한 공개를 면밀히 검토하고 있어, 바이오 또는 초저취 대체재로 전환해야 한다는 압력이 강해지고 있습니다. 규정 준수 비용은 중소 제조업체에게 부담이 되고 있지만, 친환경 포트폴리오를 보유한 대형 종합 제조업체는 경화제 시장에서의 점유율을 서서히 확대되고 있습니다.
부문 분석
2025년, 경화제 시장에서 에폭시계 시스템이 가장 큰 매출을 창출하고, 2031년까지의 연평균 성장률(CAGR) 6.29%는 다른 모든 화학 부문을 능가할 것입니다. 이 부문에서 알킬 아민 블렌드는 10°C 미만의 온도에서도 박막 경화가 가능하게 하는 반면, 폴리아미드는 선박용 프라이머에 내습성을 부여합니다. Huntsman, BASF, Evonik은 후방 통합된 아민 생산 라인과 지역별 혼합 공장을 결합하여 비용 면에서의 우위와 기술 지원을 유지하고 있습니다.
폴리우레탄계 경화제는 유연한 바닥재 및 스프레이 폼 분야에서 여전히 확고한 입지를 유지하고 있지만, 이소시아네이트 규제로 인해 열에 의해 기능성이 방출되는 블록 구조를 가진 에폭시-폴리우레탄 하이브리드 방식이 촉진되고 있습니다. 실리콘 및 페놀계 경화제는 유전 안정성이 극히 중요한 항공우주 분야와 고온 전자기기 분야에서 여전히 필수적인 존재입니다. 고무 및 아크릴계 배합물은 틈새 시장인 실링, 타이어, UV 경화 분야 수요를 충족시키며, 꾸준하지만 완만한 성장에 기여하고 있습니다.
지역별 분석
아시아태평양은 수량 및 금액 양면에서 시장을 독점하고 있으며, 2025년에는 전 세계 매출의 44.75%를 차지하고, 2031년까지 연평균 성장률(CAGR) 6.46%로 성장을 이어갈 전망입니다. 이 지역공급망은 아민 합성의 일체형 생산, 경쟁력 있는 노동력, 하류 사용자와의 근접성을 특징으로 하며, 이를 통해 현지 제조업체들은 가격 책정 및 리드타임 측면에서 유연성을 발휘하고 있습니다. 중국의 ‘중국 제조 2025’ 이니셔티브는 범용 에폭시 희석제에서 특수 가교제로 국내 생산을 고도화하여, 현지 터빈 및 반도체 제조업체를 동시에 지원하고 있습니다. 인도의 생산 연계형 인센티브 제도는 폴리에테르아민 및 페날카민 제조 시설에 다국적 기업의 자본을 유치하여 수입 의존도를 낮추는 동시에 남아시아의 경화제 시장을 견인하고 있습니다.
북미는 셰일가스를 원료로 활용할 수 있고 풍력 발전 용량이 대폭 증가하는 혜택을 누리고 있지만, VOC 규제안의 엄격화와 PFAS에 대한 감시 강화로 인해 연구개발비가 증가하고 있습니다. 주요 배합 제조업체들은 차별화를 유지하고 보조금을 확보하기 위해, 질량 균형에 기반한 바이오 유래도 평가 모델 및 순환형 수명 주기 종료(사용 후 제품 처리) 옵션으로의 전환을 추진하고 있습니다. 유럽은 전력 가격 급등과 REACH 규제의 기준치 변경에 직면해 있어, 사업자들은 고수익률의 맞춤형 솔루션으로의 전환을 강요받는 한편, Scope 2 배출량을 감축하기 위해 그린 수소를 동력원으로 하는 플랜트의 규모 확대를 추진하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.26According to Mordor Intelligence, the curing agent market size is expected to grow from USD 7.54 billion in 2025 to USD 7.92 billion in 2026 and is forecast to reach USD 10.16 billion by 2031 at 5.09% CAGR over 2026-2031.
This report Segments the Industry by (Epoxy, Polyurethane, Rubber, Acrylic, and Other Types), Application (Paints and Coatings, Building and Construction, Adhesives and Sealants, Composites, Electrical and Electronics, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Curing Agent Market Trends and Insights
Surging Demand from Paints and Coatings
Low-VOC and waterborne coatings now dominate procurement specifications for architectural and protective layers, prompting formulators to specify curing agents that deliver hardness, UV resistance, and corrosion protection without breaching emission caps. New waterborne polyamide chemistries like EPIKURE 6874-WZ-50 simplify dispersion stability while maintaining salt-spray performance. Infrastructure refurbishment raises volumes for anti-corrosion primers, and IoT-enabled surface diagnostics accelerate renovation cycles, driving additional throughput. Growing consumer awareness of sustainability pushes resin producers to leverage bio-based hardeners that match mechanical performance. These factors continue to lift demand across the global curing agent market.
Infrastructure Boom Driving Building and Construction Composites
Government-backed megaprojects in Asia Pacific favor fiber-reinforced polymers for bridge decks, facades, and rebar, as these materials reduce installation labor and mitigate corrosion costs. In the United States, bipartisan infrastructure funding has opened grants for composite girder replacement, increasing purchase orders for reactive amine systems optimized for high-humidity cure schedules. India's push for USD 300 billion chemical output by 2025 strengthens the domestic supply of specialty amines and accelerators, reinforcing regional self-sufficiency. Rapid urbanization sustains consumption of structural adhesives, further lifting the curing agent market.
Stringent VOC and REACH Regulations on Amines and Anhydrides
Europe's 2025 REACH revision extends PFAS curbs and lowers emission thresholds, compelling formulators to redesign epoxy and polyurethane systems around safer accelerators. Diisocyanate training mandates add indirect cost, and the January 2025 SVHC update tightens documentation for amine derivatives. Similar moves by the U.S. EPA on NMP heighten complexity for coatings exporters. Downstream, automotive OEMs now screen full material disclosures, elevating switching pressure toward bio-based or ultra-low-odor alternatives. Compliance expenses weigh on smaller producers, but integrated majors with green portfolios gradually consolidate share inside the curing agent market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Expansion of Wind-Energy Blade Production
- Ultra-Fast Curing Agents Enabling 3D-Printing Resins
- Volatility in Petro-Derived Raw-Material Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Epoxy systems generated the largest revenue within the curing agent market in 2025, and their 6.29% CAGR through 2031 outpaces every other chemistry category. Within this segment, aliphatic amine blends enable thin-film cure at temperatures below 10 °C, while polyamides contribute moisture tolerance for marine primers. Huntsman, BASF, and Evonik combine backward-integrated amine chains with regional mixing plants, sustaining their cost edge and technical support.
Polyurethane hardeners continue to hold strong positions in flexible flooring and spray foams, yet isocyanate regulation encourages hybrid epoxy-polyurethane routes with blocked functionality that releases under heat. Silicone and phenolic curing agents remain indispensable for aerospace and high-temperature electronics, where dielectric stability is critical. Rubber and acrylic formulations address niche sealing, tire, and UV-cure needs, contributing steady but slower growth.
Complete Report Scope:
- By Type
- Epoxy
- Polyurethane
- Rubber
- Acrylic
- Other Types (Silicone, Phenolic, etc.)
- By Application
- Paints and Coatings
- Building and Construction
- Adhesives and Sealants
- Composites (Wind, Marine, Sports)
- Electrical and Electronics (Potting, PCB, EV batteries)
- Other Applications (3D-printing, Flooring, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific dominates on both volume and value, holding 44.75% of global sales in 2025 and riding a 6.46% CAGR to 2031. Regional supply chains feature integrated amine synthesis, competitive labor, and proximity to downstream users, giving local producers agility in pricing and lead time. China's Made-in-China 2025 initiative upgrades domestic output from commodity epoxy diluents toward specialty crosslinkers, supporting local turbine and semiconductor customers simultaneously. India's production-linked incentive framework attracts multinational capital into polyetheramine and phenalkamine facilities, cutting import dependency and propelling the curing agent market in South Asia.
North America benefits from shale gas feedstock and high wind-capacity additions, yet stricter VOC proposals and PFAS scrutiny raise research and development outlays. Leading formulators move toward mass-balance bio-attribution models and circular end-of-life options to maintain differentiation and secure grants. Europe confronts elevated electricity prices and evolving REACH thresholds, compelling operators to migrate toward high-margin custom solutions while scaling green hydrogen-powered plants to lower Scope 2 emissions.
- Alfa Chemicals
- Atul Ltd.
- BASF
- Cardolite Corporation
- DIC Corporation
- Evonik Industries, AG
- Hexion Inc.
- Huntsman International LLC
- Incorez Ltd.
- Kukdo Chemical Co.
- Mitsubishi Chemical Corporation
- Olin Corporation
- Palmer International
- Supreme Polytech Pvt Ltd.
- Wanhua Chemical Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Demand from Paints and Coatings
- 4.2.2 Infrastructure Boom Driving Building and Construction Composites
- 4.2.3 Rapid Expansion of Wind-Energy Blade Production
- 4.2.4 Shift to Bio-Based Cashew Nutshell Liquid (CNSL) and Lignin Curing Chemistries
- 4.2.5 Ultra-Fast Curing Agents Enabling 3D-Printing Resins
- 4.3 Market Restraints
- 4.3.1 Stringent VOC and REACH Regulations on Amines and Anhydrides
- 4.3.2 Volatility in Petro-Derived Raw-Material Costs
- 4.3.3 Supply-Chain Concentration of Specialty Amines in Asia Pacific
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Epoxy
- 5.1.2 Polyurethane
- 5.1.3 Rubber
- 5.1.4 Acrylic
- 5.1.5 Other Types (Silicone, Phenolic, etc.)
- 5.2 By Application
- 5.2.1 Paints and Coatings
- 5.2.2 Building and Construction
- 5.2.3 Adhesives and Sealants
- 5.2.4 Composites (Wind, Marine, Sports)
- 5.2.5 Electrical and Electronics (Potting, PCB, EV batteries)
- 5.2.6 Other Applications (3D-printing, Flooring, etc.)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (Mergers and Acquisitions, JVs, Partnerships)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Alfa Chemicals
- 6.4.2 Atul Ltd.
- 6.4.3 BASF
- 6.4.4 Cardolite Corporation
- 6.4.5 DIC Corporation
- 6.4.6 Evonik Industries, AG
- 6.4.7 Hexion Inc.
- 6.4.8 Huntsman International LLC
- 6.4.9 Incorez Ltd.
- 6.4.10 Kukdo Chemical Co.
- 6.4.11 Mitsubishi Chemical Corporation
- 6.4.12 Olin Corporation
- 6.4.13 Palmer International
- 6.4.14 Supreme Polytech Pvt Ltd.
- 6.4.15 Wanhua Chemical Group
7 Market Opportunities and Future Outlook
- 7.1 Development of Environmental Friendly Low or Non-VOC Curing Agents
- 7.2 White-space and unmet-need assessment


