

|
시장보고서
상품코드
2116073
의료용 특수 백 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Medical Specialty Bags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
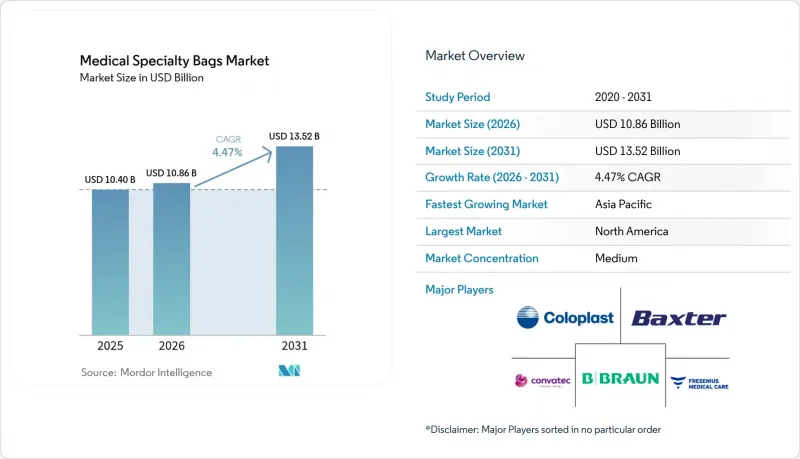
에 따르면 2026년 의료용 특수 백 시장 규모는 108억 6,000만 달러로 추정되며, 2025년 104억 달러에서 확대되어 2031년에는 135억 2,000만 달러에 달할 것으로 예측됩니다. 2026년부터 2031년까지 CAGR은 4.47%가 될 전망입니다.
본 보고서는 제품별(수액백, 장루백, 멸균 수집·배액백, 지속적 외래 복막투석(CAPD) 백 등), 소재별(PVC, PE·PP 등), 최종사용자별(병원, 외래·데이케어 센터 등), 지역별(북미, 유럽 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 의료용 특수 백 시장의 동향 및 인사이트
만성 질환 및 외과 수술 부담의 증가
대장암 및 염증성 장질환의 유병률은 계속 상승하고 있으며, 전 세계적으로 영구적 및 일시적 장루 형성 건수가 증가하고 있습니다. 병원에서는 재입원 위험을 줄이기 위해 파우치 시스템의 표준화가 진행되고 있으며, 장루 주변 피부의 건강성을 높이는 누수 방지형 오스토미 키트에 대한 수요가 촉진되고 있습니다. 각 제조사는 착용 시간과 편안함을 향상시키기 위해 하이드로콜로이드나 실리콘 결합층을 추가하여 환자의 치료 순응도를 높이고 있습니다. 퇴원 시 지원 프로그램에서는 환자에게 파우치 관리 방법을 지도하고 있으며, 이를 통해 의료용 특수 파우치 시장의 지속적인 수요가 더욱 공고해지고 있습니다. 이러한 동향으로 인해 선택적 수술 시행률이 변동하더라도 시장의 기초적인 성장은 유지되고 있습니다.
재택 신장 치료에서 CAPD의 보급 가속화
아시아태평양 및 라틴아메리카의 공적 보험 기관들은 입원 병상 부족을 완화하고 삶의 질을 향상시키기 위해 재택 투석에 대한 보험 적용을 확대하고 있습니다. ‘Carry Life UF’ 플랫폼은 정확한 혈당 조절을 통해 한외여과 및 나트륨 제거를 증가시켜, 환자가 목표 체액 범위를 유지할 수 있도록 돕는 것으로 나타났습니다. 교육용 앱과 원격 모니터링을 통해 합병증 발생률을 낮출 수 있기 때문에 임상의들은 치료 초기 단계부터 지속성 복막투석(CAPD)을 권장하고 있습니다. CAPD용 용액 및 배액백 제조업체들은 다년간의 공급 계약을 보장하는 키트 번들링 정책의 혜택을 받고 있습니다. 그 결과, CAPD는 의료용 특수 백 시장에서 여전히 가장 빠르게 성장하는 제품 라인으로 자리 잡고 있습니다.
신흥국에서의 보험 환급 격차
시술 건수는 증가하고 있지만, 저소득 지역의 많은 공적 보험은 첨단 오스토미 키트나 CAPD 키트의 비용을 전액 보상하지 않아, 환자들은 비용의 상당 부분을 본인 부담해야 하는 상황에 처해 있습니다. 높은 본인 부담금은 고품질이면서 피부에 자극이 적은 소재의 채택을 방해하여, 세계 공급업체의 수익 확대 가능성을 저해하고 있습니다. 보험 제도의 현대화는 진행되고 있으나, 의료 예산에 대한 인플레이션 압력으로 인해 보조금 협상이 장기화되고 있습니다. 현지 유통업체들은 저비용 PVC 제품을 선호하는 경향이 있어, 친환경 폴리머의 도입이 지연되고 있습니다. 향후 단계적 가격 책정 모델이나 민간 보험 가입자층의 확대에 따라 이러한 격차는 줄어들 수 있겠지만, 당분간은 의료용 특수 백 시장에 부정적인 영향이 지속될 전망입니다.
부문 분석
2025년에도 대장암 수술 및 염증성 장질환에 따른 절제 수술로 인해 장루 형성 건수가 안정적으로 유지됨에 따라, 장루 주머니는 의료용 특수 주머니 시장에서 32.02%의 점유율을 차지하며 여전히 최대 제품 라인으로 자리매김했습니다. 병원에서는 착용 기간을 연장하고, 장루 주변 피부염 발생률을 낮추며, 예정에 없던 내원을 줄여주는 다층 배리어 필름이 선호되고 있습니다. 주요 OEM 제조업체들은 폭넓은 사이즈 범위의 폐쇄형 및 배액 가능한 타입을 공급하고 있으며, 이는 그룹 계약에 따른 일괄 구매를 촉진하고 있습니다. 환자의 해부학적 구조에 맞춰 3D 프린팅된 볼록형 베이스 플레이트 등 지속적인 기술 혁신을 통해 밀봉성이 향상되면서, 의료용 특수 백 시장 전체에서 브랜드 충성도가 높아지고 있습니다.
대조적으로, CAPD 백의 제품 포트폴리오는 연평균 성장률(CAGR) 8.23%로 가장 빠른 성장세를 기록하고 있으며, 이는 재택 신장 치료에 대한 보험사 측의 인센티브를 반영한 것입니다. 새로운 저포도당 용액은 막의 수명을 연장하고 당뇨병 환자의 치료 적응 범위를 확대합니다. 즉시 사용 가능한 트윈 컴파트먼트 백은 스파이크 조작 절차를 최소화하여 액체 교환 시 복막염 위험을 줄여줍니다. 인도와 베트남에 위치한 지역 생산 거점은 리드 타임을 단축하고, 수지 부족 시에도 공급의 연속성을 보장합니다. 임상 전문가를 위한 교육 프로그램이 확산됨에 따라, CAPD의 보급 곡선은 인슐린 펌프의 동향과 유사하며, 대도시권을 넘어 지속적인 성장이 예상됩니다.
지역별 분석
북미는 2025년에 전 세계 매출의 35.82%를 차지했으며, 그 배경으로는 견실한 보험 적용 범위와 신형 백의 도입을 가속화하는 신속한 승인 절차가 꼽힙니다. 이 지역의 ASC(외래 수술 센터) 급증은 소규모 시술실에 설치할 수 있는 소형 마취·배액 세트에 대한 수요를 뒷받침하고 있습니다. 한편, 허리케인으로 인한 공장 가동 중단은 점적 백 생산에서 지리적 중복성의 중요성을 부각시키고 있습니다. 캐나다의 일회용 플라스틱 감축을 위한 국가 전략에 따라 퇴비화 가능한 오스토미 파우치 시범 프로그램이 가속화되고 있으며, 멕시코의 마키라도라 회랑에서는 국내 및 미국 시설 모두에 저비용 PVC 유닛이 공급되어 국경을 초월한 공급 탄력성이 강화되고 있습니다.
아시아태평양은 고령화와 국민건강보험의 확대에 힘입어 연평균 성장률(CAGR) 8.16%라는 가장 높은 성장률을 기록했습니다. 중국의 수량 기반 조달로 인해 평균 판매 가격에는 하락 압력이 가해지고 있지만, 높은 단위 처리량 덕분에 공급업체의 이익률은 유지되고 있습니다. 일본의 재택 투석 보급률은 15%를 넘어섰으며, RFID 칩이 탑재된 자동 교체용 백 세트에 대한 얼리 어답터층의 수요가 발생하고 있습니다. 인도에서는 주 정부 보험 제도를 통해 저소득층을 위한 장루 관리 용품에 보조금이 지급되면서 장루 사용자의 기반이 확대되고 있습니다. 동남아시아의 의료기기 단지는 외국인 직접 투자를 유치하여 수액백 및 배액백의 현지 공급을 촉진하는 한편, 해당 지역을 의료용 특수 백 시장의 제조 거점으로 확고히 자리매김하고 있습니다.
유럽은 계속해서 안정적인 수요원으로 자리 잡고 있으며, 엄격한 환경 지침에 따라 DEHP 가소화 PVC에서 재활용 가능하거나 바이오 기반 필름으로의 전환이 진행되고 있습니다. 독일과 북유럽 국가의 병원에서는 입찰에 수명주기 지표를 반영하고, 검증된 탄소발자국 정보를 공개하는 공급업체를 우대하고 있습니다. 프랑스에서 가정 영양 솔루션에 대한 보험 환급은 조제 자동화에 대응한 다층 EVA/PP 백의 판매를 뒷받침하고 있습니다. 영국에서는 충전 수준 데이터를 지역 간호사에게 전송하여 예정에 없던 병원 방문을 줄이는 스마트 오스토미 파우치에 관한 시범 연구에 자금을 지원하고 있습니다. 전반적으로, 유럽 대륙에서 지속가능성에 대한 인센티브와 삶의 질(QOL)에 기반한 보험 급여를 결합한 정책 덕분에 의료용 특수 파우치 시장은 계속해서 한 자릿수 중반대의 성장세를 유지하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.26According to Mordor Intelligence, medical specialty bags market size in 2026 is estimated at USD 10.86 billion, growing from 2025 value of USD 10.40 billion with 2031 projections showing USD 13.52 billion, growing at 4.47% CAGR over 2026-2031.
This report is Segmented by Product (Intravenous Fluid Bags, Ostomy Bags, Sterile Collection & Drainage Bags, Continuous Ambulatory Peritoneal Dialysis (CAPD) Bags, and More), Material (PVC, PE & PP, and More), End-User (Hospitals, Ambulatory & Day-Care Centers, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Medical Specialty Bags Market Trends and Insights
Rising Burden of Chronic Diseases and Surgical Procedures
Colorectal cancer and inflammatory bowel disease prevalence continues to rise, elevating permanent and temporary stoma creation volumes worldwide. Hospitals standardize pouching systems to lower readmission risks, spurring orders for leak-resistant ostomy kits that improve peristomal skin integrity. Manufacturers add hydrocolloid and silicone coupling layers to boost wear-time and comfort, encouraging patient adherence. Integrated discharge programs train patients in pouch maintenance, further anchoring recurring demand within the medical specialty bags market. These developments sustain baseline growth even when elective procedure rates fluctuate.
Accelerated Uptake of CAPD for Home Renal Therapy
Public payers in Asia-Pacific and Latin America increasingly reimburse home-based dialysis to ease inpatient bed pressure and enhance quality of life. The Carry Life UF platform underscores how precise glucose titration can increase ultrafiltration and sodium removal, helping patients stay in target fluid ranges. Training apps and tele-monitoring keep complication rates low, prompting clinicians to recommend Continuous Ambulatory Peritoneal Dialysis earlier in the treatment journey. Producers of CAPD solution and drainage bags benefit from kit bundling policies, which lock in multi-year supply contracts. Consequently, CAPD continues to be the fastest-growing product line inside the medical specialty bags market.
Reimbursement Gaps in Emerging Economies
While procedure volumes climb, many public insurers in lower-income regions do not reimburse advanced ostomy or CAPD kits in full, forcing patients to self-pay significant portions. Out-of-pocket burdens reduce uptake of premium, skin-friendly materials, dampening revenue potential for global suppliers. Insurance modernization is under way, yet inflationary pressures on health budgets prolong subsidy negotiations. Local distributors often favor low-cost PVC options, stalling adoption of greener polymers. Over time, tiered pricing models and expanded private insurance pools may narrow the gap, but near-term drag on the medical specialty bags market persists.
Other drivers and restraints analyzed in the detailed report include:
- Transition to PVC-Free and Recyclable Polymers
- Growth of Ambulatory Care Models and Digitalized Bag Solutions
- Extended Regulatory Timelines for Novel Polymers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ostomy bags remained the largest product line with a 32.02% medical specialty bags market share in 2025 as colorectal cancer surgeries and inflammatory bowel disease resections kept stoma creation steady. Hospitals favor multi-layer barrier films that prolong wear time, lowering peristomal dermatitis incidence and reducing unscheduled clinic visits. Leading OEMs supply closed-end and drainable variants in a wide size range, which drives bulk purchasing under group contracts. Continuous innovation, including 3-D-printed convex baseplates tailored to patient anatomy, improves seal integrity and boosts brand loyalty in the broader medical specialty bags market.
The CAPD bag portfolio, by contrast, posted the fastest expansion at an 8.23% CAGR, reflecting payer incentives for home renal therapies. New low-glucose solutions extend membrane life and widen treatment eligibility for diabetic populations. Ready-to-use twin-compartment bags minimize spiking steps, reducing peritonitis risk during exchanges. Regional manufacturing hubs in India and Vietnam shorten lead times and protect supply continuity during resin shortages. As clinical specialists' education programs gain traction, CAPD adoption curves mirror insulin pump trends, signaling sustained growth beyond large urban centers.
Complete Report Scope:
- By Product
- Intravenous (IV) Fluid Bags
- Ostomy Bags
- Sterile Collection & Drainage Bags
- Continuous Ambulatory Peritoneal Dialysis (CAPD) Bags
- Anesthesia & Resuscitation Bags
- Blood & Blood-Component Transfer Bags
- Others
- By Material
- PVC
- PE & PP
- EVA & Other Copolymers
- Silicone & TPU
- Bio-based / Compostable Polymers
- By End-user
- Hospitals
- Ambulatory & Day-Care Centers
- Home-Care Settings
- Long-term Care Facilities
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 35.82% of global revenue in 2025, anchored by robust insurance coverage and rapid clearance pathways that speed novel bag introductions. The region's ASC boom fuels demand for compact anesthesia and drainage sets that fit small procedure rooms, while hurricane-related factory disruptions spotlight the importance of geographic redundancy in IV bag production. Canada's national strategy to cut single-use plastics accelerates pilot programs for compostable ostomy pouches, and Mexico's maquiladora corridor supplies low-cost PVC units to both domestic and U.S. facilities, reinforcing cross-border supply resilience.
Asia-Pacific registered the fastest growth at an 8.16% CAGR, propelled by aging populations and expanding universal health coverage. China's volume-based procurement exerts downward pressure on average selling prices, yet high unit throughput preserves supplier margins. Japanese home-dialysis penetration exceeds 15%, creating early-adopter demand for automated exchange bag sets with RFID chips. India subsidizes stoma care appliances for low-income groups through state insurance schemes, broadening the base of ostomy users. Southeast Asia's medical device parks attract foreign direct investment, fostering local supply of infusion and drainage bags and cementing the region as a manufacturing pivot in the medical specialty bags market.
Europe remains a steady contributor, with stringent environmental directives pushing conversion from DEHP-plasticized PVC toward recyclable or bio-based films. Hospitals in Germany and the Nordics embed life-cycle metrics into tenders, rewarding vendors with validated carbon-footprint disclosures. France's reimbursement of home nutrition solutions boosts sales of multilayer EVA/PP bags compatible with compounding automation. The United Kingdom funds pilot studies on smart ostomy pouches that transmit fill-level data to community nurses, reducing unplanned clinic visits. Overall, the continent's policy mix of sustainability incentives and quality-of-life reimbursement preserves mid-single-digit expansion in the medical specialty bags market.
- Ambu
- B. Braun
- Baxter
- Coloplast
- ConvaTec Group plc
- Hollister
- Kawasumi Laboratories
- MacoPharma
- Nolato
- Danaher
- Cardinal Health
- Fresenius
- Beckton Dickinson
- Terumo
- ICU Medical
- Teleflex
- Poly Medicure Ltd.
- Weigao Group Medical Polymer Co.
- Renolit SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Burden Of Chronic Diseases & Surgeries
- 4.2.2 Rapid Adoption Of CAPD For Home Renal Care
- 4.2.3 Shift Toward PVC-Free & Recyclable Polymers
- 4.2.4 Expansion Of Ambulatory & Day-Care Centers
- 4.2.5 AI-Enabled Production Line Quality Control
- 4.2.6 Hospital Demand For RFID-/Iot-Tagged Smart Bags
- 4.3 Market Restraints
- 4.3.1 Reimbursement Gaps In Emerging Economies
- 4.3.2 Long Regulatory Approval Cycles For Novel Polymers
- 4.3.3 Volatile Prices Of Medical-Grade Resins
- 4.3.4 Rising ESG Scrutiny On Single-Use Devices
- 4.4 Porter's Five Forces
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitute Products
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Intravenous (IV) Fluid Bags
- 5.1.2 Ostomy Bags
- 5.1.3 Sterile Collection & Drainage Bags
- 5.1.4 Continuous Ambulatory Peritoneal Dialysis (CAPD) Bags
- 5.1.5 Anesthesia & Resuscitation Bags
- 5.1.6 Blood & Blood-Component Transfer Bags
- 5.1.7 Others
- 5.2 By Material
- 5.2.1 PVC
- 5.2.2 PE & PP
- 5.2.3 EVA & Other Copolymers
- 5.2.4 Silicone & TPU
- 5.2.5 Bio-based / Compostable Polymers
- 5.3 By End-user
- 5.3.1 Hospitals
- 5.3.2 Ambulatory & Day-Care Centers
- 5.3.3 Home-Care Settings
- 5.3.4 Long-term Care Facilities
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Ambu A/S
- 6.3.2 B. Braun Melsungen AG
- 6.3.3 Baxter International Inc.
- 6.3.4 Coloplast A/S
- 6.3.5 ConvaTec Group plc
- 6.3.6 Hollister Incorporated
- 6.3.7 Kawasumi Laboratories Inc.
- 6.3.8 Macopharma SA
- 6.3.9 Nolato AB
- 6.3.10 Danaher Corporation (Pall Corporation)
- 6.3.11 Cardinal Health Inc.
- 6.3.12 Fresenius Medical Care AG & Co. KGaA
- 6.3.13 BD (Becton, Dickinson and Company)
- 6.3.14 Terumo Corporation
- 6.3.15 ICU Medical Inc.
- 6.3.16 Teleflex Inc.
- 6.3.17 Poly Medicure Ltd.
- 6.3.18 Weigao Group Medical Polymer Co.
- 6.3.19 Renolit SE
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


