

|
시장보고서
상품코드
2124176
압력 주입 백 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Pressure Infusion Bags - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
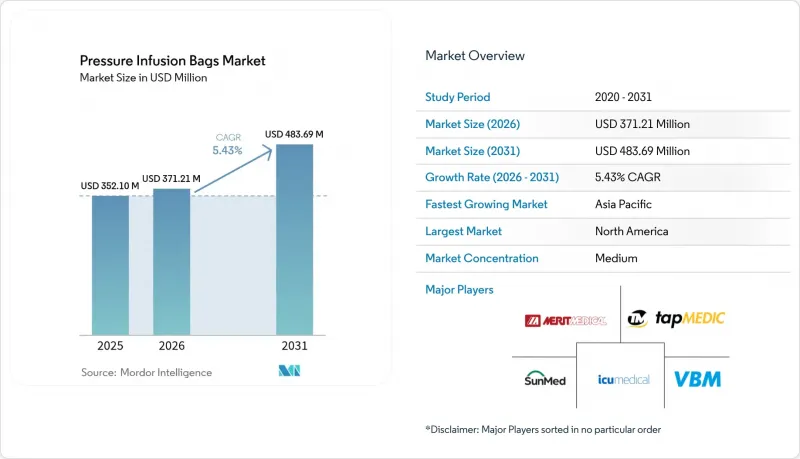
에 의하면, 2026년 압력 주입 백 시장 규모는 3억 7,121만 달러로 추정되고 있어 2025년 3억 5,210만 달러에서 확대해, 2031년에는 4억 8,369만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.43%로 성장할 것으로 전망됩니다.
본 보고서는 제품 유형(재사용형, 일회용), 소재(나일론, 폴리우레탄, 기타 소재), 압력 범위(250-300 mmHg, 기타), 용도(혈액 및 약물 주입, 침습적 압력 모니터링, 기타), 최종 사용자(병원 및 진료소, 기타),지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 압력 주입 백 시장 동향 및 인사이트
만성 질환 및 외상 사례 증가
외상 센터에서는 신속하고 대량의 수액 주입이 필요한 복잡한 다발성 외상 사례가 증가하고 있어, 신뢰성이 높은 가압식 투여 시스템이 요구되고 있습니다. 전투 부상자 치료에서도 이러한 필요성은 두드러집니다. 미국 국방부의 ‘골든 아워(Golden Hour)’ 이니셔티브에서는 가혹한 환경에서도 2일간 연속 작동이 가능한 가압 보조 장치가 중시되고 있습니다. 『2024년 전술적 전투 부상자 구호 지침』에서는 출혈성 쇼크에 대해 휴대용 가압 시스템을 활용한 조기 정맥 내 또는 골내 접근이 권장되고 있습니다. 이와 더불어 인구 동향의 변화, 고령화, 도시 지역 이동에 따른 부상 증가로 인해 전 세계 민간 응급 의료 부문에서 이 제품의 소비량이 확대되고 있습니다.
수술실(OR) 및 응급실(ED)에서의 일회용 가압 백의 급속한 보급
재사용 가능한 커프의 부적절한 재처리로 인한 집단 감염이 발생한 것을 계기로, 병원 감염 관리 위원회에서는 일회용 백을 폭넓게 지지하게 되었습니다. B. Braun사의 DUPLEX 플랫폼은 투약 오류 발생률을 54% 감소시켰으며, 1회당 투약 준비 주기를 약 4분 단축했습니다. 이러한 이점은 대량 사상자 사태에서 더욱 두드러집니다. 인력 부족으로 재처리 비용이 상승하는 가운데, 일회용 제품은 매력적인 총비용 구조를 제공하며, 과거에는 미미한 가격 프리미엄으로 여겨졌던 것이 이제는 운영 비용 절감으로 이어지고 있습니다.
저소득 지역의 숙련된 수액 요법사 부족
네팔의 간호 학교에서는 지도 체계의 약화가 보고되고 있으며, 졸업생들은 복잡한 수액 요법 프로토콜에 대응할 준비가 되어 있지 않습니다. 이러한 경향은 자원이 부족한 의료 시스템을 가진 여러 국가에서도 반복되고 있습니다. 전 세계적으로 조영제 알레르기 관리에 관한 공식 교육을 받은 의료진은 고작 31.1%에 불과하여, 첨단 의료기기 사용을 제한하는 기술 격차가 두드러지게 나타나고 있습니다.
부문 분석
일회용 주입백은 2025년 매출의 69.22%를 차지하며, 압력 주입 백 시장에서 감염 관리의 우선순위를 뒷받침하고 있습니다. 이 점유율은 병원 내 감염에 따른 법적 책임 증가와 보험사로부터의 제재를 반영한 것입니다. 이러한 추세에 따라 일회용 압력 주입 백 시장 규모는 2031년까지 연평균 성장률(CAGR) 6.08%로 확대될 것으로 예상되며, 비용에 민감한 지역에서도 재사용 가능한 커프를 대체할 전망입니다.
현재 병원에서는 멸균 담당 직원의 노동력, 오토클레이브 유지보수, 소송에 따른 숨겨진 비용을 일회용 백의 명확한 경제성과 비교하여 평가했습니다. 다수 사상자 대응 훈련에서 응급실 측에 따르면, 외상용 카트에 일회용 백이 미리 장착되어 있을 경우 환자 수용 및 이송 주기가 20% 단축되었다고 보고되었습니다. 그 결과, 각 제조업체는 품질 보증을 유지하면서 단위 비용의 차이를 줄이기 위해 생산 자동화를 추진하고 있습니다.
나일론은 확립된 생체 적합성과 뛰어난 비용 대비 성능 덕분에 2025년에는 매출의 43.85%를 차지했습니다. 그러나 임상 환경에서 DEHP 함유 PVC의 단계적 폐지를 요구하는 EU 지침을 배경으로, PVC가 포함되지 않은 바이오폴리머는 연평균 성장률(CAGR) 6.97%로 성장을 지속하고, 있습니다. 이러한 추세에 힘입어 PVC가 포함되지 않은 제품은 압력 주입 백 시장에서 가장 빠르게 성장하는 부문이 되었습니다.
대학병원 지속가능성 담당 팀은 수명 주기 전반에 걸친 이산화탄소 배출량 감축 및 소각 시 배출량 저감을 이유로, 입찰 시 바이오폴리우레탄제 백을 지정하는 사례가 늘고 있습니다. 공급업체들은 가격 변동이 심한 나일론 원료에서 벗어나기 위해 원료 다각화를 추진하고 있습니다. 이를 통해 지정학적 리스크를 헤지하고 비용 구조를 안정시키는 동시에, 친환경 제품 인증을 추진하고 있습니다.
지역별 분석
북미는 관대한 보험 환급 제도, 견조한 군 의료 예산, 그리고 스마트 수액 기술의 급속한 보급에 힘입어 2025년 매출의 37.10%를 차지했습니다. 미국의 구매자들은 중환자실(ICU) 입원 기간 단축을 장려하는 일괄 지급 인센티브의 혜택을 받고 있으며, 이를 통해 수액 관련 합병증을 완화하는 의료기기에 대한 투자가 촉진되고 있습니다. 캐나다의 국가 조달 이니셔티브 역시 연방 정부의 환경 목표에 부합하여 일회용 PVC 프리 대체품으로 전환되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR)이 5.89%로, 각 지역 중 가장 높은 성장률을 기록하고 있습니다. 이는 중국과 인도의 병원 건설 프로그램, 그리고 인도네시아, 베트남, 필리핀에서의 수술 건수 증가에 힘입은 결과입니다. 중국의 여러 제조업체가 클래스 III 의료기기 인증을 획득했으며, 연구개발(R&D)상의 제약이 있음에도 불구하고 국내 경쟁을 심화시키고 수출 확대에 대한 의지를 북돋우고 있습니다. 각 지역의 규제 당국은 아세안(ASEAN) 의료기기 지침에 따라 협력하여 시장 진입을 원활하게 하고 있지만, 보상 모델이 지역마다 다르기 때문에 여전히 지역에 맞춘 시장 진출 전략이 요구되고 있습니다.
유럽은 압력 주입 백 시장에서 큰 점유율을 차지하고 있으며, 지속가능성과 품질에 관한 지침이 조달 기준을 형성하고 있습니다. 독일의 DRG(진단 관련 그룹)에 기반한 병원 재정 제도는 수술 후 회복 기간을 단축하는 고품질 제품의 구매를 촉진하고 있습니다. 프랑스의 에코디자인령은 생체고분자 백의 채택을 가속화하고 있는 반면, 영국의 병원들은 브렉시트 이후에도 계속해서 EU 기술 문서를 준수하고 있습니다. 중동에서는 특히 UAE와 사우디아라비아에서 최첨단 외상 센터에 대한 자금 지원이 이루어지고 있습니다. 한편, 남아프리카공화국에서는 지역별 유통 체계가 정비되어, 기존 의약품 유통 채널을 통해 인접 국가들에 압력 주입 키트를 공급하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, pressure infusion bags market size in 2026 is estimated at USD 371.21 million, growing from 2025 value of USD 352.10 million with 2031 projections showing USD 483.69 million, growing at 5.43% CAGR over 2026-2031.
This report is Segmented by Product Type (Reusable, Disposable), Material (Nylon, Polyurethane, Other Materials), Pressure Range (250-300 MmHg, and More), Application (Blood and Drug Infusion, Invasive Pressure Monitoring, and More), End User (Hospitals and Clinics, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Pressure Infusion Bags Market Trends and Insights
Rising Prevalence of Chronic Diseases & Trauma Cases
Trauma centers increasingly report complex polytrauma presentations requiring rapid, high-volume infusions that favor reliable pressurized delivery systems. Combat casualty care underscores this need: the U.S. Department of Defense's Golden Hour initiatives highlight pressure-assisted devices capable of continuous operation for two days in austere environments. Tactical Combat Casualty Care Guidelines 2024 recommend early intravenous or intraosseous access supported by portable pressure systems for hemorrhagic shock. Parallel demographic shifts, aging populations, and urban mobility-related injuries are boosting unit consumption in civilian emergency departments worldwide.
Rapid Adoption of Disposable Pressure Bags in OR & ED
Hospital infection-control committees widely favor single-use bags after outbreaks linked to inadequately reprocessed reusable cuffs. B. Braun's DUPLEX platform demonstrated a 54% reduction in medication-error incidence and shaved nearly four minutes off each dose preparation cycle, a benefit amplified during mass-casualty events. As labor shortages inflate reprocessing costs, disposables offer an attractive total-cost profile, turning once-marginal price premiums into operational savings.
Shortage of Skilled Infusion Therapists in Low-Income Regions
Nepal's nursing schools report diminished supervision, leaving graduates unprepared for complex infusion protocols, a pattern repeated across several low-resource health systems. Only 31.1% of global practitioners receive formal training on contrast-media allergy management, underscoring a skills gap that limits sophisticated device use.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Ambulatory/Field-Care & Military Medicine
- Technological Shift to Integrated Pressure-Monitoring Valves
- Stringent ISO 8536-8 Particulate / Pressure Compliance Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Disposable bags captured 69.22% of 2025 revenue, anchoring the pressure infusion bags market's infection-control priority. This share reflects rising legal liability from hospital-acquired infections alongside payor penalties. Under these dynamics, the pressure infusion bags market size for disposables is projected to grow at 6.08% CAGR through 2031, replacing reusable cuffs even in cost-sensitive regions.
Hospitals now measure the hidden costs of sterilization staff time, autoclave maintenance, and litigation against the straightforward economics of one-time-use bags. During multi-casualty drills, emergency departments reported 20% faster turnover when disposables were pre-assembled on trauma carts. Manufacturers are consequently automating production to narrow unit-cost differentials while maintaining quality assurance.
Nylon held 43.85% revenue in 2025 due to its established biocompatibility and favorable price-performance ratio. Yet PVC-free biopolymers post a 6.97% CAGR, powered by EU directives phasing out DEHP-containing PVC in clinical environments. This momentum positions PVC-free variants as the fastest-growing slice of the pressure infusion bags market.
Sustainability teams at university hospitals increasingly specify bio-polyurethane bags in tenders, citing lifecycle-carbon savings and lower incineration emissions. Suppliers are diversifying feedstocks away from volatile nylon streams, hedging geopolitical risk and stabilizing cost structures while promoting green-label credentials.
Complete Report Scope:
- By Product Type
- Reusable
- Disposable
- By Material
- Nylon
- Polyurethane
- Silicone-coated Composites
- PVC-free Biopolymers
- By Pressure Range
- 250-300 mmHg
- 301-400 mmHg
- More than 400 mmHg
- By Application
- Blood & Drug Infusion
- Invasive Pressure Monitoring
- Rapid Fluid Resuscitation
- Contrast-Media Injection
- By End User
- Hospitals & Clinics
- Ambulatory Surgical & Outpatient Centers
- Home Care & Long Term Care
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 37.10% of 2025 revenue, underpinned by premium reimbursement structures, strong military medical budgets, and rapid adoption of smart infusion technologies. U.S. buyers benefit from bundled payment incentives that reward shorter ICU stays, encouraging investment in devices that reduce infusion-related complications. Canada's national procurement initiatives are likewise pivoting toward disposable, PVC-free alternatives, aligning with federal environmental targets.
Asia-Pacific logs the fastest regional CAGR at 5.89% through 2031, propelled by hospital-build programs in China and India and by rising surgical volumes in Indonesia, Vietnam, and the Philippines. Multiple Chinese manufacturers have advanced to Class III device certification, enhancing domestic competition and driving export ambitions despite R&D constraints. Regional regulators coordinate under ASEAN Medical Device Directives to ease market entry, although varied reimbursement models still require localized go-to-market strategies.
Europe commands a substantial slice of the pressure infusion bags market, with sustainability and quality directives shaping procurement standards. Germany's DRG-based hospital financing supports premium purchases that shorten postoperative recovery. France's eco-design decree accelerates adoption of bio-polymeric bags, while UK hospitals continue to align with EU technical files post-Brexit. The Middle East funds state-of-the-art trauma centers, notably in the UAE and Saudi Arabia, whereas South Africa consolidates regional distribution, supplying neighboring states with pressure infusion kits through existing pharmaceutical channels.
- Merit Medical Systems
- ICU Medical
- VBM Medizintechnik
- Biegler
- SunMed
- Tapmedic
- Armstrong Medical (Eakin Healthcare)
- Sarstedt
- Fairmont Medical
- Spengler
- Ecomed
- Baxter
- B. Braun
- Fresenius
- Smiths Group
- Terumo Corp.
- Medline Industries
- 3M Health Care
- Codan US Corp.
- Vogt Medical Vertrieb
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence of Chronic Diseases & Trauma Cases
- 4.2.2 Rapid Adoption of Disposable Pressure Bags in OR & ED
- 4.2.3 Expansion of Ambulatory/Field-Care & Military Medicine
- 4.2.4 Technological Shift to Integrated Pressure-Monitoring Valves
- 4.2.5 Sustainability Push for PVC-Free, Recyclable Bag Materials
- 4.2.6 AI-Assisted Closed-Loop Infusion Systems Enable Higher Bag Throughput
- 4.3 Market Restraints
- 4.3.1 Shortage of Skilled Infusion Therapists in Low-Income Regions
- 4.3.2 Stringent Iso 8536-8 Particulate/Pressure Compliance Costs
- 4.3.3 Volatility in Medical-Grade Nylon & PU Resin Supply Chains
- 4.3.4 Competition from Elastomeric & Needle-Free Pressure Devices
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Product Type
- 5.1.1 Reusable
- 5.1.2 Disposable
- 5.2 By Material
- 5.2.1 Nylon
- 5.2.2 Polyurethane
- 5.2.3 Silicone-coated Composites
- 5.2.4 PVC-free Biopolymers
- 5.3 By Pressure Range
- 5.3.1 250-300 mmHg
- 5.3.2 301-400 mmHg
- 5.3.3 More than 400 mmHg
- 5.4 By Application
- 5.4.1 Blood & Drug Infusion
- 5.4.2 Invasive Pressure Monitoring
- 5.4.3 Rapid Fluid Resuscitation
- 5.4.4 Contrast-Media Injection
- 5.5 By End User
- 5.5.1 Hospitals & Clinics
- 5.5.2 Ambulatory Surgical & Outpatient Centers
- 5.5.3 Home Care & Long Term Care
- 5.5.4 Other End Users
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Merit Medical Systems
- 6.3.2 ICU Medical Inc.
- 6.3.3 VBM Medizintechnik GmbH
- 6.3.4 Biegler GmbH
- 6.3.5 SunMed
- 6.3.6 Tapmedic LLC
- 6.3.7 Armstrong Medical (Eakin Healthcare)
- 6.3.8 Sarstedt AG & Co. KG
- 6.3.9 Fairmont Medical
- 6.3.10 Spengler SAS
- 6.3.11 Ecomed
- 6.3.12 Baxter International
- 6.3.13 B. Braun Melsungen AG
- 6.3.14 Fresenius Kabi
- 6.3.15 Smiths Medical
- 6.3.16 Terumo Corp.
- 6.3.17 Medline Industries
- 6.3.18 3M Health Care
- 6.3.19 Codan US Corp.
- 6.3.20 Vogt Medical Vertrieb
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


