|
시장보고서
상품코드
2116450
이식편대숙주질환(GVHD) 치료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Graft Versus Host Disease Treatment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
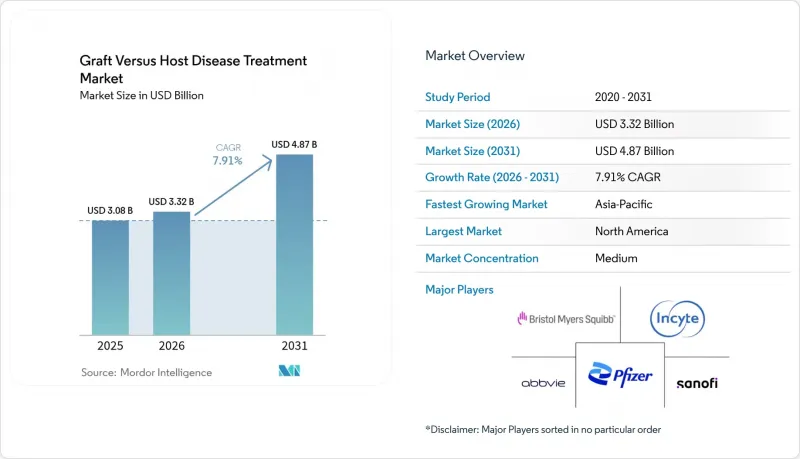
에 의하면, 2026년 이식편대숙주질환(GVHD) 치료 시장 규모는 33억 2,000만 달러로 추정되고 2025년 30억 8,000만 달러에서 확대해, 2031년에는 48억 7,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 7.91%를 나타낼 것으로 전망됩니다.
본 보고서는 질환별(급성 GVHD 등), 제품 카테고리별(코르티코스테로이드 등), 치료 방식별(저분자 의약품 등), 치료 라인별(1차 선택 등),투여 경로별(경구 등), 최종 사용자별(병원 약국 등), 환자 연령대별(소아 등), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 이식편대숙주질환(GVHD) 치료 시장 동향 및 인사이트
적응증 범위 확대가 동종 조혈모세포이식(HSCT) 시행 건수를 끌어올렸으며
CMS는 2024년 3월, 골수이형성증후군에 대한 동종 조혈모세포 이식(HSCT)의 메디케어 적용 범위를 확대하여 고령 환자나 동반 질환이 있는 환자에 대한 이식을 허용했습니다. 이에 따라 GVHD가 발병할 가능성이 있는 환자층이 직접적으로 확대되었습니다. 현재 병원에서는 이전에는 적격으로 간주되지 않았던 후보자들도 치료 대상으로 포함하고 있으며, 비골수 파괴 요법에 의한 혼합 키메라 상태에 대한 데이터도 이러한 종합적인 접근 방식을 뒷받침하고 있습니다. 시술 건수 증가는 예방 요법의 사용 증가 및 반복 치료의 필요성으로 이어져, 이식편대숙주질환(GVHD) 치료 시장의 성장세를 유지하고 있습니다.
FDA 승인의 물결
소아의 스테로이드 저항성 급성 GVHD에 대한 레메스템셀-L, 만성 GVHD에 대한 악사틸리맙의 FDA 승인은 새로운 치료 접근법과 높은 가격 책정 기회를 제공합니다. 각 승인은 유사한 작용기전을 가진 치료법에 대한 투자를 촉진하고 임상시험 피험자 모집을 가속화할 뿐만 아니라, 미충족 의료 수요에 대응하려는 규제 당국의 노력을 강조하는 것입니다. 이러한 자산의 신속한 상용화는 경쟁을 심화시키고 이식편대숙주질환(GVHD) 치료 시장의 제품 라인업을 강화할 것입니다.
바이오의약품 및 세포 치료제의 높은 비용
레메스템셀-L 및 악사티리맙의 정가는 특히 의료 기술 평가 체계에서 비용 대비 효과가 중시되는 경우, 지불 주체의 예산을 압박합니다. 신흥 시장에서는 특히 큰 장벽에 직면해 있어, 명확한 임상적 이점이 있음에도 불구하고 도입이 지연되고 있습니다. 사전 승인 규정이나 단계적 치료 프로토콜로 인해 임상의들이 차세대 약물의 도입을 주저하는 경우가 있으며, 이는 단기적으로 성장 가능성을 억제하는 요인이 되고 있습니다.
부문별 분석
급성 GVHD는 2025년 이식편대숙주질환(GVHD) 치료 시장 점유율의 61.12%를 차지했으며, 이식 후 초기 염증의 임상적 발생 빈도가 여전히 높음을 반영합니다. 한편, 만성 GVHD는 2031년까지 연평균 성장률(CAGR) 11.17%로 성장할 전망이며, 질환 부문 중 가장 높은 성장률을 보이고 있습니다. 이러한 성장 가속화는 이식 후 생존 기간의 연장으로 인해 만성기 환자 수가 증가하고 있는 점, 섬유화, B세포 활성화, 혹은 ROCK2 신호 전달을 특이적으로 표적으로 하는 JAK 억제제나 단일클론 항체와 같은 새로운 치료 옵션이 등장하고 있는 데 기인합니다. 베드리즈마브를 이용한 하부 소화관 예방 요법을 통해 180일 생존율은 이미 85.5%에 달했으며, 이로 인해 급성 사건은 감소하는 한편, 만성 증상이 발현될 때까지 생존하는 환자 수가 증가하고 있습니다.
현재 다직종 협력 클리닉에서는 만성 GVHD를 전신성 자가면역 질환과 동일하게 치료하고 있으며, 표준적인 면역억제 요법에 더해 폐 재활, 안구 윤활제, 룩솔리티닙의 국소 투여가 이루어지고 있습니다. 중증 장 증례에서 테두글루티드의 64.7%라는 전체 반응률은 장기 특이적 생물학적 제제가 얼마나 완화율을 향상시킬 수 있는지를 여실히 보여주고 있습니다. 그 결과, 만성기 치료는 2031년까지 매년 이식편대숙주질환(GVHD) 치료 시장 내 점유율을 확대할 것으로 예상되며, 혁신적인 제약 기업들에게 지속적인 목표 시장을 창출하게 될 것입니다.
2025년, 코르티코스테로이드는 이식편대숙주질환(GVHD) 치료 시장에서 38.12%의 점유율을 차지했습니다. 이는 주로 지침 작성자들이 여전히 급성 발작에 대한 1차 치료법으로 메틸프레드니솔론을 권장하고 있기 때문입니다. 그러나 JAK 억제제는 연평균 성장률(CAGR) 12.44%로 성장하고 있으며, 이는 룩솔리티닙이 소아 환자에서 94.1%의 종합 유효율을 보였습니다는 점과 스테로이드 저항성 질환을 가진 성인 환자에서의 사용 경험이 증가하고 있다는 점이 뒷받침하고 있습니다. 현재 저용량 메토트렉세이트는 스테로이드와 병용되어 1년 무재발 생존율을 스테로이드 단독 요법의 41%에 비해 69%까지 끌어올리고 있으며, 스테로이드의 유용성을 유지하는 점진적인 혁신이 두드러지고 있습니다.
JAK 억제제 외에도 악사틸리맙 등의 단일클론 항체가 만성 GVHD 시장에서 점유율을 확대하고 있으며, BTK 억제제는 암 치료 프로그램에서 전용되고 있습니다. 세포 및 유전자 치료는 현재로서는 시장 점유율이 아직 제한적이지만, 고가의 가격 책정에도 불구하고 장기적인 약물 요법을 대체할 가능성이 있는 지속적인 치료 효과를 가져옵니다. 이러한 동향들이 맞물려 이식편대숙주질환(GVHD) 치료 시장에서 스테로이드의 점유율을 서서히 잠식하면서 치료법의 다양성을 확대해 나갈 것으로 예측됩니다.
저분자 의약품(코르티코스테로이드, JAK 억제제, 칼시뉴린 비의존성 약물)은 2025년 이식편대숙주질환(GVHD) 치료 시장 규모의 43.98%를 차지했습니다. 세포 및 유전자 치료는 소아 급성 GVHD에 대한 레메스템셀-L의 FDA 승인 및 타베크렐셀 등의 후기 임상 개발 프로그램에 힘입어 연평균 성장률(CAGR) 11.66%로 가장 빠르게 성장하고 있습니다. 생물학적 제제는 여전히 안정적인 중견 위치를 유지하고 있으며, CSF-1R, CD38, α4B7 인테그린에 대한 항체 제제는 적응증을 서서히 확대되고 있습니다.
폐쇄형 바이오리액터 및 사내 플라스미드 제조 설비의 가동에 따라, 중간엽 줄기세포 및 바이러스 벡터 제조의 격차는 줄어들고 있으며, 각 후원사는 상업적 수요에 부응할 수 있게 되었습니다. 또한, 플랫폼의 발전으로 인해 환자별로 필요한 리드타임을 피할 수 있는 동종 ‘오프-더-쉘프(off-the-shelf)’ 제품의 제공도 가능해졌습니다. 앞으로 치료법의 구성은 GVHD를 지속적이고 완치 가능성을 지닌 방식으로 제어할 수 있는 세포 기반 솔루션으로 계속 전환될 것이며, 이에 따라 이식편대숙주질환(GVHD) 치료 시장 내 세포 치료법의 점유율이 확대될 것으로 전망됩니다.
지역별 분석
북미는 신규 승인을 신속화하는 FDA의 환경과 고가 의약품에 대한 보험 급여에 적극적인 보험사의 태도에 힘입어 2025년 매출의 41.82%를 차지했습니다. 메디케어가 2024년에 이식 적응증을 확대 승인함에 따라 국내 환자층은 더욱 확대되고 있습니다. 미국의 이식 센터에서는 원격 의료를 통한 경과 관찰 및 재택 주입 서비스를 통합하고 있으며, 이를 통해 입원 기간을 단축하는 동시에 외래 환자의 경구제 복용을 지원하고 있습니다.
아시아태평양은 중국과 일본이 이식 역량을 확대하고 새로운 항바이러스 요법 및 이식편대숙주질환(GVHD) 치료법을 승인함에 따라, 세계 최고 수준인 연평균 성장률(CAGR) 10.54%를 나타낼 것으로 전망됩니다. 세포 처리 시설에 대한 민관 투자를 통해 수입 벡터에 대한 의존도가 낮아지고, 공급 안정성이 향상되고 있습니다. 혈액 악성 종양의 발생률 증가와 보험 제도의 확충이 맞물려, 이 지역은 세계 이식편대숙주질환(GVHD) 치료 시장 성장의 주요 견인차로서의 입지를 확고히 하고 있습니다.
유럽은 안정적인 상태를 유지하며 시장 침투율도 높은 수준을 이어가고 있으나, 엄격한 예산 관리로 인해 고가 치료법의 도입은 억제되고 있습니다. 공동 임상시험 네트워크를 통해 근거 창출은 가속화되고 있으나, 보험사의 철저한 심사로 인해 최첨단 제품의 보험 적용은 지연되고 있습니다. 남미, 중동 및 아프리카는 여전히 시장이 형성되기 시작한 단계이며, 이들 지역의 이식편대숙주질환(GVHD) 치료 시장의 장기적인 잠재력을 끌어내기 위해서는 기술 이전 계약 및 기증자 등록 기관과의 협력이 필수적입니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, GVHD treatment market size in 2026 is estimated at USD 3.32 billion, growing from 2025 value of USD 3.08 billion with 2031 projections showing USD 4.87 billion, growing at 7.91% CAGR over 2026-2031.
This report is Segmented by Disease (Acute GVHD and More), Product Category (Corticosteroids and More), Therapeutic Modality (Small-Molecule Drugs, and More), Treatment Line (First-Line, and More), Route of Administration (Oral and More), End User (Hospital Pharmacies and More), Patient Age Group (Paediatric and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Graft Versus Host Disease Treatment Market Trends and Insights
Broader Eligibility Driving Allogeneic HSCT Volumes
CMS expanded Medicare coverage for allogeneic HSCT in myelodysplastic syndrome during March 2024, permitting transplants in older or comorbid patients and directly enlarging the pool that may experience GVHD. Hospitals now treat candidates once deemed ineligible, and mixed-chimerism data from non-myeloablative regimens reinforce this inclusive approach. Growing procedure counts translate into higher prophylaxis usage and recurring therapy needs, sustaining GVHD treatment market momentum.
Wave of FDA Approvals
FDA endorsements for remestemcel-L in pediatric steroid-refractory acute GVHD and axatilimab in chronic GVHD provide new therapeutic angles and premium pricing opportunities. Each approval encourages investment in analogous mechanisms, accelerates trial enrollment, and underscores regulatory commitment to address unmet need. Rapid commercialization of these assets heightens competition and enriches the product mix within the GVHD treatment market.
High Cost of Biologics & Cell Therapies
Remestemcel-L and axatilimab list prices strain payer budgets, especially where health-technology-assessment frameworks emphasize cost-effectiveness. Emerging markets face particular hurdles, delaying uptake despite clear clinical benefit. Prior authorization rules and step-therapy protocols sometimes deter clinicians from adopting next-generation agents, tempering growth potential in the near term.
Other drivers and restraints analyzed in the detailed report include:
- Expanding Pipeline of Biologics & Cell Therapies
- Growing Incidence of Hematologic Malignancies
- Infection Risk from Profound Immunosuppression
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acute GVHD retained 61.12% of 2025 GVHD treatment market share, reflecting the still-greater clinical frequency of early post-transplant inflammation. Chronic GVHD, however, is on track for an 11.17% CAGR to 2031, the fastest among disease segments. This acceleration stems from longer post-transplant survival that enlarges the chronic-phase patient pool and from fresh options such as JAK inhibitors and monoclonal antibodies that specifically target fibrosis, B-cell activation, or ROCK2 signaling. Lower-GI prophylaxis with vedolizumab has already lifted day-180 survival to 85.5%, which decreases acute events yet leaves more patients alive to develop chronic manifestations.
Multidisciplinary clinics are now treating chronic GVHD more like systemic autoimmune disease, adding pulmonary rehab, ocular lubricants, and topical ruxolitinib to standard immunosuppression. Teduglutide's 64.7% overall response in severe intestinal cases underlines how organ-directed biologics can lift remission rates. As a result, chronic therapies are expected to raise their portion of GVHD treatment market size each year through 2031, creating a sustained addressable base for innovators.
Corticosteroids commanded 38.12% GVHD treatment market share in 2025, largely because guideline writers still endorse methylprednisolone as first-line therapy for acute episodes. Yet JAK inhibitors are expanding at a 12.44% CAGR, buoyed by ruxolitinib's 94.1% overall effectiveness in children and by growing adult experience in steroid-refractory disease. Mini-dose methotrexate now combines with steroids to push 1-year failure-free survival to 69% versus 41% for steroids alone, highlighting incremental innovations that maintain steroid relevance.
Beyond JAK blockade, monoclonal antibodies such as axatilimab are taking share in chronic GVHD, and BTK inhibitors are being repurposed from oncology programs. Cell and gene therapies, while still holding a modest slice today, carry premium pricing and deliver durable responses that can displace prolonged drug courses. Collectively, these dynamics are expected to chip away at the steroid portion of GVHD treatment market size while broadening therapeutic diversity.
Small-molecule drugs-corticosteroids, JAK inhibitors, calcineurin-sparing agents-held 43.98% of 2025 GVHD treatment market size. Cell and gene therapies are the fastest movers at an 11.66% CAGR, lifted by FDA endorsement of remestemcel-L for pediatric acute GVHD and late-stage programs such as tabelecleucel. Biologics remain a steady middle ground, with antibodies against CSF-1R, CD38, and a4B7 integrin incrementally widening indications.
The manufacturing gap for mesenchymal stem cells and viral vectors is narrowing as closed-system bioreactors and in-house plasmid suites come online, letting sponsors meet commercial demand. Platform advances also allow allogeneic "off-the-shelf" products that avoid patient-specific lead times. Looking ahead, the modality mix will keep shifting toward cell-based solutions that promise sustained, possibly curative, control of GVHD and thereby lift cell therapy share of GVHD treatment market size.
Complete Report Scope:
- By Disease
- Acute GVHD
- Chronic GVHD
- By Product Category
- Corticosteroids
- Monoclonal Antibodies
- JAK Inhibitors
- BTK Inhibitors
- Tyrosine Kinase Inhibitors (non-JAK/BTK)
- mTOR Inhibitors
- Cell & Gene Therapies
- Other Products
- By Therapeutic Modality
- Small-Molecule Drugs
- Biologics
- Cell & Gene Therapies
- By Treatment Line
- First-Line (Steroid Sensitive)
- Second-Line (Steroid-Refractory)
- Late-Line / Salvage
- By Route of Administration
- Oral
- Intravenous
- Sub-cutaneous
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- By Patient Age Group
- Paediatric
- Adult
- Geriatric
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 41.82% of 2025 revenue, buoyed by an FDA environment that expedites novel approvals and by insurer willingness to reimburse high-cost agents. Medicare's 2024 decision to fund broader transplant indications further enlarges domestic patient pools. Transplant centers in the United States integrate telehealth follow-up and home-infusion services, limiting inpatient stays and supporting outpatient adoption of oral agents.
Asia-Pacific is projecting a 10.54% CAGR, the fastest worldwide, as China and Japan expand transplant capacity and approve new anti-viral and GVHD therapies. Public-private investment in cell-processing facilities reduces reliance on imported vectors, improving supply security. Rising incidence of hematologic malignancies, coupled with broader insurance schemes, positions the region as a prime contributor to global GVHD treatment market growth.
Europe remains stable and well-penetrated, but tight budget controls moderate uptake of premium therapies. Collaborative trial networks hasten evidence generation, yet payer scrutiny delays reimbursement for frontier products. South America, the Middle East, and Africa remain nascent; technology-transfer deals and donor-registry collaborations are necessary to unlock their long-term GVHD treatment market potential.
- Incyte
- Bristol-Myers Squibb
- Sanofi
- Abbvie
- Pfizer
- Novartis
- Astellas Pharma
- Roche
- Takeda Pharmaceuticals
- Merck
- Gamida Cell Ltd.
- Gilead
- Bluebird bio Inc.
- Atara Biotherapeutics Inc.
- Mesoblast Limited
- Omeros Corporation
- Amgen
- Eli Lilly and Company
- CSL Behring
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Broader Eligibility Driving Allogeneic HSCT Volumes
- 4.2.2 Wave Of FDA Approvals
- 4.2.3 Expanding Pipeline Of Biologics & Cell Therapies
- 4.2.4 Growing Incidence Of Hematologic Malignancies
- 4.2.5 Microbiome-Modulation Therapeutics Opening New Niches
- 4.2.6 Post-Transplant Cyclophosphamide Enabling Haplo-Identical HSCT
- 4.3 Market Restraints
- 4.3.1 High Cost Of Biologics & Cell Therapies
- 4.3.2 Infection Risk From Profound Immunosuppression
- 4.3.3 Supply Constraints For MSC & Viral-Vector Manufacturing
- 4.3.4 Reimbursement Gaps For Off-Label Regimens In EMS
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Disease
- 5.1.1 Acute GVHD
- 5.1.2 Chronic GVHD
- 5.2 By Product Category
- 5.2.1 Corticosteroids
- 5.2.2 Monoclonal Antibodies
- 5.2.3 JAK Inhibitors
- 5.2.4 BTK Inhibitors
- 5.2.5 Tyrosine Kinase Inhibitors (non-JAK/BTK)
- 5.2.6 mTOR Inhibitors
- 5.2.7 Cell & Gene Therapies
- 5.2.8 Other Products
- 5.3 By Therapeutic Modality
- 5.3.1 Small-Molecule Drugs
- 5.3.2 Biologics
- 5.3.3 Cell & Gene Therapies
- 5.4 By Treatment Line
- 5.4.1 First-Line (Steroid Sensitive)
- 5.4.2 Second-Line (Steroid-Refractory)
- 5.4.3 Late-Line / Salvage
- 5.5 By Route of Administration
- 5.5.1 Oral
- 5.5.2 Intravenous
- 5.5.3 Sub-cutaneous
- 5.6 By Distribution Channel
- 5.6.1 Hospital Pharmacies
- 5.6.2 Retail Pharmacies
- 5.6.3 Online Pharmacies
- 5.7 By Patient Age Group
- 5.7.1 Paediatric
- 5.7.2 Adult
- 5.7.3 Geriatric
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 Europe
- 5.8.2.1 Germany
- 5.8.2.2 United Kingdom
- 5.8.2.3 France
- 5.8.2.4 Italy
- 5.8.2.5 Spain
- 5.8.2.6 Rest of Europe
- 5.8.3 Asia-Pacific
- 5.8.3.1 China
- 5.8.3.2 Japan
- 5.8.3.3 India
- 5.8.3.4 Australia
- 5.8.3.5 South Korea
- 5.8.3.6 Rest of Asia-Pacific
- 5.8.4 Middle East and Africa
- 5.8.4.1 GCC
- 5.8.4.2 South Africa
- 5.8.4.3 Rest of Middle East and Africa
- 5.8.5 South America
- 5.8.5.1 Brazil
- 5.8.5.2 Argentina
- 5.8.5.3 Rest of South America
- 5.8.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Incyte Corporation
- 6.3.2 Bristol Myers Squibb Company
- 6.3.3 Sanofi SA
- 6.3.4 AbbVie Inc.
- 6.3.5 Pfizer Inc.
- 6.3.6 Novartis AG
- 6.3.7 Astellas Pharma Inc.
- 6.3.8 F. Hoffmann-La Roche Ltd.
- 6.3.9 Takeda Pharmaceutical Co. Ltd.
- 6.3.10 Merck & Co., Inc.
- 6.3.11 Gamida Cell Ltd.
- 6.3.12 Gilead
- 6.3.13 Bluebird bio Inc.
- 6.3.14 Atara Biotherapeutics Inc.
- 6.3.15 Mesoblast Limited
- 6.3.16 Omeros Corporation
- 6.3.17 Amgen Inc.
- 6.3.18 Eli Lilly and Company
- 6.3.19 CSL Behring
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment