

|
시장보고서
상품코드
2116507
부인과 검진 의자 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Gynecological Examination Chairs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
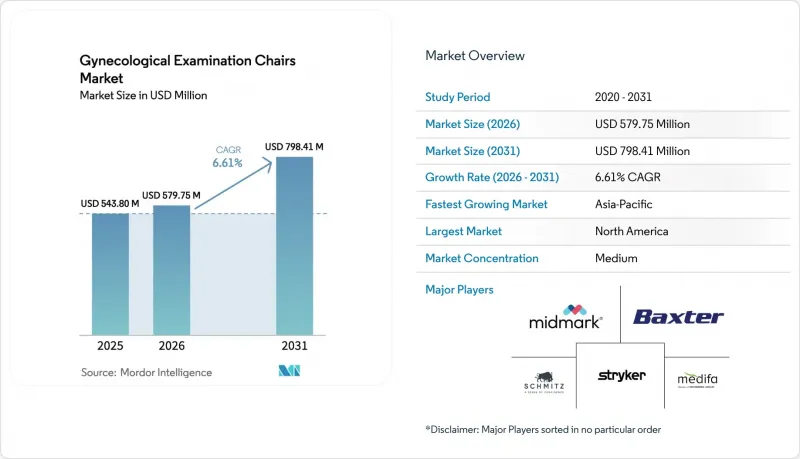
에 의하면, 부인과 검진 의자 시장 규모는 2025년에 5억 4,380만 달러로 평가되었습니다. 2026년 5억 7,975만 달러에서 2031년까지 7억 9,841만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.61%를 나타낼 전망입니다.
본 보고서는 제품 유형(비전동식 수동형 등), 최종 사용자(병원, 민간 클리닉, 진단센터, 외래수술센터(ASC), 소매 미니 클리닉), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 부인과 검진 의자 시장 동향 및 인사이트
여성 건강 문제로 인한 부담 증가
2021년 Global Burden of Disease의 최신 보고서에 따르면, 생식기 질환 유병자 수는 12억 1,000만 명에 달했으며, 인도, 중국, 인도네시아 등 주요 시장에서 선별 검진 프로그램이 확대됨에 따라 이 수치는 계속 증가하고 있습니다. 이러한 진단 범위의 확대로 인해 환자의 재방문율이 높아지고 있으며, 진료소에서는 구형 고정 높이 테이블에서 첨단 다중 위치 조절이 가능한 전동 의자로의 교체가 진행되고 있습니다. 이러한 진찰대는 공간을 최적화하도록 설계되어 골반 검사, 질 확대경 검사, 산전 검진 등 다양한 기능을 지원합니다. 또한, 자궁경부암에 대한 보편적 선별검사를 의무화하는 각국의 정책에 따라 영상 진단용 마운트 및 ADA(미국 장애인법) 기준을 준수하는 이동식 면을 갖춘 진찰대에 대한 수요가 증가하고 있으며, 이는 진화하는 규제 및 운영 요건에도 부합합니다.
전 세계 의료 인프라의 확대
아시아태평양의 의료 지출은 2030년까지 5조 달러에 달할 것으로 예측됩니다. 그 배경에는 인도의 ‘아유슈만 바라트’ 보험 프로그램, 중국의 제14차 5개년 계획에 포함된 ‘여성 및 소아를 위한 현립 병원 1,000곳 설립’ 공약, 그리고 인도네시아의 진료소 네트워크 확대를 목적으로 한 다자간 자금 지원과 같은 주요 이니셔티브가 있습니다. WHO의 최신 인체공학 및 감염 관리 기준을 준수하는 신규 시설 건설에 따라, 기존의 저비용 수동식 수술대보다 첨단 전동식 또는 전기유압식 수술대가 선호되는 경향이 강해지면서 의료기기 도입에 큰 변화가 일어나고 있습니다.
막대한 설비 투자가 필요
전동식 부인과 검진 의자의 가격은 2,950-7,500달러인 반면, 수동식 모델은 1,050-2,400달러로, 이 2-3배에 달하는 가격 차이는 ASC(외래수술센터(ASC))나 지방 진료소의 예산을 압박하고 있습니다. 게다가 설치 비용으로 10-15%, 부속품 비용으로 500-1,100달러가 추가되므로 총 지출액은 막대한 규모가 됩니다. 10개 실 규모의 산부인과 센터의 경우, 진찰대만으로도 5만-7만 5,000달러가 소요될 수 있습니다. 리퍼브 제품이나 구독형 제품은 진입 장벽을 낮추지만, 보증 및 잔존 가치에 대한 우려로 인해 도입률은 여전히 낮은 수준을 유지하고 있습니다.
부문별 분석
2025년, 전동식 유닛은 부인과 검진 의자 시장 점유율의 47.67%를 차지했으며 연평균 성장률(CAGR) 8.54%를 나타낼 것으로 예측됩니다. 이러한 성장은 환자의 설정 시간을 40% 가까이 단축하는 프로그래밍 가능한 메모리 프리셋 기능에 의해 주도되고 있습니다. 병원에서는 자산 관리 소프트웨어와 직접 연동되는 IoT 원격 측정 기능을 갖추고 있어 이러한 유닛을 점점 더 선호하는 추세입니다. 그 결과, 전동식 유닛은 고소득 지역에서 표준적인 선택지로 자리 잡고 있습니다. 비용 효율성을 중시하는 시장에서는 유압식이나 전기유압식 하이브리드가 여전히 주류를 이루고 있지만, 향후 시행될 접근성 규정을 준수하기 위해 전동식 높이 조절 기능에 대한 수요가 증가하고 있습니다. 스마트하고 완전히 연결된 진찰 의자의 출하 대수는 현재 5% 미만이지만, 북미의 시범 프로그램을 통해 가동 중단 시간을 3분의 1 가까이 줄일 수 있음이 입증되었습니다. 이에 따라 사이버 보안 체계가 성숙해짐에 따라 이 부문은 상당한 성장이 예상됩니다.
규제 및 지속가능성에 대한 압력 또한 전동 모델의 채택을 더욱 촉진하고 있습니다. 분리 가능한 부품을 에틸렌옥사이드 대신 과산화수소나 방사선을 사용하여 재처리함으로써, EPA의 멸균제 규정을 준수하는 절차가 간소화됩니다. 2024년에는 OEM 재처리 프로그램을 통해 500만 파운드의 장비가 회수되었으며, 고객의 비용 절감액은 2억 3,900만 달러에 달했습니다. 이러한 수명 주기 비용상의 이점은 가치 기반 조달 위원회의 우선순위와 부합합니다. 한편, 수동식 수술대는 ADA(미국 장애인법)의 높이 조정 기준을 충족하지 못하는 사례가 증가하고 있어, 향후에는 초저예산 용도나 인도적 지원 현장에만 국한될 것으로 예측됩니다.
지역별 분석
2025년에는 6,300곳이 넘는 외래수술센터(ASC), 지속적인 병원 설비 갱신 주기, 그리고 고정 높이 테이블 사용을 금지하는 접근성 규제의 시행에 힘입어 북미가 총 매출의 41.56%를 차지했습니다. 미국 내 소매 클리닉의 확장은 병원 이외의 새로운 구매자를 유치하고 있는 반면, 캐나다 각 주에서 시행하는 의무화 조치는 이중 언어 지원을 갖춘 ISO 인증 기기에 대한 수요를 촉진하고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로 자리매김하고 있으며, 2031년까지 연평균 성장률(CAGR)은 7.54%로 예측됩니다. 주요 촉진요인으로는 인도의 ‘아유슈만 바라트’ 이니셔티브, 중국이 계획 중인 1,000곳의 현급 여성·소아 병원 설립, 그리고 인도네시아에서 아시아 인프라 투자 은행(AIIB) 자금을 통한 진료소 현대화 등이 꼽힙니다. 이러한 움직임으로 인해 WHO의 인체공학 기준에 부합하는 전동식 및 하이브리드식 진료용 의자에 대한 큰 수요가 발생하고 있습니다. 현지 제조업체들은 2,000달러 미만의 경쟁력 있는 가격을 유지하고 있어, 이로 인해 2선 도시에서도 널리 보급되고 있습니다.
유럽에서는 단일 지불자 조달 시스템이 안정적인 판매량을 확보하고 있는 반면, 이익률에 압박을 가하고 있습니다. 조달 계약에 포함된 지속가능성 관련 조항으로 인해 순환형 경제 솔루션을 제공하는 공급업체가 점점 더 유리한 입장에 놓이고 있습니다. 중동 시장은 양극화되어 있으며, 고급스러운 걸프 지역 병원 체인과는 대조적으로 사하라 이남 지역에서는 기부금에 의한 사업이 주류를 이루고 있어, 주로 수동식 또는 비용 효율적인 하이브리드 솔루션이 조달되고 있습니다. 라틴아메리카에서는 환율 변동이 성장을 둔화시키고 있지만, 브라질과 아르헨티나에서는 각국의 여성 건강 프로그램에 부합하는 공공 입찰 활동이 계속해서 견조한 추세를 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.31According to Mordor Intelligence, the gynecological examination chairs market size was valued at USD 543.80 million in 2025 and is estimated to grow from USD 579.75 million in 2026 to reach USD 798.41 million by 2031, at a CAGR of 6.61% during the forecast period (2026-2031).
This report is Segmented by Product Type (Non-Electric Manual, and More), End User (Hospitals, Private Clinics, Diagnostic Centres, Ambulatory Surgical Centres, and Retail Minute Clinics), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, and South America). Market Forecasts are Provided in Terms of Value (USD).
Global Gynecological Examination Chairs Market Trends and Insights
Growing Burden of Women's Health Disorders
The 2021 Global Burden of Disease update reported 1.21 billion prevalent reproductive-system conditions, a figure that continues to rise as screening programs expand in key markets such as India, China, and Indonesia. This increasing diagnostic coverage is driving higher patient revisit rates and prompting clinics to replace outdated fixed-height tables with advanced multi-position electric chairs. These chairs, designed to optimize space, support multiple functions, including pelvic exams, colposcopy, and prenatal monitoring. Furthermore, national mandates for universal cervical-cancer screening are fueling demand for chairs equipped with imaging mounts and ADA-compliant transfer surfaces, aligning with evolving regulatory and operational requirements.
Expansion of Global Healthcare Infrastructure
Health-care expenditure in the Asia-Pacific region is projected to reach USD 5 trillion by 2030, fueled by key initiatives such as India's Ayushman Bharat insurance program, China's 14th Five-Year Plan commitment to establish 1,000 county-level hospitals for women and children, and multilateral funding aimed at expanding clinic networks in Indonesia. With new facilities adhering to modern WHO ergonomic and infection-control standards, there is a growing preference for advanced electric or electro-hydraulic chairs over traditional low-cost manual tables, driving a significant shift in medical equipment adoption.
High Capital Expenditure Requirements
Electric gynecological chairs list at USD 2,950-7,500, compared with USD 1,050-2,400 for manual models, a 2-3X differential that strains ASC and rural-clinic budgets. Add 10-15% for installation and USD 500-1,100 for accessories and the outlay becomes formidable; a 10-room women's center can spend USD 50-75 thousand on chairs alone. Refurbished or subscription-priced offerings lower entry barriers, but uptake remains modest amid concerns about warranties and residual value.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advancements in Examination Chairs
- Increasing Focus on Patient Comfort and Safety
- Stringent Regulatory and Compliance Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, electric motorized units accounted for 47.67% of the gynecological examination chairs market share and are projected to grow at a CAGR of 8.54%. This growth is driven by programmable memory presets, which reduce patient setup time by nearly 40%. Hospitals increasingly favor these units due to their IoT telemetry capabilities, which integrate directly with asset-management software. As a result, electric motorized units are becoming the standard choice in high-income regions. While hydraulic and electro-hydraulic hybrids remain prevalent in cost-sensitive markets, demand for powered height adjustments is rising to meet forthcoming accessibility regulations. Although smart, fully connected chairs currently represent less than 5% of shipments, they have demonstrated a nearly one-third reduction in downtime during North American pilot programs. This positions the segment for significant growth as cybersecurity frameworks mature.
Regulatory and sustainability pressures are further driving the adoption of powered models. Compliance with EPA sterilant regulations is simplified when detachable components are reprocessed with hydrogen peroxide or radiation rather than ethylene oxide. In 2024, OEM reprocessing programs recovered 5 million pounds of equipment, resulting in USD 239 million in customer savings. These lifecycle-cost advantages align with the priorities of value-based procurement committees. Meanwhile, manual tables are increasingly non-compliant with ADA height-adjustment standards and are expected to be relegated to ultra-low-budget or humanitarian applications.
Complete Report Scope:
- By Product Type
- Non-Electric (Manual)
- Electric (Motorised)
- Hydraulic
- Electro-Hydraulic Hybrid
- Smart / IoT-Integrated Models
- By End User
- Hospitals
- Private Clinics
- Diagnostic Centres
- Ambulatory Surgical Centres
- Retail / Minute Clinics
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
In 2025, North America contributed 41.56% of the total revenue, driven by over 6,300 Ambulatory Surgical Centers (ASCs), ongoing hospital refresh cycles, and the enforcement of accessibility regulations disqualifying many fixed-height tables. The expansion of retail clinics in the U.S. is attracting new non-hospital buyers, while Canadian provincial mandates are fueling demand for ISO-certified equipment with bilingual support.
Asia-Pacific is positioned as the fastest-growing region, with a projected 7.54% CAGR through 2031. Key drivers include India's Ayushman Bharat initiative, China's plan to establish 1,000 county-level hospitals for women and children, and AIIB-funded clinic modernizations in Indonesia. These developments are generating significant demand for electric and hybrid chairs that comply with WHO ergonomic standards. Local manufacturers are maintaining competitive pricing below USD 2,000, enabling widespread adoption even in tier-two cities.
In Europe, single-payer procurement systems ensure stable volumes but exert pressure on margins. Sustainability clauses in procurement contracts are increasingly favoring vendors offering circular-economy solutions. The Middle East market is bifurcated, with high-end Gulf hospital chains contrasting with donor-funded initiatives in Sub-Saharan regions, which primarily procure manual or cost-effective hybrid solutions. In Latin America, currency fluctuations moderate growth; however, Brazil and Argentina continue to drive steady public tender activity aligned with national women's health programs.
- A-dec
- ABCO Health Care
- AGA Sanitatsartikel GmbH
- ArjoHuntleigh
- Avante Health Solutions
- Desco Medical
- GIMA S.p.A.
- Hill Laboratories Company
- Hill-Rom Holdings Inc. (Baxter)
- Inmoclinc S.A.
- Innomed Kozep-Europai Zrt.
- LINET Group
- Malvestio S.p.A.
- Medifa-Hesse GmbH & Co. KG
- Midmark
- Oakworks Medical Inc.
- PMT Healthcare Pvt. Ltd.
- Promotal
- Schmitz u. Sohne GmbH & Co. KG
- Sonesta AB
- Stryker
- Taicang Kang Hui (Medik)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Burden of Women's Health Disorders
- 4.2.2 Expansion of Global Healthcare Infrastructure
- 4.2.3 Technological Advancements in Examination Chairs
- 4.2.4 Increasing Focus on Patient Comfort and Safety
- 4.2.5 Integration of Digital Health and IoT Solutions
- 4.2.6 Shift Toward Decentralized and Outpatient Care Delivery
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure Requirements
- 4.3.2 Stringent Regulatory and Compliance Standards
- 4.3.3 Limited Space and Workflow Constraints in Clinics
- 4.3.4 Environmental Sustainability and Lifecycle Considerations
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Non-Electric (Manual)
- 5.1.2 Electric (Motorised)
- 5.1.3 Hydraulic
- 5.1.4 Electro-Hydraulic Hybrid
- 5.1.5 Smart / IoT-Integrated Models
- 5.2 By End User
- 5.2.1 Hospitals
- 5.2.2 Private Clinics
- 5.2.3 Diagnostic Centres
- 5.2.4 Ambulatory Surgical Centres
- 5.2.5 Retail / Minute Clinics
- 5.3 Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 Japan
- 5.3.3.3 India
- 5.3.3.4 Australia
- 5.3.3.5 South Korea
- 5.3.3.6 Rest of Asia-Pacific
- 5.3.4 Middle East & Africa
- 5.3.4.1 GCC
- 5.3.4.2 South Africa
- 5.3.4.3 Rest of Middle East & Africa
- 5.3.5 South America
- 5.3.5.1 Brazil
- 5.3.5.2 Argentina
- 5.3.5.3 Rest of South America
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)}
- 6.3.1 A-Dec Inc.
- 6.3.2 ABCO Health Care
- 6.3.3 AGA Sanitatsartikel GmbH
- 6.3.4 ArjoHuntleigh
- 6.3.5 Avante Health Solutions
- 6.3.6 Desco Medical India
- 6.3.7 GIMA S.p.A.
- 6.3.8 Hill Laboratories Company
- 6.3.9 Hill-Rom Holdings Inc. (Baxter)
- 6.3.10 Inmoclinc S.A.
- 6.3.11 Innomed Kozep-Europai Zrt.
- 6.3.12 LINET Group SE
- 6.3.13 Malvestio S.p.A.
- 6.3.14 Medifa-Hesse GmbH & Co. KG
- 6.3.15 Midmark Corporation
- 6.3.16 Oakworks Medical Inc.
- 6.3.17 PMT Healthcare Pvt. Ltd.
- 6.3.18 Promotal SAS
- 6.3.19 Schmitz u. Sohne GmbH & Co. KG
- 6.3.20 Sonesta AB
- 6.3.21 Stryker Corporation
- 6.3.22 Taicang Kang Hui (Medik)
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


