

|
시장보고서
상품코드
2117395
스페인의 광물 처리 장비 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Spain Mineral Processing Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 스페인의 광물 처리 장비 시장 규모는 2025년에 2,212만 달러로 평가되었습니다. 2026년 2,370만 달러에서 2031년까지 3,201만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 6.20%를 나타낼 전망입니다.
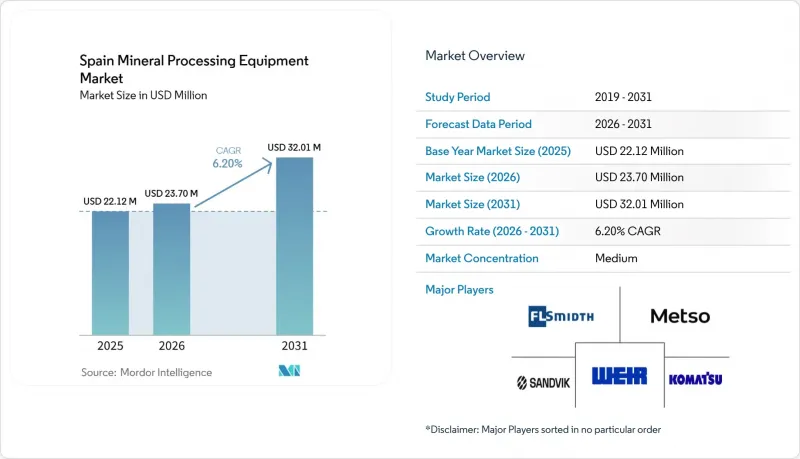
본 보고서는 광물 채굴 부문(보크사이트, 철광석 등), 장비 유형(파쇄기, 컨베이어 등), 채굴 방법(노천 채굴, 지하 채굴), 자동화 수준(수동, 반자동 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(단위)으로 제시되어 있습니다.
스페인의 광물 처리 장비 시장 동향 및 인사이트
주요 배터리용 광물에 대한 국내 수요 증가
스페인의 ‘광물 자원 행동 계획(2026-2030년)’은 1970년대 이후 스페인 최초로 시행되는 체계적인 탐사 프로그램으로, 갈리시아에서 안달루시아에 이르는 서부 회랑 전역의 리튬, 코발트, 흑연 및 희토류를 대상으로 하고 있습니다. ‘중요 원자재법’에 따른 전략적 지위 덕분에 허가 및 승인 절차가 간소화되고 유럽투자은행(EIB)의 대출이 승인됨에 따라, 스포듀멘 및 레피돌라이트 광석을 위해 설계된 부유 셀, 오토클레이브, 이온 교환 회로 설비 발주가 이미 가속화되고 있습니다. 스페인에서는 발렌시아와 나바라에 기가팩토리가 건설됨에 따라 두 곳의 리튬 허브가 조성되고 있습니다. 이러한 협력을 통해 중요한 판매처가 확보되고, 가공 플랜트의 초기 설비 투자 위험이 경감됩니다. 그 결과, 스페인 내 리튬 관련 설비의 성장률은 해당국의 광물 처리 장비 시장 전체 성장률을 상회하고 있습니다. 또한, 대학에서 검증된 페더슨(Pedersen) 방식의 전해법은 기존의 바이어(Buyer) 방식에 비해 물 사용량을 대폭 줄여, 국내 OEM 제조업체에 뚜렷한 환경적 우위를 제공합니다. 이러한 전략적 움직임들이 어우러져, 스페인은 EU 내 배터리 등급 광물의 전환 능력 면에서 가장 유력한 후보국으로서의 입지를 확고히 하고 있습니다.
EU의 ‘넷제로 산업법’에 따른 현지화 인센티브
‘넷제로 산업법’은 2030년까지 연간 도입되는 전략적 기술의 40%를 EU 역내에서 제조하도록 의무화하고 있어, 사실상 EU산 광물 처리 장비를 우대하는 것입니다. 스페인이 포르투갈과 공동으로 추진하는 ‘이베리아 황철광 벨트’ 프로젝트는 기준의 조화를 도모하여 OEM 각사가 두 국내 시장을 아우르며 연구 개발을 확대할 수 있도록 하고, 모듈식 파쇄·이송 라인의 단위당 설비 투자를 절감하고 있습니다. 2025년에 채택된 재정 조치에는 신규 수산화리튬 정제소에 대한 가속 상각 및 세액 공제가 포함되어 있어, 이에 따라 가압 산화 오토클레이브 및 용매 추출용 믹서의 수주가 더욱 증가하고 있습니다. ‘전략적 프로젝트’로 지정됨에 따라 인허가 취득 기간이 약 24-27개월로 단축되어, 기성 모듈을 제공하는 공급업체들이 맞춤형 제품을 제조하는 제조업체들을 제치고 시장 점유율을 확대되고 있습니다. ESG 준수는 현재 공공 자금의 공동 출자를 받기 위한 조건이 되고 있어, 각 벤더사는 실시간 배출량 및 수질 분석 기능을 표준 사양으로 통합하도록 압박받고 있습니다.
환경 허가 취득까지의 장기화
안달루시아 주가 추가 영향 평가를 요구함에 따라, 아즈날코할 구리·아연 광산의 가동 재개는 당초 2025년에서 2027년으로 연기되었습니다. 이러한 지연은 전략적 사이트로 간주되는 곳이라 하더라도 다층적인 심사를 통해 일정이 최대 3년까지 연장될 수 있음을 여실히 보여주고 있습니다. 한편, 갈리시아 주의 미나 무가(Mina Muga) 텅스텐 프로젝트는 주로 ‘나투라 2000(Natura 2000)’과 관련된 우려를 이유로 12년에 걸친 심사 수렁에 빠져 있습니다. 이러한 우려는 설비 발주를 동결시킨 것은 물론, OEM 업체들이 엔지니어링 자원을 배정하는 것을 주저하게 만드는 요인이 되고 있습니다. CRMA(환경 관리 인증) 취득을 통해 이러한 심사 기간을 약 26개월까지 단축할 가능성이 있지만, 2026년 초 시점에서 스페인 국내에서 이 인증을 취득한 사업은 불과 7건에 그치고 있습니다. 그 결과, 신청자의 대다수는 기존의, 더 장기화되는 제도에 얽매인 채로 남아 있습니다. 이러한 지연은 구체적인 영향을 미치고 있으며, 스페인의 광물 처리 장비 시장 성장은 현저히 둔화되고 있습니다. 특히, 사업자들이 최종 허가를 기다리며 구매를 미루고 있기 때문에 대형 파쇄기나 지상 컨베이어가 가장 큰 타격을 받고 있습니다.
부문별 분석
2025년, 철광석을 주축으로 하는 사업은 스페인 광물 처리 장비 시장 수요의 34.18%를 차지했습니다. 이는 하이드로사이클론과 건식 중력 선별을 채택한 미나스 데 아르키페(Minas de Arquife)사의 연간 4.5 Mt 마그네티트 처리 회로가 주도한 결과입니다. 리튬 분야는 도입 규모는 작지만 연평균 성장률(CAGR) 6.95%로 확대되고 있습니다. 이는 에스트레마두라 주와 갈리시아 주에서 유럽연합 집행위원회(EC)의 지원을 받고 있는 두 프로젝트가 고밀도 매체 분리기, 소성로, 컨테이너형 부유 선별 라인을 필요로 하고 있음을 반영합니다.
배터리용 광물의 중요성이 높아짐에 따라 습식 야금용 오토클레이브 및 이온 교환 컬럼에 대한 수요가 급증하고 있습니다. 동시에 철 생산 업체들은 에너지 소비를 줄이기 위해 에너지 효율이 높은 HPGR(고압 압연기) 및 에어 클래시파이어로의 전환을 추진하고 있습니다. 토지 복원과 자원 회수를 연계한 정부 보조금으로 인해 바이오레칭 반응기에 대한 수요가 증가하고 있습니다. 이러한 반응기는 현재 광미에서 코발트, 안티몬, 게르마늄을 추출하는 데 매우 중요한 역할을 하고 있습니다. 그 결과, 2029년까지 스페인의 리튬 광물 처리 장비 시장은 보크사이트 시장을 넘어설 전망입니다. 이러한 변화에 발맞추어 각 공급업체들은 연구 개발의 중점을 저수량 플로우시트 및 디지털 추적성 강화로 재조정하고 있습니다.
2025년 지출에서 파쇄기는 28.33%라는 최대 점유율을 유지했으나, 메츠오(Metso)사의 ‘FIT’ 및 ‘Foresight’ 시리즈 덕분에 현장 조립 시간을 15% 단축할 수 있었기 때문에 모듈식 설계의 컨베이어는 연평균 성장률(CAGR) 7.03%로 성장하고 있습니다. 2026년 3월에 도입된 샌드빅(Sandvik)사의 CH442 및 CH662 콘 크러셔는 엘라스토머 라이너를 폐지하고 유지보수 주기를 1년으로 연장함으로써, 재료 과학이 가동 시간을 어떻게 향상시키고 있는지를 보여주고 있습니다.
가변 주파수 구동 벨트를 통해 가격 급등 시기에 처리량을 조정할 수 있게 되어, 계통 연계형 태양광 발전의 경제성이 향상되고 있습니다. 자율형 드릴 및 브레이커는 예측 마모 알고리즘을 통해 리그 수명을 40% 연장하여, 예방 정비에서 상태 기반 정비로의 광범위한 전환을 뒷받침하고 있습니다. 폐루프식 물 관리 의무화에 따라 ‘기타’ 범주에 속하는 압력 필터 및 페이스트 백필 플랜트의 수주도 동시에 증가하고 있습니다. 이러한 일련의 동향은 스페인의 광물 처리 장비 시장 전체에서 모듈화 및 자동화를 향한 조달 경향을 더욱 강화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.02According to Mordor Intelligence, the spanish mineral processing equipment market size was valued at USD 22.12 million in 2025 and estimated to grow from USD 23.70 million in 2026 to reach USD 32.01 million by 2031, at a CAGR of 6.20% during the forecast period (2026-2031).
This report is Segmented by Mineral Mining Sector (Bauxite, Iron, and More), Equipment Type (Crushers, Conveyors, and More), Mining Method (Surface Mining, Underground Mining), and Automation Level (Manual, Semi-Automated, and More). Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Spain Mineral Processing Equipment Market Trends and Insights
Rising Domestic Demand for Critical Battery Minerals
Spain's Mineral Raw Materials Action Plan (2026-2030) is the nation's first systematic exploration program since the 1970s and targets lithium, cobalt, graphite, and rare earths across the western corridor from Galicia to Andalusia . Strategic status under the Critical Raw Materials Act grants streamlined permitting and EIB financing, which is already accelerating equipment orders for flotation cells, autoclaves, and ion-exchange circuits designed for spodumene and lepidolite ores. In Spain, two lithium hubs are aligning with the construction of gigafactories in Valencia and Navarra. This synchronization establishes a crucial offtake anchor, mitigating upfront capital expenditure risks for processing plants. As a result, the growth of lithium equipment in Spain outpaces the overall growth of the country's mineral processing equipment market. Furthermore, the Pedersen electrolysis, validated by universities, significantly reduces water usage compared to the traditional Bayer process, offering domestic OEMs a notable environmental edge. These strategic moves collectively position Spain as the leading contender in the EU for battery-grade mineral conversion capacity.
EU Net-Zero Industry Act Localization Incentives
The Net-Zero Industry Act mandates that 40% of annually deployed strategic technologies be made inside the bloc by 2030, effectively favoring EU-sourced mineral processing equipment. Spain's joint Iberian Pyrite Belt work with Portugal harmonizes standards and allows OEMs to scale R&D across two national markets, cutting per-unit capex for modular crushing and conveying lines. Fiscal measures adopted in 2025 include accelerated depreciation and tax credits for new lithium hydroxide refineries, driving incremental orders for pressure-oxidation autoclaves and solvent-extraction mixers. Strategic project designations compress permitting to around 24-27 months, so suppliers with off-the-shelf modules gain share at the expense of bespoke fabricators. ESG compliance now acts as a gateway for public co-funding, pushing vendors to integrate real-time emissions and water analytics as standard features.
Lengthy Environmental Permitting Timelines
Andalusia's demand for additional impact studies pushed back Aznalcollar's copper-zinc restart from a 2025 target to 2027. This delay underscores how multi-layer reviews can extend timelines by up to three years, even for sites deemed strategic. Meanwhile, Galicia's Mina Muga tungsten project has been ensnared in a 12-year review, primarily due to Natura 2000 concerns. These concerns have not only frozen equipment orders but also dissuaded OEMs from allocating engineering resources. While CRMA status can potentially shorten these timelines to around 26 months, by early 2026, only seven ventures in Spain had achieved this status. As a result, the majority of applicants remain bound by the older, more protracted regime. Such delays have tangible repercussions: Spain's mineral processing equipment market growth sees a notable dip. Notably, large crushers and overland conveyors are feeling the brunt, as operators postpone purchases, awaiting final permits.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Brown-field Plant Digital Retrofits
- Growing Government Support for the Mining Sector
- Tight Water-use Restrictions in Drought-prone Mining Regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Iron-focused operations generated 34.18% of Spain's mineral processing equipment market demand in 2025, anchored by Minas de Alquife's 4.5 Mt/y magnetite circuit that relies on hydrocyclones and dry gravimetric sorting. Lithium, although starting from a smaller installed base, is expanding at a 6.95% CAGR, reflecting two EC-backed projects in Extremadura and Galicia that require dense-media separators, roasting kilns, and containerized flotation lines.
As battery minerals gain prominence, there's a surge in demand for hydrometallurgical autoclaves and ion-exchange columns. Concurrently, iron producers are turning to energy-efficient HPGRs and air classifiers to reduce energy consumption. Government grants, which tie land rehabilitation to resource recovery, are boosting the demand for bio-leach reactors. These reactors are now pivotal in extracting cobalt, antimony, and germanium from tailings. Consequently, by 2029, the Spanish market for lithium mineral processing equipment is set to outpace that of bauxite. This shift is prompting vendors to recalibrate their R&D focus towards low-water flowsheets and enhanced digital traceability.
Crushers retained the largest 28.33% slice of 2025 spending, but modular-design conveyors are advancing at a 7.03% CAGR thanks to Metso's FIT and Foresight lines that shorten on-site assembly by 15%. Sandvik's CH442 and CH662 cone crushers, introduced in March 2026, remove elastomer liners and extend maintenance intervals to a full year, illustrating how materials science is improving uptime.
Variable-frequency-drive belts allow throughput modulation during price peaks, improving grid-integrated solar economics. Autonomous drills and breakers extend rig life by 40% through predictive wear algorithms, supporting the broader shift from preventive to condition-based maintenance. Closed-loop water mandates are simultaneously elevating orders for pressure filters and paste-backfill plants that fall under the "Others" category. Altogether, these dynamics reinforce a procurement tilt toward modularity and automation across the Spanish mineral processing equipment market.
Complete Report Scope:
- By Mineral Mining Sector
- Bauxite
- Iron
- Lithium
- Others
- By Equipment Type
- Crushers
- Conveyors
- Drills and Breakers
- Feeders
- Others
- By Mining Method
- Surface Mining
- Underground Mining
- By Automation Level
- Manual
- Semi-Automated
- Fully Automated
List of Companies Covered in this Report:
- FLSmidth A/S
- Metso Corporation
- Sandvik AB
- The Weir Group PLC
- Komatsu Ltd.
- Haver & Boecker
- TAKRAF Group
- Astec Industries Inc.
- Terex Corporation
- Sotecma S.L.
- Talleres Alquezar S.A.
- Eriez Global
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Domestic Demand for Critical Battery Minerals
- 4.2.2 EU Net-Zero Industry Act Localization Incentives
- 4.2.3 Surge in Brown-field Plant Digital Retrofits
- 4.2.4 Growing Government Support for the Mining Sector
- 4.2.5 Circular Economy Mandates on Mine Waste Valorization
- 4.2.6 Low-carbon Equipment Financing from Spanish Green Banks
- 4.3 Market Restraints
- 4.3.1 Lengthy Environmental Permitting Timelines
- 4.3.2 Tight Water-use Restrictions in Drought-prone Mining Regions
- 4.3.3 Shortage of Skilled Automation Technicians
- 4.3.4 Volatile Electricity Prices Impacting OPEX
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Mineral Mining Sector
- 5.1.1 Bauxite
- 5.1.2 Iron
- 5.1.3 Lithium
- 5.1.4 Others
- 5.2 By Equipment Type
- 5.2.1 Crushers
- 5.2.2 Conveyors
- 5.2.3 Drills and Breakers
- 5.2.4 Feeders
- 5.2.5 Others
- 5.3 By Mining Method
- 5.3.1 Surface Mining
- 5.3.2 Underground Mining
- 5.4 By Automation Level
- 5.4.1 Manual
- 5.4.2 Semi-Automated
- 5.4.3 Fully Automated
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 FLSmidth A/S
- 6.4.2 Metso Corporation
- 6.4.3 Sandvik AB
- 6.4.4 The Weir Group PLC
- 6.4.5 Komatsu Ltd.
- 6.4.6 Haver & Boecker
- 6.4.7 TAKRAF Group
- 6.4.8 Astec Industries Inc.
- 6.4.9 Terex Corporation
- 6.4.10 Sotecma S.L.
- 6.4.11 Talleres Alquezar S.A.
- 6.4.12 Eriez Global
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


