

|
시장보고서
상품코드
2124391
광물 처리 장비 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Mineral Processing Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
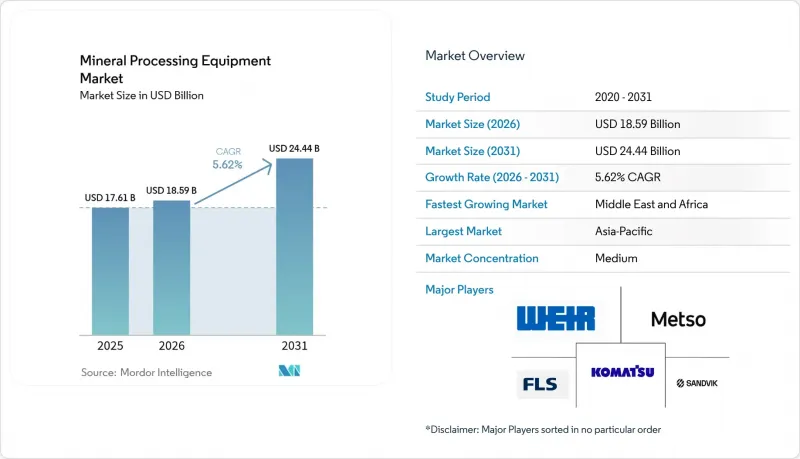
에 의하면, 광물 처리 장비 시장 규모는 2025년에 176억 1,000만 달러로 평가되었고 2026년 185억 9,000만 달러에서 2031년까지 244억 4,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.62%를 나타낼 전망입니다.
본 보고서는 광물 채굴 부문별(보크사이트, 구리, 철, 리튬, 니켈, 희토류 원소, 금 및 귀금속, 기타), 장비별(파쇄기 및 분쇄기, 스크린 및 분리기, 기타),가공 단계별(파쇄·분쇄, 기타), 최종 사용자 산업별(광물·광석 채굴 기업, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 광물 처리 장비 시장 동향 및 인사이트
전기차(EV)용 배터리 금속 붐(리튬, 니켈)
배터리 등급 원료에 대한 수요의 급증은 광물 처리 장비 시장에 현저한 변화를 가져오고 있습니다. 리튬 프로젝트에서는 99.5% 이상의 순도를 실현할 수 있는 특수한 소성, 침출, 결정화 회로가 필요하며, 이로 인해 Metso의 pCAM 및 칼시네이터 패키지에 대한 신규 수주가 촉진되고 있습니다. 니켈 라텔라이트 처리 분야에서도 대형 오토클레이브, 황산 침출 반응기, 하류 용매 추출 장비가 마찬가지로 수혜를 보고 있습니다. 호주, 인도네시아, 칠레에서 투자자들이 배터리용 금속의 통합 허브 건설을 급속도로 추진하는 가운데, 고온·고압 설계 실적을 보유한 OEM 각사는 높은 이익률을 확보하고 있습니다. 그 결과로 발생하는 생산 능력 확대 덕분에, 범용 원자재에 대한 투자가 둔화되더라도 장비 수요는 두 자릿수 성장세를 유지하고 있습니다. 또한, 각 공급업체는 배터리용 금속 1톤당 ‘제조 시작부터 출하까지(cradle-to-gate)’의 배출량을 추적하는 ESG 보고 모듈도 도입하고 있습니다.
저품위 광석으로의 전환이 대용량 파쇄기 수요를 견인
구리, 금, 철광석의 평균 품위는 계속해서 하락하고 있어, 금속 생산량을 유지하기 위해서는 플랜트가 더 많은 처리량을 처리할 수밖에 없는 상황입니다. HPGR 회로는 20-40%의 에너지 절감 효과를 가져오고, 더 미세한 입도 분포를 실현함으로써 다운스트림 공정인 부유 회수율을 향상시킵니다. 이는 위어 그룹의 ‘ENDURON’이 호주와 칠레의 광산에 도입된 사례에서도 입증되었습니다. 해당 광산에서는 정격 처리 능력 2만 t/h의 1차 파쇄기를 개조하고, 제어 루프를 닫는 실시간 입자경 분석 장치를 병용하고 있습니다. 이러한 연쇄적인 효과로 인해 더 많은 슬러리 처리량을 처리할 수 있는 스크린, 사이클론, 탈수 장치에 대한 수요가 증가하고 있습니다. 분쇄부터 선별까지 통합 패키지를 제공하는 공급업체들은 추가적인 서비스 수익을 창출하고 있으며, 이는 광물 처리 장비 시장에서 ‘고처리량·저비에너지’ 솔루션에 대한 집중을 뒷받침하고 있습니다.
그린필드 광산에 대한 ESG 주도 자본 배분 제한
기관 투자자들은 엄격한 ESG 기준을 적용하고 있으며, 이로 인해 신규 광산의 승인 절차가 지연되고 관련 플랜트의 수주도 늦어지고 있습니다. 캐나다의 신규 철광석 및 구리 프로젝트에서는 현재 초기 단계부터 탄소 중립적인 처리 설계를 요구하고 있어, 이로 인해 설치 비용이 최대 20% 증가하고 있습니다. 허가 취득 절차의 장기화로 인해 분쇄기 및 제련기에 대한 단기 수요는 압박을 받고 있지만, 반면 분진 억제 시스템 및 물 재활용 시스템에 대한 개조 수주는 증가하고 있습니다. 각 OEM 업체들은 토지에 미치는 영향을 최소화하고 환경 심사 기간을 단축하는 모듈식 이동 가능 플랜트를 제공함으로써 이에 대응하고 있으며, 광물 처리 장비 시장에서 소규모이면서도 신속하게 진행되는 수주 파이프라인을 유지하고 있습니다.
부문 분석
2031년까지 리튬 시장의 연평균 성장률(CAGR)이 13.58%라는 급격한 성장을 기록하고 있다는 사실은 광물 처리 장비 시장의 구조적 변화를 여실히 보여주고 있습니다. ‘기타’로 분류되는 벌크 상품은 여전히 2025년 광물 처리 장비 시장 규모의 89.55%를 차지하고 있지만, 배터리용 금속 플랜트에서는 불순물 함량을 극한까지 낮추도록 설계된 소성로, 용매 추출용 믹서, 결정화 장치가 채택되고 있습니다. 자동차 제조업체들이 안전하고 추적 가능한 공급망을 요구하는 가운데, 광물 처리 장비 시장은 투자자들의 관심을 모으고 있습니다. 기존 철광석과 구리의 유통량은 여전히 크지만, 그 한 자릿수 성장률은 중요 광물 부문의 두 자릿수 성장과 뚜렷한 대조를 이루고 있습니다.
구리와 금의 원광 등급이 지속적으로 하락함에 따라 HPGR(고압 분쇄 롤), 미세 분쇄, 플래시 부양 장치의 설비 투자 주기가 장기화되고 있습니다. 처리량은 적지만, 희토류 원소의 유통 경로에서는 복잡한 다단계 분리가 요구되고 높은 단가가 책정되기 때문에 이익률에 대한 기여도가 높아지고 있습니다. 따라서 공급업체들은 수용액 야금법 및 선택적 침출법을 위한 연구 개발(R&D)에 주력하며, 기존 대량 상품에 대한 의존도와 고성장 전문 분야 간의 균형을 맞추고 있습니다.
2025년에는 광물 처리 장비 시장 규모에서 파쇄기와 분쇄기가 최대 점유율(32.72%)을 차지했으나, 2031년까지의 연평균 성장률(CAGR)이 가장 높은 분야는 첨단 부양 셀로 5.88%였습니다. 복잡한 납·아연 광석이나 니켈 광석을 처리하는 플랜트에서는 품위를 유지하기 위해 자동화된 기류 제어 시스템이나 거품 카메라 시스템이 채택되고 있습니다. 일체형 스키드 탑재형 부유 모듈은 납기 기간을 6개월로 단축하여 신속한 진행이 요구되는 리튬 프로젝트에 적합합니다.
다운스트림 공정에서는 고처리 용량의 농축기 및 페이스트 충전 플랜트가 광미 댐의 위험을 해결하고, 마모 성능 센서가 장착된 스마트 슬러리 펌프가 정밀 점검까지의 평균 간격을 연장하고 있습니다. 따라서 광물 처리 장비 시장 점유율 구성은 수자원 관리와 가치 회수의 우선순위가 높아지고 있음을 반영하여, 분리 및 광미 처리 부문으로 점차 이동하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 67.92%를 차지하며, 광물 처리 장비 시장의 중심지로서의 위치를 유지하고 있습니다. 중국의 거대한 제련 및 정련 기반은 타의 추종을 불허하는 규모로 파쇄기, 분쇄기, 여과 장비를 흡수하고 있습니다. 호주의 주요 철광석 기업들은 연간 700 Mt 이상의 생산 능력을 확보하고 있으며, HPGR(수평 맷돌식 분쇄기) 및 선별 설비의 업그레이드를 지속하고 있습니다. 한편, 인도네시아의 니켈 라테라이트 프로젝트에서는 오토클레이브 및 산 공장과 연계된 설비가 요구되고 있습니다. 인도의 중요 광물에 대한 ‘생산 연동형 인센티브 제도’와 광업법 개정은 2025-2030년까지 설비 수요 증가를 뒷받침할 리튬 및 흑연의 그린필드 개발을 촉진하고 있습니다.
중동 및 아프리카는 2031년까지 9.82%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 이는 사우디아라비아, 나미비아, 앙골라가 인산염, 구리, 희토류 자원의 수익화를 위해 국가 자본을 투입하고 있기 때문입니다. 태양광 발전 기반의 해수 담수화 플랜트가 물을 대량으로 소비하는 농축 플랜트에 물을 공급함으로써 단위당 운영 비용을 절감하고 있습니다. 마아덴(Maaden)사의 거대 인산염 복합 시설은 광산에서 비료에 이르는 통합된 흐름의 좋은 사례이며, 펌프, 증점기, 회전식 건조기에 관한 서비스 계약을 수주했습니다. 더반, 무스카트, 테마에 설치된 현지 유지보수 거점은 물류 지연을 줄여주어, 현지 기술자에 투자하는 OEM에 유리하게 작용하고 있습니다. 북미와 유럽에서는 공급망 안전 확보를 중시하는 정책을 배경으로 한 자릿수 중반의 성장률을 기록하고 있습니다. 미국 연방 정부의 보조금에 힘입어 국내 수산화 리튬 정제소 건설이 가속화되고 있으며, 소성 장치 및 결정화 장치의 전문 제조업체들이 그 혜택을 보고 있습니다. EU의 ‘중요 원료법’은 희토류 분리 및 배터리 재활용에 보조금을 지급하고 있어, 컬럼 부유 플랜트 및 수력 선광 플랜트의 수주를 뒷받침하고 있습니다. 남미의 리튬 트라이앵글은 여전히 성장세를 유지하고 있지만, 안데스 고원의 물 사용 제한으로 인해 염수 소비량이 적은 직접 리튬 추출(DLE) 모듈의 도입이 확대되고 있습니다. 지정학적 요인, ESG 요구, 자원 민족주의가 맞물려 지역별 장비 조달 패턴을 재편하고 있으며, 이는 광물 처리 장비 시장의 광범위한 성장을 뒷받침하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the mineral processing equipment market size was valued at USD 17.61 billion in 2025 and estimated to grow from USD 18.59 billion in 2026 to reach USD 24.44 billion by 2031, at a CAGR of 5.62% during the forecast period (2026-2031).
This report is Segmented by Mineral Mining Sector (Bauxite, Copper, Iron, Lithium, Nickel, Rare-Earth Elements, Gold and Precious Metals, Others), Equipment (Crushers and Mills, Screens and Separators, and More), Processing Stage (Crushing and Grinding, and More), End-User Industry (Mineral/Ore Mining Companies, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Mineral Processing Equipment Market Trends and Insights
EV-Battery Metal Boom (Lithium, Nickel)
Soaring demand for battery-grade inputs drives a pronounced shift in the Mineral Processing Equipment market. Lithium projects require specialized roasting, leaching, and crystallization circuits able to deliver 99.5%+ purity levels, prompting new orders for Metso's pCAM and calciner packages. Nickel laterite processing equally benefits larger autoclaves, sulfuric-acid leach reactors, and downstream solvent-extraction units. OEMs with high-temperature, high-pressure design credentials command premium margins as investors fast-track integrated battery-metal hubs in Australia, Indonesia, and Chile. The resulting capacity build-out sustains double-digit equipment demand even when bulk-commodity spending moderates. Suppliers also integrate ESG reporting modules that trace cradle-to-gate emissions for each tonne of battery metal.
Shift to Finer-Grade Ores Driving High-Capacity Crushers
Copper, gold, and iron ore head grades continue to fall, obliging plants to process larger tonnages to maintain metal output. HPGR circuits yield 20-40% energy savings and finer product size distributions that elevate downstream flotation recovery, as demonstrated by Weir Group's ENDURON installs Mines in Australia and Chile retrofit primary crushers with 20,000 t/h nameplate capacities, complemented by real-time particle-size analyzers that close the control loop. This cascading effect lifts demand for screens, cyclones, and dewatering equipment sized for higher slurry volumes. Suppliers that provide integrated comminution-to-classification packages capture added service revenue, reinforcing the Mineral Processing Equipment market's focus on high-throughput, low-specific-energy solutions.
ESG-Driven Capital Rationing for Green-Field Mines
Institutional investors apply stringent ESG filters, slowing approvals for new mines and delaying linked plant orders. Greenfield iron ore and copper projects in Canada now require upfront carbon-neutral processing designs, adding up to 20% to installed costs. Extended permitting cycles compress near-term demand for crushers and mills, even as retrofit orders for dust-suppression and water-recycling systems rise. OEMs respond with modular, relocatable plants that minimize land disturbance and shorten environmental reviews, preserving a pipeline of smaller, faster-moving purchase orders within the Mineral Processing Equipment market.
Other drivers and restraints analyzed in the detailed report include:
- CAPEX Surge in African Critical-Mineral Projects
- Digital-Twin Adoption for Plant-Wide Optimization
- Tightening Particulate-Matter Emission Norms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium's meteoric 13.58% CAGR through 2031 underscores structural change inside the mineral processing equipment market. Although bulk commodities under the "Others" banner still generated 89.55% of the mineral processing equipment market size in 2025, battery-metal plants are specifying calcination kilns, solvent-extraction mixers, and crystallizers built for ultra-low impurity thresholds. The Mineral Processing Equipment market captures investor enthusiasm as automakers seek secure, traceable supply chains. Traditional iron-ore and copper flows maintain large volumes; however, their single-digit growth contrasts sharply with double-digit expansion in critical mineral circuits.
Continued head-grade decline in copper and gold extends capex cycles for HPGR, fine-grinding, and flash-flotation gear. Though small in tonnage, rare-earth element circuits demand complex multi-stage separation that commands high unit pricing, lifting margin contribution. Suppliers thus allocate R&D toward hydrometallurgy and selective leaching, balancing legacy bulk-commodity exposure with high-growth specialty segments.
Crushers and mills represented the largest 32.72% slice of the mineral processing equipment market size in 2025, yet advanced flotation cells booked the quickest 5.88% CAGR through 2031. Plants processing complex lead-zinc or nickel ores adopt automated air-flow and froth-camera systems to sustain grade. Integrated skid-mounted flotation modules shorten delivery to six months, suiting fast-track lithium projects.
Downstream, high-rate thickeners and paste-fill plants address tailings dam risk, while smart slurry pumps with wear-performance sensors extend the mean time between overhauls. Therefore, the Mineral Processing Equipment market share mix tilts gradually toward separation and tailings handling, reflecting heightened water stewardship and value-recovery priorities.
Complete Report Scope:
- By Mineral Mining Sector
- Bauxite
- Copper
- Iron
- Lithium
- Nickel
- Rare-earth Elements
- Gold and Precious Metals
- Others
- By Equipment
- Crushers and Mills
- Screens and Separators
- Feeders and Conveyors
- Drills and Breakers
- Thickening and Clarification
- Flotation Cells
- Magnetic and Gravity Separators
- Pumps and Valves
- Filtration and Dewatering
- By Processing Stage
- Crushing and Grinding
- Screening and Sorting
- Concentration (Flotation/Separation)
- Dewatering
- Material Handling
- By End-User Industry
- Mineral/Ore Mining Companies
- Contract Processing Plants
- Recycling and Secondary Metals
- Aggregates and Construction
- Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Australia
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific, with 67.92% of 2025 turnover, remains the nucleus of the mineral processing equipment market. China's vast smelting and refining backbone absorbs crushers, mills, and filtration packages on an unparalleled scale. Australian iron-ore majors commit to 700+ Mt/y capacity, sustaining HPGR and screening upgrades, while Indonesian nickel laterite projects specify autoclaves and acid-plant tie-ins. India's Production-Linked Incentive scheme for critical minerals and mining code reforms stimulates greenfield lithium and graphite developments that underpin incremental equipment demand in 2025-2030.
The Middle East and Africa deliver the fastest 9.82% CAGR through 2031, as Saudi Arabia, Namibia, and Angola deploy sovereign capital to monetize phosphate, copper, and rare-earth resources. Solar-powered desalination plants feed water-intensive concentrators, cutting unit opex. Ma'aden's mega-phosphate complex exemplifies integrated mine-to-fertilizer flows, capturing service contracts for pumps, thickeners, and rotary dryers. Localized maintenance hubs in Durban, Muscat, and Tema mitigate logistics delays, favoring OEMs that invest in on-ground technicians. North America and Europe record mid-single-digit growth rates anchored by supply-chain security agendas. United States federal grants fast-track domestic lithium-hydroxide refineries, benefitting calciner and crystallizer specialists. The EU's Critical Raw Materials Act subsidizes rare-earth separation and battery recycling, boosting column-flotation and hydromet plant orders. South America's lithium triangle retains momentum, although water-use restrictions in the high Andes propel the adoption of direct-lithium-extraction (DLE) modules that consume less brine. Geopolitics, ESG imperatives, and resource nationalism jointly reshape regional equipment procurement patterns, sustaining broad-based Mineral Processing Equipment market growth.
- FLSmidth A/S
- Metso Corporation
- Komatsu Ltd.
- Sandvik AB
- The Weir Group PLC
- ThyssenKrupp AG
- TAKRAF GmbH
- CITIC Heavy Industries Co., Ltd.
- Terex Corporation
- Wirtgen GmbH
- Multotec (Pty) Ltd
- FEECO International, Inc.
- McLanahan Corporation
- Tenova S.p.A.
- Haver & Boecker Niagara GmbH
- Derrick Corporation
- Eriez Manufacturing Co.
- Astec Industries, Inc.
- Sotecma S.L.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV-Battery Metal Boom (Lithium, Nickel)
- 4.2.2 Shift To Finer-Grade Ores Driving High-Capacity Crushers
- 4.2.3 CAPEX Surge in African Critical-Mineral Projects
- 4.2.4 Digital-Twin Adoption for Plant-Wide Optimization
- 4.2.5 Green-Steel Initiatives Increasing Pelletizing Demand
- 4.2.6 AI-Based Ore-Sorting Reducing Downstream Energy Use
- 4.3 Market Restraints
- 4.3.1 ESG-Driven Capital Rationing for Green-Field Mines
- 4.3.2 Tightening Particulate-Matter Emission Norms
- 4.3.3 Skilled-Workforce Shortages in Remote Regions
- 4.3.4 Geopolitical Supply-Chain Nationalism on Key Spares
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD))
- 5.1 By Mineral Mining Sector
- 5.1.1 Bauxite
- 5.1.2 Copper
- 5.1.3 Iron
- 5.1.4 Lithium
- 5.1.5 Nickel
- 5.1.6 Rare-earth Elements
- 5.1.7 Gold and Precious Metals
- 5.1.8 Others
- 5.2 By Equipment
- 5.2.1 Crushers and Mills
- 5.2.2 Screens and Separators
- 5.2.3 Feeders and Conveyors
- 5.2.4 Drills and Breakers
- 5.2.5 Thickening and Clarification
- 5.2.6 Flotation Cells
- 5.2.7 Magnetic and Gravity Separators
- 5.2.8 Pumps and Valves
- 5.2.9 Filtration and Dewatering
- 5.3 By Processing Stage
- 5.3.1 Crushing and Grinding
- 5.3.2 Screening and Sorting
- 5.3.3 Concentration (Flotation/Separation)
- 5.3.4 Dewatering
- 5.3.5 Material Handling
- 5.4 By End-User Industry
- 5.4.1 Mineral/Ore Mining Companies
- 5.4.2 Contract Processing Plants
- 5.4.3 Recycling and Secondary Metals
- 5.4.4 Aggregates and Construction
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Chile
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Australia
- 5.5.4.4 Japan
- 5.5.4.5 South Korea
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 FLSmidth A/S
- 6.4.2 Metso Corporation
- 6.4.3 Komatsu Ltd.
- 6.4.4 Sandvik AB
- 6.4.5 The Weir Group PLC
- 6.4.6 ThyssenKrupp AG
- 6.4.7 TAKRAF GmbH
- 6.4.8 CITIC Heavy Industries Co., Ltd.
- 6.4.9 Terex Corporation
- 6.4.10 Wirtgen GmbH
- 6.4.11 Multotec (Pty) Ltd
- 6.4.12 FEECO International, Inc.
- 6.4.13 McLanahan Corporation
- 6.4.14 Tenova S.p.A.
- 6.4.15 Haver & Boecker Niagara GmbH
- 6.4.16 Derrick Corporation
- 6.4.17 Eriez Manufacturing Co.
- 6.4.18 Astec Industries, Inc.
- 6.4.19 Sotecma S.L.


