

|
시장보고서
상품코드
2117526
영국의 항공화물 부가 서비스 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)United Kingdom Air Freight Ancillary Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 영국의 항공화물 부가 서비스 시장 규모는 2025년에 39억 1,000만 달러로 평가되었고 2026년 42억 1,000만 달러에서 2031년까지 59억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 7.12%를 나타낼 전망입니다.
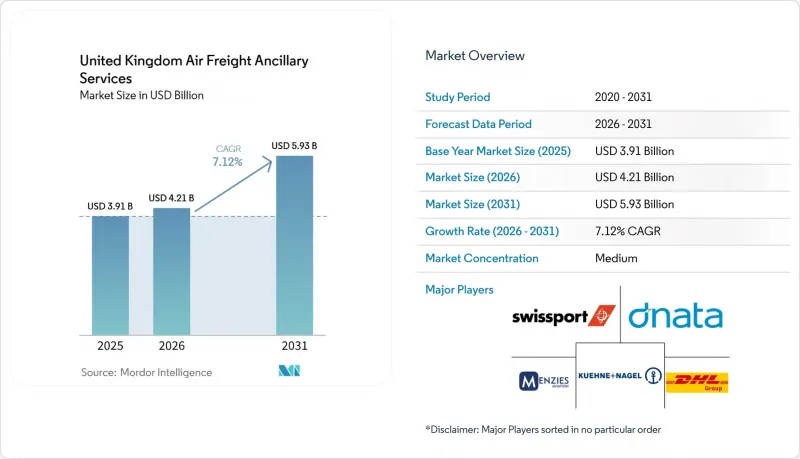
영국의 항공화물 부가 서비스 시장은 화물 운송 활동의 회복, 주요 허브 공항의 운송 능력 제약, 그리고 콜드체인 처리, 신속한 통관 절차, 출하 현황 가시화 등 부가가치 서비스에 대한 수요 증가에 힘입어 견조한 추세를 보이고 있습니다. 본 보고서는 서비스 유형(화물 취급, 혼재, 포장·라벨 부착 등), 출하 유형(국내·국제), 산업별(패션·명품, 전자상거래·소매, 가전, 식품 및 음료 등), 지역별(잉글랜드, 스코틀랜드 등)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
영국 항공화물 부가 서비스에 대한 인사이트 및 동향
시간 엄수가 요구되는 항공화물 취급에 대한 수요 증가
영국의 항공화물 시장은 첨단 바이오 의약품, 항공우주 부품, 반도체, 적시(JIT) 산업용 원자재 등 지연을 용납할 수 없는 화물로 더욱 전환되고 있습니다. 2025년에는 히스로 공항의 화물 처리량이 150만 톤으로 증가했으며, 해당 공항이 취급하는 화물 무역액은 2,930억 파운드(3,750억 달러)에 달했습니다. 이는 처리량 증가를 상회하는 가치 성장을 보여줍니다. 또한 히스로 공항은 2025년 12월에 처리 일수 사상 최고치를 기록했습니다. 이는 성수기에 업무가 집중되고 있음을 보여주며, 신속한 운송 및 우선 수취 서비스에 대한 프리미엄 가격 책정을 뒷받침하고 있습니다. 이러한 운영 패턴은 신속한 물리적 처리와 신뢰할 수 있는 디지털 추적 및 공간 배분을 결합할 수 있는 취급 업체에게 유리하게 작용합니다. 그 결과, 영국의 항공화물 부가 서비스 시장에서는 제한된 공항 시설 내에서 속도, 가시성, 규정 준수를 보장하는 서비스에 대한 수요가 증가하고 있습니다.
전자상거래, 항공화물 및 국경을 넘는 소포 흐름의 성장
전자상거래는 영국의 항공화물 부가 서비스 시장에 추가적인 서비스 부담을 가중시키고 있습니다. 이는 각 소포마다 통관, 라벨 부착, 반품, 추적과 같은 작업이 발생하며, 이러한 작업량은 화물 톤수보다 더 빠르게 증가하는 경향이 있기 때문입니다. 글래스고 프레스토윅 공항은 이러한 변화를 여실히 보여주는 사례입니다. 중국의 전자상거래 운송업체들은 해당 공항의 연중무휴 24시간 운영, 야간 운항 제한이 없는 체계, 그리고 중국 본토행 정기편을 활용하여 소포 중심의 물류 흐름을 뒷받침하고 있습니다. 2026년 7월 1일부터 EU의 150유로(174달러) ‘데미니스’ 관세 면제 조치가 폐지됨에 따라, 영국에서 유럽으로의 소포 운송에 따른 규정 준수 업무가 더욱 증가할 것이며, 이는 통관 대행 및 서류 작성 서비스를 직접 뒷받침하게 될 것입니다. 소포 유통에는 기존의 혼적 화물보다 신속한 스캔, 분류 및 예외 처리가 필요하기 때문에 익스프레스 허브와 지역 취급 업체도 혜택을 보고 있습니다. 이에 따라 전자상거래는 영국의 항공화물 부가 서비스 시장에서 단기적으로는 가장 강력한 수요 견인 역할을 계속하고 있습니다.
주요 공항의 슬롯 제약과 화물 운송 능력의 한계
히스로 공항은 슬롯 이용률이 거의 포화 상태이며, 이는 영국의 항공화물 부가 서비스 시장에서 물리적 처리 능력을 얼마나 빠르게 확대할 수 있는지에 대한 구조적 제약을 초래하고 있습니다. 히스로 공항에서 승인된 제3활주로는 화물 처리 능력을 50% 향상시키고, 연간 처리량을 300만 톤 증가시킬 것으로 예측됩니다. 그러나 관련 인프라 정비 계획의 사정상 그 혜택을 누릴 수 있는 시기는 2030년대 중반 이후가 될 가능성이 높습니다. 그 동안 WFS가 히스로 공항에 신설되는 11,000 m² 규모의 화물 시설에 대해 20년간의 임대 계약을 체결한 사례에서 볼 수 있듯이, 기존 사업자들은 희소한 공항 공간에 대해 막대한 비용을 지불하고 있습니다. 이러한 공간 프리미엄은 기존 사업자의 가격 결정력을 뒷받침하는 한편, 처리량 증가에 따른 확장을 억제하여 소규모 서비스 제공업체 시장 진입 장벽을 높게 유지하고 있습니다. 즉, 영국 항공화물 부가 서비스 시장의 단기적 성장은 이용 가능한 처리량의 전반적인 증가라기보다는 부가가치가 높은 하역 업무에 의존하게 될 것입니다.
부문 분석
2025년 기준, 온도 관리 서비스는 영국 항공화물 부가 서비스 시장 점유율의 32.46%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 8.49%로 확대될 것으로 예측됩니다. 이에 따라 콜드체인은 투자 우선순위와 서비스 차별화를 가장 명확하게 좌우하는 부문이 되었습니다. 수요는 엄격한 온도 관리가 필요한 의약품 화물과 신속한 항공 운송이 필요한 스코틀랜드산 연어, 신선 식품, 유제품 등의 신선품이라는 두 가지 뚜렷한 흐름에서 발생하고 있습니다. 스위스포트(Swissport)가 2026년 1월 히스로 공항에서 연간 3만 톤을 목표로 하는 2,694 m² 규모의 신선식품 전용 센터를 개설한 것은 사업자들이 범용 공간이 아닌 전문 시설에 자본을 투입하고 있음을 보여줍니다. 또한, 이 회사가 스캔 세계 로지스틱스(Scan Global Logistics)와 체결한 3년간의 제휴 역시, 제약이 많은 공항 내 인프라 투자를 정당화하기 위해서는 장기적인 고객과의 계약이 점점 더 필요해지고 있음을 보여줍니다.
히스로 공항의 터미널 네트워크는 여전히 대규모 적재, 하역, 환적 및 에어사이드 이동에 의존하고 있기 때문에 화물 취급은 영국 항공화물 부가 서비스 업계에서 여전히 두 번째로 큰 수익원입니다. 포장, 라벨 부착, 보험 및 혼적은 규모가 작은 부문이지만, 전자상거래로 인해 개별 발송 건수가 증가하고 소포 단위의 대응 수요가 높아짐에 따라 그 중요성이 커지고 있습니다. 통관 업무와 서류 관리도 브렉시트 이후의 ICS2 신고 규정에 따라 건당 청구 대상 서류량이 증가함에 따라 수익원으로서의 비중이 높아지고 있습니다. 2031년까지 콜드체인 처리와 규제 준수 보관 이력 관리, 그리고 능동적인 온도 관리를 결합할 수 있는 제공업체를 중심으로 서비스 성장이 지속될 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측(금액, 2026-2031년)
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.01According to Mordor Intelligence, the United Kingdom air freight ancillary services market size was valued at USD 3.91 billion in 2025 and estimated to grow from USD 4.21 billion in 2026 to reach USD 5.93 billion by 2031, at a CAGR of 7.12% during the forecast period (2026-2031).
The United Kingdom air freight ancillary services market is holding up well, supported by recovering cargo activity, limited capacity at major hubs, and stronger demand for value-added services like cold chain handling, rapid processing, and shipment visibility. This report is Segmented by Service Type (Cargo Handling, Consolidation, Packaging and Labeling, and More), by Shipment Type (Domestic and International), by Industry Vertical (Fashion and Luxury Goods, E-Commerce and Retail, Consumer Electronics, Food and Beverages, and More), and by Geography (England, Scotland, and More). The Market Forecasts are Provided in Terms of Value (USD).
Insights and Trends of United Kingdom Air Freight Ancillary Services
Rising Demand for Time-Critical Air Cargo Handling
United Kingdom air freight is moving further toward goods that cannot absorb delays, including advanced biologics, aerospace components, semiconductors, and just-in-time industrial inputs. Heathrow's cargo volumes rose to 1.5 million tons in 2025, while cargo trade handled by the airport reached GBP 293 billion (USD 375 billion), which shows that value growth is outpacing tonnage growth. Heathrow also reported record handling days in December 2025, indicating strong concentration during peak windows and supporting premium pricing for rapid transfers and priority acceptance services. This operating pattern favors handlers that can combine fast physical processing with dependable digital tracking and space allocation. As a result, the United Kingdom air freight ancillary services market is seeing stronger demand for services that protect speed, visibility, and compliance within a constrained airport estate.
Growth Of E-Commerce, Air Cargo And Cross-Border Parcel Flows
E-commerce places a heavier service burden on the United Kingdom air freight ancillary services market because each parcel generates customs, labeling, returns, and tracking work that often rises faster than tonnage. Glasgow Prestwick has become a visible example of this shift, with Chinese e-commerce carriers using the airport's 24/7, curfew-free operation and its scheduled links to mainland China to support parcel-heavy flows. The removal of the EU's EUR 150 (USD 174) de minimis customs duty exemption from July 1, 2026, adds more compliance work for United Kingdom-to-Europe parcel movements, which directly supports customs brokerage and documentation services. Express hubs and regional handlers also benefit because parcel flows need faster scanning, sortation, and exception management than traditional consolidated cargo. This keeps e-commerce as the strongest short-term demand driver across the United Kingdom air freight ancillary services market.
Slot Constraints And Limited Cargo Capacity At Key Airports
Heathrow is operating near full slot use, which creates a structural limit on how fast the United Kingdom air freight ancillary services market can add physical handling capacity. Heathrow's approved third runway is expected to raise cargo capacity by 50% and add 3 million tons of annual throughput. Still, the related infrastructure program means the benefit is unlikely to arrive before the mid-2030s. In the meantime, established operators are paying heavily for scarce airport space, as shown by WFS signing a 20-year lease for a new 11,000 m2 cargo facility at Heathrow. That space premium supports incumbent pricing power but also suppresses volume-led expansion, keeping entry barriers high for smaller service providers. This means near-term growth in the United Kingdom air freight ancillary services market depends more on value-added handling than on a broad rise in available throughput.
Other drivers and restraints analyzed in the detailed report include:
- Pharmaceutical And Temperature-Sensitive Cargo Compliance Requirements
- Airline And Airport Focus On Yield-Enhancing Ancillary Services
- Customs Complexity And Documentation Friction After Brexit
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Temperature-controlled services held 32.46% of the United Kingdom air freight ancillary services market share in 2025 and are forecast to expand at a CAGR of 8.49% through 2031, making cold chain the segment that most clearly shapes investment priorities and service differentiation. Demand comes from 2 distinct streams: pharmaceutical cargo that requires tightly controlled temperature ranges, and perishables such as Scottish salmon, fresh produce, and dairy products that require rapid air handling. Swissport's January 2026 launch of a 2,694 m2 dedicated perishables center at Heathrow, with an annual target of 30,000 tons, shows how operators are deploying capital into specialized facilities rather than generic space. Its linked 3-year partnership with Scan Global Logistics also shows that long-term customer commitments are increasingly needed to justify infrastructure spending at constrained airports.
Cargo handling remains the next-largest revenue stream in the United Kingdom air freight ancillary services industry because Heathrow's terminal network still relies on build-up, breakdown, transfer, and airside movement at scale. Packaging, labeling, insurance, and consolidation are smaller categories, but they are gaining importance as e-commerce creates more individual shipment events and raises the need for parcel-level intervention. Customs brokerage and documentation management are also becoming denser revenue streams because post-Brexit and ICS2 filing rules increase the amount of billable paperwork per shipment. Through 2031, service growth should continue to lean toward providers that can combine cold chain handling with compliant chain-of-custody and active temperature management.
Complete Report Scope:
- By Service Type
- Cargo Handling Services
- Cargo Consolidation Services
- Packaging and Labeling Services
- Cargo Insurance Services
- Temperature-Controlled (Cold Chain) Services
- Other Services
- By Shipment Type
- Domestic Shipments
- International Shipments
- By Industry Vertical
- Aerospace and Defense
- Consumer Electronics
- Automotive and Industrial Manufacturing
- E-commerce and Retail
- Healthcare and Technology
- Food and Beverage (Perishables)
- Chemicals and Hazardous Materials
- Fashion and Luxury Goods
- Others
- By Geography
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- DHL
- Kuehne + Nagel International AG
- Menzies Aviation
- Swissport International Ltd
- dnata
- DSV A/S
- CEVA Logistics (CMA CGM)
- Expeditors International of Washington, Inc.
- Hellmann Worldwide Logistics SE and Co. KG
- UPS
- FedEx
- JAS Worldwide
- GEODIS
- Chapman Freeborn Airchartering Ltd
- Air Charter Service Group Limited
- Ligentia UK Ltd
- Unsworth UK Ltd
- Woodland Group Ltd
- Cardinal Global Logistics Ltd
- Metro Shipping Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview and Role of Ancillary Services in Air Freight Economics
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Time-Critical Air Cargo Handling
- 4.2.2 Growth of E-Commerce Air Cargo and Cross-Border Parcel Flows
- 4.2.3 Pharmaceutical and Temperature-Sensitive Cargo Compliance Requirements
- 4.2.4 Airline and Airport Focus on Yield-Enhancing Ancillary Services
- 4.2.5 Expansion of Specialist Cold Chain Packaging and Chain-of-Custody Services
- 4.2.6 Heathrow-Centric Demand for Premium Handling and Expedited Turnaround
- 4.3 Market Restraints
- 4.3.1 Slot Constraints and Limited Cargo Capacity at Key Airports
- 4.3.2 High Labor and Compliance Costs for Security-Critical Handling
- 4.3.3 Customs Complexity and Documentation Friction After Brexit
- 4.3.4 Fragmented SME Demand Limits Automation Payback in Smaller Facilities
- 4.4 Regulatory Framework
- 4.5 Value Chain and Distribution Channel Architecture Analysis
- 4.6 Technology Innovations Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Rivalry Among Competitors
- 4.8 Evolution of the Air Freight Ancillary Services
- 4.9 Impact of Geo-Political Events on Supply Chain Shifts
5 Market Size & Growth Forecasts (Value, 2026-2031)
- 5.1 By Service Type
- 5.1.1 Cargo Handling Services
- 5.1.2 Cargo Consolidation Services
- 5.1.3 Packaging and Labeling Services
- 5.1.4 Cargo Insurance Services
- 5.1.5 Temperature-Controlled (Cold Chain) Services
- 5.1.6 Other Services
- 5.2 By Shipment Type
- 5.2.1 Domestic Shipments
- 5.2.2 International Shipments
- 5.3 By Industry Vertical
- 5.3.1 Aerospace and Defense
- 5.3.2 Consumer Electronics
- 5.3.3 Automotive and Industrial Manufacturing
- 5.3.4 E-commerce and Retail
- 5.3.5 Healthcare and Technology
- 5.3.6 Food and Beverage (Perishables)
- 5.3.7 Chemicals and Hazardous Materials
- 5.3.8 Fashion and Luxury Goods
- 5.3.9 Others
- 5.4 By Geography
- 5.4.1 England
- 5.4.2 Scotland
- 5.4.3 Wales
- 5.4.4 Northern Ireland
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 DHL
- 6.4.2 Kuehne + Nagel International AG
- 6.4.3 Menzies Aviation
- 6.4.4 Swissport International Ltd
- 6.4.5 dnata
- 6.4.6 DSV A/S
- 6.4.7 CEVA Logistics (CMA CGM)
- 6.4.8 Expeditors International of Washington, Inc.
- 6.4.9 Hellmann Worldwide Logistics SE and Co. KG
- 6.4.10 UPS
- 6.4.11 FedEx
- 6.4.12 JAS Worldwide
- 6.4.13 GEODIS
- 6.4.14 Chapman Freeborn Airchartering Ltd
- 6.4.15 Air Charter Service Group Limited
- 6.4.16 Ligentia UK Ltd
- 6.4.17 Unsworth UK Ltd
- 6.4.18 Woodland Group Ltd
- 6.4.19 Cardinal Global Logistics Ltd
- 6.4.20 Metro Shipping Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


