

|
시장보고서
상품코드
2117544
산업용 필터 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Industrial Filters - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
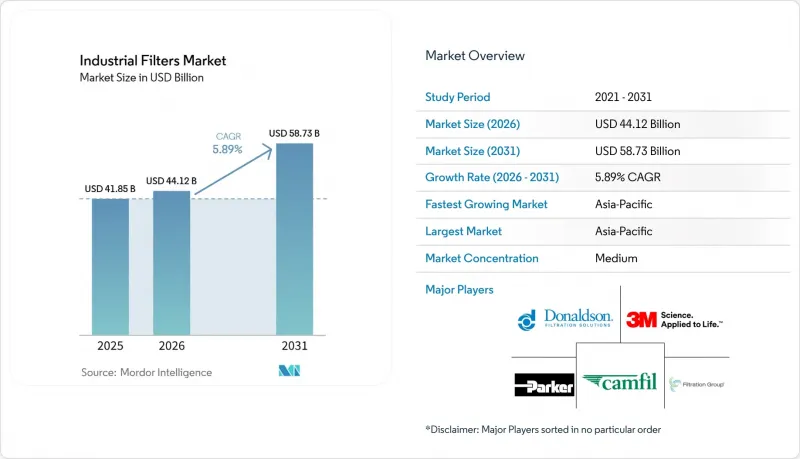
에 의하면, 산업용 필터 시장 규모는 2025년 418억 5,000만 달러로 평가되었습니다. 2026년 441억 2,000만 달러에서 2031년까지 587억 3,000만 달러로 확대되며 2026년부터 2031년에 걸쳐 CAGR 5.89%를 나타낼 전망입니다.
본 보고서는 유형(액체 여과, 공기 여과), 여과재(활성탄, 유리섬유 등), 최종 사용자 산업(화학제품 및 석유화학제품, 석유 및 가스, 식품 및 음료, 제약 등) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 산업용 필터 시장 동향 및 인사이트
산업용 수처리 및 공정 유체 여과에 대한 수요 증가
산업용 수처리는 단순한 규제 준수의 기능에서 직접적인 운영상의 우선 과제로 전환되고 있으며, 이는 산업용 필터 시장 전체 수요를 견인하고 있습니다. 인도, 중동, 중국 북부 등 물 부족에 시달리는 생산 지역에서는 공장이 폐수 재이용 및 재활용을 더욱 적극적으로 추진해야 하는 상황에 직면해 있습니다. 이러한 변화로 인해, 특히 석유화학, 섬유, 공정 제조 분야에서 기본적인 분리 방법보다 고성능의 액체 처리 시스템이 선호되고 있습니다. 또한, 재이용 루프 내에서 기존의 종이 또는 유리섬유 필터에서 멤브레인 및 활성탄 매체로 전환되는 추세도 가속화되고 있습니다. 식품 및 음료 부문 역시 청징, 미생물 제어, CIP(정지 세척) 공정을 통해 액체 여과 시스템의 높은 가동률이 유지되고 있어 안정적인 수요층을 형성하고 있습니다.
엄격한 환경 규제가 규정 준수를 위한 설비 투자를 촉진
배출 규제의 강화로 인해 산업용 필터 시장 전반에서 여과 시스템의 업그레이드가 필수적인 비용이 되고 있습니다. 유럽에서는 개정된 ‘산업 배출 지침’이 2024년 8월에 발효되었으며, 회원국은 2026년 7월 1일까지 이를 국내법에 반영해야 할 의무가 부과됨에 따라 광범위한 산업 시설에 대한 규제가 강화되었습니다. 또한 유럽집행위원회는 규정을 준수하지 않는 시설에 대해서는 연간 매출액에 따른 벌금이 부과될 가능성이 있다고 밝혔으며, 대응이 지연될 경우 사업자에게는 추가적인 비용 증가로 이어질 것입니다. 미국에서는 환경보호청(EPA)이 2025년에 철강 일괄 생산을 위한 ‘유해 대기 오염 물질에 관한 국가 배출 기준(NESHAP)’을 개정하고, 준수 기한을 2027년 4월까지 연장함에 따라 플랜트 계획에서 고도 여과 프로젝트가 계속해서 진행되고 있습니다. 이러한 규제 주기의 중첩으로 인해 서비스 업무도 증가하고 있습니다. 이는 많은 중규모 플랜트가 현재 시스템 설계 및 규정 준수 지원을 전문 업체에 의존하고 있기 때문입니다.
높은 설치·교체·유지보수 비용
비용은 산업용 필터 시장 전체에서 여전히 현실적인 장벽으로 작용하고 있으며, 특히 막대한 초기 투자를 정당화하기 어려운 소규모 플랜트의 경우 더욱 그렇습니다. 산업용 정수 시스템의 도입 비용은 2만 달러에서 25만 달러 이상에 달할 수 있으며, 설치 및 시운전 비용이 프로젝트 총비용을 크게 끌어올리고 있습니다. 의약품 등급 시스템의 경우, 교체용 카트리지나 막 또한 연간 운영 예산에서 상당한 비중을 차지합니다. 예산이 제한적인 경우, 사업자는 권장 수준을 초과하여 점검 및 정비 주기를 연장하는 경우가 많으며, 그 결과 오염 위험이 높아지고 가동 중단 시간이 길어질 수 있습니다. 이에 대응하여 주요 공급업체들은 모듈형 및 서비스 기반의 비즈니스 모델을 모색하고 있지만, 중견 기업 구매자들의 도입은 여전히 제한적입니다.
부문별 분석
2025년 시점에서 액체 여과는 산업용 필터 시장 점유율의 58.44%를 차지한 반면, 공기 여과는 2031년까지 연평균 성장률(CAGR) 6.47%를 나타낼 것으로 예측됩니다. 화학, 정제, 식품 가공, 제약 업계에서는 공정 유체의 지속적인 관리가 요구되기 때문에 액체 여과 시스템이 더 큰 수익 기반을 유지하고 있습니다. 도입 기반이 넓기 때문에 신규 프로젝트의 시기가 불규칙하더라도 꾸준한 교체 수요가 뒷받침되고 있습니다. 산업용 필터 시장은 규모 면에서는 여전히 액체 여과에 의존하고 있지만, 단기적인 성장에서는 공기 여과가 더 큰 비중을 차지하고 있습니다.
플랜트 운영자들이 작업자의 노출 한도, 분진 포집 및 청정한 제조 환경에 관한 더욱 엄격한 요구 사항에 직면함에 따라 공기 여과의 성장세가 가속화되고 있습니다. 산업용 필터 시장의 이 부문은 중소규모 산업 구매자들 사이에서 더욱 세분화되어 있으며, 이는 공급업체에게 더 견고한 단위 수익성을 뒷받침하고 있습니다. 2026년 캠필(Camfil)의 말레이시아 사업 확장은 아시아의 공기 여과 수요가 여전히 충분히 견조하여 현지 생산 능력 확충을 정당화할 수 있다는 확신을 반영합니다. 액체 필터 분야에서는 이튼(Eaton)이 2025년에 ‘BECO Helix’ 심층 필터 카트리지를 출시하여 입자 포집 능력을 향상시키고 수명을 연장했습니다. 이는 규모가 더 크고 성숙한 이 부문에서도 혁신이 활발히 이어지고 있음을 보여줍니다.
지역별 분석
아시아태평양은 2025년에 산업용 필터 시장 점유율의 39.84%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.73%로 성장할 것으로 전망됩니다. 중국은 2025년 전 세계 매출의 24%를 차지하고 있으며, 석유화학,반도체, 식품 가공 분야의 설비 갱신이 이를 뒷받침하고 있습니다. 인도는 제2의 성장 동력으로 부상하고 있으며, 하이데라바드와 아메다바드의 제약 허브가 수출 지향적인 규정 준수 요건에 부합하는 막 시스템 수요를 견인하고 있습니다. MANN+HUMMEL사는 2026년 5월,카르나타카주에 독일 해외 최대 규모의 개발 센터를 개설할 예정이며, 총 투자액은 100카롤 루피(1,200만 달러)를 넘어설 것으로 예상되어, 향후 공급 및 제품 개발에서 이 지역의 전략적 역할을 부각시키고 있습니다.
한국과 일본은 반도체 클린룸용 여과 및 정밀 산업용 유체 관리를 통해 이 지역 시장 기반 심화에 기여하고 있습니다. 동남아시아에서도 식품 가공 및 석유화학 생산 능력이 지속적으로 확대됨에 따라 수요 기반이 확대되고 있습니다. 이러한 동향으로 인해 아시아태평양에서는 막대한 산업 수요와 고사양 용도가 공존하고 있으며, 현지 생산 및 수입된 프리미엄 시스템 모두에서 사업 활동이 지속될 것으로 전망됩니다.
북미는 2025년에 지역별 2위 규모를 유지했습니다. 이는 정유, 화학, 식품 가공 분야의 노후화된 설비 기반에 기인한 지속적인 갱신 수요에 힘입은 결과입니다. 도널드슨사는 2025 회계연도에 새로운 집진 설비 및 발전 프로젝트 수주를 통해 시장 평균을 상회하는 실적을 보고했으며, 이는 산업용 공기 처리 분야 수요가 견조함을 보여줍니다. 유럽에서는 개정된 ‘산업 배출 지침’이 2026년 7월까지 국내법에 반영되어야 하는 시한을 앞두고, 이전 규제 주기 하에서 미뤄졌던 플랜트 개보수 결정이 가속화되고 있습니다. 독일, 영국, 프랑스는 화학, 제약, 에너지, 식품 제조 각 분야에서 계속해서 고성능 여과 기술이 요구되고 있어 중요한 수요 거점으로 남아 있습니다.
남미는 브라질의 석유 및 가스 및 식품 가공 부문을 필두로, 아르헨티나도 화학 및 광업을 통해 수요를 견인하고 있어 여전히 성장 기회를 내포하고 있습니다. 중동 및 아프리카에서는 정유시설 가동, 해수 담수화 인프라, 광업 활동, 그리고 확대되는 의약품 제조가 장기적인 지역 수요를 뒷받침하고 있습니다. 사우디아라비아와 남아프리카공화국은 수처리 및 산업 공정 수요가 장기적인 여과 관련 지출에서 중요한 역할을 하는 주목할 만한 시장입니다. 이 지역들은 현재 시장 점유율은 작지만, 더 광범위한 산업용 필터 시장을 뒷받침하는 인프라 구축 계획 및 수출 지향형 산업 투자와 밀접하게 연관되어 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.02According to Mordor Intelligence, the industrial filters market size is projected to expand from USD 41.85 billion in 2025 and USD 44.12 billion in 2026 to USD 58.73 billion by 2031, and is expected to register a CAGR of 5.89% between 2026 to 2031.
This report is Segmented by Type (Liquid Filtration, Air Filtration), Filter Media (Activated Carbon, Fiber Glass, and More), End-User Industry (Chemicals & Petrochemicals, Oil & Gas, Food & Beverage, Pharmaceuticals, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Filters Market Trends and Insights
Increasing Demand for Industrial Water Treatment and Process Fluid Filtration
Industrial water treatment is shifting from a compliance function to a direct operating priority, driving demand across the industrial filters market. Water-stressed production zones in India, the Middle East, and northern China are pushing plants to recycle and reclaim wastewater more aggressively. This shift favors higher-performance liquid systems over basic separation methods, particularly in petrochemicals, textiles, and process manufacturing. It also supports a transition from conventional paper and fiberglass options to membrane and activated carbon media within reuse loops. The food and beverage sector adds another stable layer of demand, as clarification, microbial control, and clean-in-place processes keep liquid filtration systems operating at high utilization rates.
Stringent Environmental Regulations Driving Compliance Capital Expenditure
Stricter emissions rules are making filtration upgrades a required expense across the industrial filters market. The revised Industrial Emissions Directive in Europe entered into force in August 2024, and member states were required to transpose it by July 1, 2026, tightening obligations for a wide range of industrial facilities. The European Commission also stated that non-compliant installations can face penalties tied to annual turnover, making delays more costly for operators. In the United States, the EPA revised National Emission Standards for Hazardous Air Pollutants (NESHAP) rules for integrated iron and steel manufacturing in 2025 and extended the compliance timeline to April 2027, keeping advanced filtration projects active in plant planning. These overlapping regulatory cycles are also generating more service work, as many mid-sized plants now rely on specialist firms for system design and compliance support.
High Installation, Replacement, and Maintenance Costs
Cost remains a practical barrier across the industrial filters market, especially for smaller plants that struggle to justify large upfront expenditures. Industrial water filtration installations can range from USD 20,000 to more than USD 250,000, with installation and commissioning adding significantly to total project costs. In pharmaceutical-grade systems, replacement cartridges and membranes also account for a notable share of annual operating budgets. When budgets are constrained, operators often extend service intervals beyond recommended levels, which increases contamination risk and can lead to greater downtime. Larger suppliers are exploring modular and service-based models in response, but adoption among mid-market buyers remains limited.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Air Quality Management in Industrial Settings
- Growing Adoption of Smart and Internet of Things (IoT)-Enabled Filtration Systems
- Filter Fouling and Performance Degradation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Liquid filtration held 58.44% of the industrial filters market share in 2025, while air filtration is projected to grow at a 6.47% CAGR through 2031. Liquid systems retained the larger revenue base because chemicals, refining, food processing, and pharmaceuticals require continuous process-fluid management. The large installed base supports steady replacement demand even when new project timing is uneven. The industrial filters market continues to depend on liquid filtration for scale, while air filtration is contributing a larger share of near-term growth.
Air filtration is gaining ground as plant operators face stricter requirements for worker exposure limits, dust capture, and clean manufacturing conditions. This segment of the industrial filters market is also more fragmented among small- and medium-sized industrial buyers, which supports firmer unit economics for suppliers. Camfil's expansion in Malaysia in 2026 reflects confidence that Asian air filtration demand will remain strong enough to justify additional local capacity. On the liquid side, Eaton introduced BECO Helix depth filter cartridges in 2025 to increase particle-holding capacity and extend service life, demonstrating that innovation remains active in the larger, more mature segment.
Complete Report Scope:
- By Type
- Liquid Filtration
- Air Filtration
- By Filter Media
- Activated Carbon
- Fiber Glass
- Filter Paper
- Metal
- Non-Woven Fabric
- Membrane
- Other Filter Media
- By End-user Industry
- Food and Beverage
- Chemicals and Petrochemicals
- Power Generation
- Oil and Gas
- Pharmaceuticals
- Metal and Mining
- Automotive
- Other End-use Industry
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 39.84% of the industrial filters market share in 2025 and is projected to grow at a 6.73% CAGR through 2031. China accounted for 24% of global revenue in 2025, supported by upgrades in petrochemicals, semiconductors, and food processing. India is emerging as a second growth engine, with pharmaceutical hubs in Hyderabad and Ahmedabad driving demand for membrane systems aligned with export-oriented compliance requirements. MANN+HUMMEL opened its largest development center outside Germany in Karnataka in May 2026, with combined investments expected to exceed INR 100 crores (USD 12 million), underscoring the region's strategic role in future supply and product development.
South Korea and Japan contribute to regional depth through semiconductor cleanroom filtration and precision industrial fluid management. Southeast Asia is also expanding its demand base as food processing and petrochemical capacity continue to grow. These trends give Asia-Pacific a mix of large-volume industrial demand and high-specification applications, which should sustain activity across both local production and imported premium systems.
North America held the second-largest regional position in 2025, supported by recurring replacement activity driven by an aging installed base in refining, chemicals, and food processing. Donaldson reported above-market performance in fiscal 2025 from new dust-collection equipment and power-generation project wins, indicating healthy demand in industrial air applications. In Europe, the July 2026 transposition deadline for the revised Industrial Emissions Directive is accelerating plant upgrade decisions that had been deferred under the prior regulatory cycle. Germany, the United Kingdom, and France remain important demand centers, as chemicals, pharmaceuticals, energy, and food manufacturing continue to require high-performance filtration.
South America remains a developing opportunity, led by Brazil's oil and gas and food processing sectors, with Argentina contributing volume through chemicals and mining. In the Middle East and Africa, refinery operations, desalination infrastructure, mining activity, and growing pharmaceutical manufacturing are supporting longer-term regional demand. Saudi Arabia and South Africa are notable markets where water treatment and industrial processing needs are material to long-term filtration spending. While these regions represent smaller shares today, they remain connected to infrastructure programs and export-oriented industrial investment that support the broader industrial filters market.
- 3M
- AAF International
- Ahlstrom-Munksjo
- Air Filters Inc.
- BWF Envirotec GmbH
- Camfil
- Clarcor Inc.
- Donaldson Company Inc.
- Eaton Corporation
- Filtra-Systems Company LLC
- Filtration Group
- GRAVER Technologies
- Huber Technology GmbH
- Hydac International GmbH
- Industrial Filter and Pump Mfg. Co.
- Lydall, Inc.
- Mann+Hummel
- Nanjing Kairui Filter Co. Ltd.
- PARKER HANNIFIN CORP
- Sefar AG
- WAMGROUP S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand for High-Purity Filtration Across Process Industries
- 4.2.2 Stringent Environmental and Industrial Emission Regulations Driving Filtration Adoption
- 4.2.3 Growing Demand for Advanced Filtration Solutions in Pharmaceutical and Biotechnology Manufacturing
- 4.2.4 Increasing Modernization of Industrial Facilities with Energy-Efficient Filtration Technologies
- 4.2.5 Growing Adoption of Smart Filtration Systems and Predictive Maintenance Technologies
- 4.3 Market Restraints
- 4.3.1 High Installation, Replacement, and Maintenance Costs of Advanced Filtration Systems
- 4.3.2 Filter Fouling and Performance Degradation Leading to Operational Downtime
- 4.3.3 Volatility in the Supply and Cost of Specialized Filtration Materials
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Liquid Filtration
- 5.1.2 Air Filtration
- 5.2 By Filter Media
- 5.2.1 Activated Carbon
- 5.2.2 Fiber Glass
- 5.2.3 Filter Paper
- 5.2.4 Metal
- 5.2.5 Non-Woven Fabric
- 5.2.6 Membrane
- 5.2.7 Other Filter Media
- 5.3 By End-user Industry
- 5.3.1 Food and Beverage
- 5.3.2 Chemicals and Petrochemicals
- 5.3.3 Power Generation
- 5.3.4 Oil and Gas
- 5.3.5 Pharmaceuticals
- 5.3.6 Metal and Mining
- 5.3.7 Automotive
- 5.3.8 Other End-use Industry
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 AAF International
- 6.4.3 Ahlstrom-Munksjo
- 6.4.4 Air Filters Inc.
- 6.4.5 BWF Envirotec GmbH
- 6.4.6 Camfil
- 6.4.7 Clarcor Inc.
- 6.4.8 Donaldson Company Inc.
- 6.4.9 Eaton Corporation
- 6.4.10 Filtra-Systems Company LLC
- 6.4.11 Filtration Group
- 6.4.12 GRAVER Technologies
- 6.4.13 Huber Technology GmbH
- 6.4.14 Hydac International GmbH
- 6.4.15 Industrial Filter and Pump Mfg. Co.
- 6.4.16 Lydall, Inc.
- 6.4.17 Mann+Hummel
- 6.4.18 Nanjing Kairui Filter Co. Ltd.
- 6.4.19 PARKER HANNIFIN CORP
- 6.4.20 Sefar AG
- 6.4.21 WAMGROUP S.p.A.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


