

|
시장보고서
상품코드
2117984
동아프리카의 사료용 종자 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)East Africa Forage Seed - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
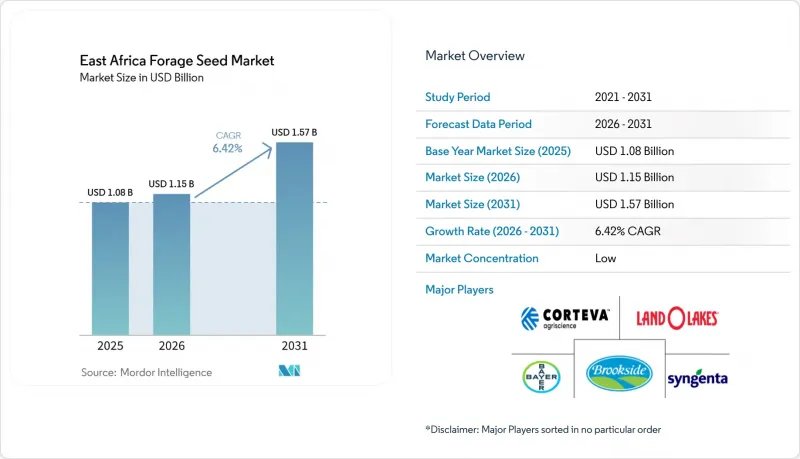
에 의하면, 동아프리카의 사료용 종자 시장 규모는 2025년 10억 8,000만 달러로 평가되었습니다. 2026년에는 11억 5,000만 달러로 확대되어 2031년까지 15억 7,000만 달러에 이를 것으로 예측되며, 2026-2031년에 걸쳐 CAGR 6.42%로 성장할 전망입니다.
본 보고서는 육종 기술별(하이브리드, 개방 수분 품종 및 하이브리드 파생 품종), 작물 유형별(알팔파, 사료용 옥수수, 사료용 수수, 기타 사료 작물), 그리고 지역별(케냐, 에티오피아, 탄자니아,우간다, 동아프리카의 기타 지역)으로 분류되어 있습니다. 시장 예측은 금액(달러)과 수량(톤)으로 제시되어 있습니다.
동아프리카의 사료용 종자 시장 동향 및 인사이트
케냐와 에티오피아의 유우용 사료 부족 심화
동아프리카의 사료용 종자 시장은 축산 시스템이 여전히 심각한 구조적 사료 부족에 직면해 있어 성장을 이어가고 있습니다. 국제가축연구소(ILRI)(2024년)에 따르면, 이 지역의 연간 사료 수요는 건조물 기준으로 3억 5,300만 톤에 달하는 반면, 현재 공급량은 이 수요의 불과 60%만을 충당하고 있습니다. 에티오피아에서는 재배되는 사료의 부족량이 매년 880만 톤(건물 기준)을 초과하며, 사료 종자 시스템은 여전히 취약한 상태입니다. 종자의 약 70%가 여전히 비공식 유통 경로를 통해 거래되고 있습니다. 이러한 격차로 인해 사료 수요는 임의적인 지출이 아니라 실질적인 운영상의 필요와 연결되어 있으며, 이는 동아프리카 사료 종자 시장에 견고한 기반을 마련해 주고 있습니다. 또한 이러한 부족 상황은 제한된 토지에서 더 많은 바이오매스와 더 안정적인 사료 생산량을 가져다주는 품종의 가치를 높이고 있습니다.
기후 변화에 강한 사료용 종자 시스템의 확대
기후 변화로 인해 농가와 종자 공급업체는 수분 스트레스, 토지 이용 압력, 예측하기 어려운 생육 조건을 견딜 수 있는 품종을 선호하게 되었습니다. 동아프리카의 사료 종자 시장은 혼합 경작법에 적합하고, 밭에서 스트레스를 받는 상황에서도 보다 안정적인 생산성을 발휘할 수 있는 개량된 벼과 및 콩과 식물에 대한 관심이 높아짐에 따라 이러한 변화에 대응하고 있습니다. 우간다와 사하라 이남 아프리카 전역에 걸친 개량 사료작물 조사 결과에서도, 기후 변화에 강한 사료작물 선택지가 적절한 보급 지원 및 시장 지원과 연계될 경우, 사료의 안정적 공급과 가축 생산성이 향상된다는 사실이 밝혀졌습니다. 이는 동아프리카의 사료 종자 시장이 종자 판매 증가뿐만 아니라, 생산 위험을 줄여주는 품종 및 형태로의 점진적인 전환을 통해 확대되고 있음을 의미합니다. 장기적으로는 이를 통해 도입의 일관성이 향상되어, 공급업체가 현지에서의 증산 및 유통에 대한 투자를 정당화할 수 있게 됩니다.
개량 사료작물의 높은 종자비 및 식재 비용
높은 종자 비용은 도입 가속화를 저해하는 가장 두드러진 장벽 중 하나로 남아 있습니다. 케냐에서는 우로크로아의 종자 가격이 1kg당 40-50달러로 보고되고 있는 반면, 남미 공급 시장에서는 1kg당 15-30달러인 점을 고려할 때, 현지에서의 증식이 여전히 제한적이라는 사실이 동아프리카의 사료용 종자 시장의 비용 상승 요인으로 작용하고 있음을 알 수 있습니다. 이와 유사한 압박은 농가의 행동에서도 나타나고 있으며, 멜 현에서 개량 사료 품종에 대한 구매 의향은 대부분의 제품에서 시장 가격보다 낮은 수준을 유지했습니다. 또한 케냐에서는 종자 생산 비용도 급등하고 있어, 2025년 3월 파종 시즌을 앞두고 종자 생산용 구획의 토지 비용이 1에이커당 4,000 케냐 실링(26달러)에서 2만 케냐실링(130달러)로 상승했습니다. 이러한 비용 부담은 소규모 농가 시스템에서 도입을 가장 크게 저해하고 있습니다. 이러한 시스템에서는 개량된 사료 작물의 농업적 이점이 크더라도, 초기 현금 부담을 감당하기는 여전히 어렵기 때문입니다.
부문별 분석
2025년, 하이브리드 종자는 동아프리카의 사료용 종자 시장에서 46%의 점유율을 차지하며 국가별 부문에서 가장 큰 점유율을 유지했습니다. 이러한 우위는 상업용 옥수수 사일리지 시스템에서의 적극적인 활용과 케냐 및 에티오피아 내 주요 종자 공급업체의 확고한 유통망 덕분입니다. 또한, 하이브리드 종자는 더 높은 바이오매스 생산량, 뛰어난 병해 저항성, 더 예측 가능한 밭에서의 생육 성적을 추구하는 낙농장 및 상업용 사일리지 사업자의 요구에도 부응하고 있습니다. 동아프리카 사료 산업에서 이러한 특성이 중요시되는 이유는 사료 비용이 종자 가격뿐만 아니라 가축 생산량과 비교하여 평가되기 때문입니다. 따라서 하이브리드 품종은 종자 재사용보다 안정적인 수확량이 중시되는 고부가가치 낙농 지역에서 계속해서 유리한 입지를 유지하고 있습니다.
개방 수분 품종과 하이브리드 파생 품종은 2026년부터 2031년까지 연평균 성장률(CAGR) 7.6%를 기록하며 가장 빠르게 성장하는 부문입니다. 이러한 성장은 낮은 단위 비용, 번식 용이성, 여전히 지역 축산업을 지배하고 있는 소규모 농가 시스템과의 높은 친화성에 기인합니다. 2024년, 국제농업연구협의그룹(CGIAR) 보고서에 따르면, 케냐에서 우로클로아(Urochloa)와 메가티르수스 막시무스(Megathyrsus maximus)는 가장 널리 거래되는 개량 사료 품종 중 하나이며, 향후 10년 동안도 중요한 지위를 유지할 것으로 예측됩니다. 따라서 동아프리카의 사료 종자 시장은 하이브리드 품종이 상업적 판매량을 뒷받침하는 한편, 개방 수분 품종이 보급 범위를 확대하는 이 두 가지 축을 따라 동시에 발전하고 있습니다. 이러한 균형이 중요한 이유는 동아프리카 사료 종자 시장의 광범위한 보급이 고수확 부문와 현지 증식 시스템을 통해 유통 가능한 저렴한 가격의 종자 형태 모두에 의존하기 때문입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 본 보고서의 내용
제3장 개요 및 주요 조사 결과
제4장 주요 산업 동향
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 CEO를 위한 중요한 전략적 과제
KTH 26.09.02According to Mordor Intelligence, the East Africa forage seed market size is projected to increase from USD 1.08 billion in 2025 to USD 1.15 billion in 2026 and reach USD 1.57 billion by 2031, growing at a CAGR of 6.42% over 2026-2031.
This report is Segmented by Breeding Technology (Hybrids and Open Pollinated Varieties and Hybrid Derivatives), by Crop Type (Alfalfa, Forage Corn, Forage Sorghum, and Other Forage Crops), and by Geography (Kenya, Ethiopia, Tanzania, Uganda, and the Rest of East Africa). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Metric Tons).
East Africa Forage Seed Market Trends and Insights
Rising Dairy Feed Deficit in Kenya and Ethiopia
The East Africa forage seed market continues to grow because livestock systems still face a major structural feed shortage. According to the International Livestock Research Institute (ILRI) (2024), the regional annual feed demand reaches 353 million metric tons of dry matter, while current supply covers only 60% of this demand. In Ethiopia, cultivated forage deficit exceeds 8.8 million metric tons of dry matter each year, and the forage seed system remains weak, with nearly 70% of seeds still moving through informal channels. This gap keeps forage demand tied to a real operating need rather than discretionary spending, which gives the East Africa forage seed market a durable base. The same shortage also raises the value of varieties that can deliver more biomass and more stable feed output from limited land.
Expansion of Climate-Resilient Forage Seed Systems
Climate variability is pushing farmers and seed suppliers to favor varieties that can withstand moisture stress, land pressure, and less-predictable growing conditions. The East Africa forage seed market is responding through greater interest in improved grasses and legumes that fit mixed farming systems and can perform more reliably under field stress. Research on improved forages in Uganda and broader Sub-Saharan Africa also shows that feed security and livestock productivity improve when resilient forage options are matched with the right extension and market support. This means the East Africa forage seed market is expanding not only through more seed sales but also through a gradual shift toward species and formats that reduce production risk. Over time, that improves adoption consistency and helps suppliers justify local multiplication and distribution investments.
High Seed and Establishment Costs for Improved Forages
High seed cost remains one of the clearest barriers to faster adoption. In Kenya, Urochloa seed prices were reported at USD 40 to USD 50 per kg, compared with USD 15 to USD 30 per kg in South American supplier markets, which shows how limited local multiplication still raises costs in the East Africa forage seed market. The same pressure is visible in farmer behavior, since willingness to pay for improved forage varieties in Meru County remained below market prices for most products. Seed production costs also rose sharply in Kenya, with land cost for seed production plots moving from KES 4,000 (USD 26) to KES 20,000 (USD 130) per acre before the March 2025 planting season. This cost burden slows adoption most in smallholder systems, where the agronomic case for improved forage may be strong, but the upfront cash requirement remains difficult to absorb.
Other drivers and restraints analyzed in the detailed report include:
- Commercial Silage and Fodder Contracting Models
- Public and Donor De-Risking of Early Market Development
- Fragmented Seed Quality Assurance and Variety Registration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hybrids held the largest country segment, with a 46% share of the East Africa forage seed market in 2025. Their lead came from strong use in commercial maize silage systems and from the established distribution presence of large seed suppliers in Kenya and Ethiopia. Hybrids also meet the needs of dairy farms and commercial silage operators seeking higher biomass output, better disease tolerance, and more predictable field performance. In the East Africa forage industry, these traits matter because feed costs are judged against livestock output, not only seed price. That keeps hybrids well-positioned in higher-value dairy corridors, where consistent yield matters more than seed recycling.
Open Pollinated Varieties and Hybrid Derivatives are the fastest segment with a 7.6% CAGR from 2026 to 2031. Their growth is tied to lower unit cost, easier multiplication, and a better fit with smallholder systems that still dominate regional livestock production. In 2024, a Consultative Group on International Agricultural Research (CGIAR) publication found that Urochloa and Megathyrsus maximus are among the most widely traded improved forage varieties in Kenya and are projected to remain important over the next decade. The East Africa forage seed market is therefore developing along 2 lines at once, with hybrids anchoring commercial volume and open-pollinated options expanding reach. That balance matters because broad adoption in the East Africa forage seed market will depend on both premium yield segments and affordable seed formats that can move through local multiplication systems.
Complete Report Scope:
- Breeding Technology
- Hybrids
- Non-Transgenic Hybrids
- Transgenic Hybrids
- Herbicide Tolerant Hybrids
- Other Traits
- Open Pollinated Varieties and Hybrid Derivatives
- Hybrids
- Crop Type
- Alfalfa
- Forage Corn
- Forage Sorghum
- Other Forage Crops
- By Country
- Kenya
- Ethiopia
- Tanzania
- Uganda
- Rest of East Africa
List of Companies Covered in this Report:
- Advanta Seeds (UPL Ltd.)
- Bayer AG
- Land O'Lakes Inc.
- East African Seed Company Limited
- Groupe Limagrain
- Seed Co International Limited
- Brookside Dairy Limited (Brookside Holdings)
- Gatiko Company Ltd (Gatiko Company Ltd)
- Corteva Inc.
- Syngenta Limited
- Kenya Nut Company Limited
- New Kenya Co-operative Creameries Limited
- Balton CP Limited
- Shayashone PLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
- 1.3 Research Methodology
2 REPORT OFFERS
3 EXECUTIVE SUMMARY AND KEY FINDINGS
4 KEY INDUSTRY TRENDS
- 4.1 Area Under Cultivation
- 4.1.1 Row Crops
- 4.2 Most Popular Traits
- 4.2.1 Alfalfa
- 4.3 Breeding Techniques
- 4.3.1 Row Crops
- 4.4 Regulatory Framework
- 4.5 Value Chain And Distribution Channel Analysis
- 4.6 Market Drivers
- 4.6.1 Rising dairy feed deficit in Kenya and Ethiopia
- 4.6.2 Expansion of climate-resilient forage seed systems
- 4.6.3 Commercial silage and fodder contracting models
- 4.6.4 Public and donor de-risking of early market development
- 4.6.5 Premiumization of certified forage for dairy and feed mills
- 4.6.6 Cross-border fodder trade from surplus highland zones
- 4.7 Market Restraints
- 4.7.1 High seed and establishment costs for improved forages
- 4.7.2 Fragmented seed quality assurance and variety registration
- 4.7.3 Land and water constraints in high-potential dairy corridors
- 4.7.4 Dry-season logistics losses and weak cold or covered storage
5 MARKET SIZE AND GROWTH FORECAST (VALUE AND VOLUME)
- 5.1 Breeding Technology
- 5.1.1 Hybrids
- 5.1.1.1 Non-Transgenic Hybrids
- 5.1.1.2 Transgenic Hybrids
- 5.1.1.2.1 Herbicide Tolerant Hybrids
- 5.1.1.3 Other Traits
- 5.1.2 Open Pollinated Varieties and Hybrid Derivatives
- 5.1.1 Hybrids
- 5.2 Crop Type
- 5.2.1 Alfalfa
- 5.2.2 Forage Corn
- 5.2.3 Forage Sorghum
- 5.2.4 Other Forage Crops
- 5.3 By Country
- 5.3.1 Kenya
- 5.3.2 Ethiopia
- 5.3.3 Tanzania
- 5.3.4 Uganda
- 5.3.5 Rest of East Africa
6 COMPETITIVE LANDSCAPE
- 6.1 Key Strategic Moves
- 6.2 Market Share Analysis
- 6.3 Company Landscape
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Business Segments, Financials, Key Information, Market Rank, Market Share, Products and Services, and Analysis of Recent Developments).
- 6.4.1 Advanta Seeds (UPL Ltd.)
- 6.4.2 Bayer AG
- 6.4.3 Land O'Lakes Inc.
- 6.4.4 East African Seed Company Limited
- 6.4.5 Groupe Limagrain
- 6.4.6 Seed Co International Limited
- 6.4.7 Brookside Dairy Limited (Brookside Holdings)
- 6.4.8 Gatiko Company Ltd (Gatiko Company Ltd)
- 6.4.9 Corteva Inc.
- 6.4.10 Syngenta Limited
- 6.4.11 Kenya Nut Company Limited
- 6.4.12 New Kenya Co-operative Creameries Limited
- 6.4.13 Balton CP Limited
- 6.4.14 Shayashone PLC


