

|
시장보고서
상품코드
2118107
모바일 DevOps 플랫폼 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Mobile DevOps Platform - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
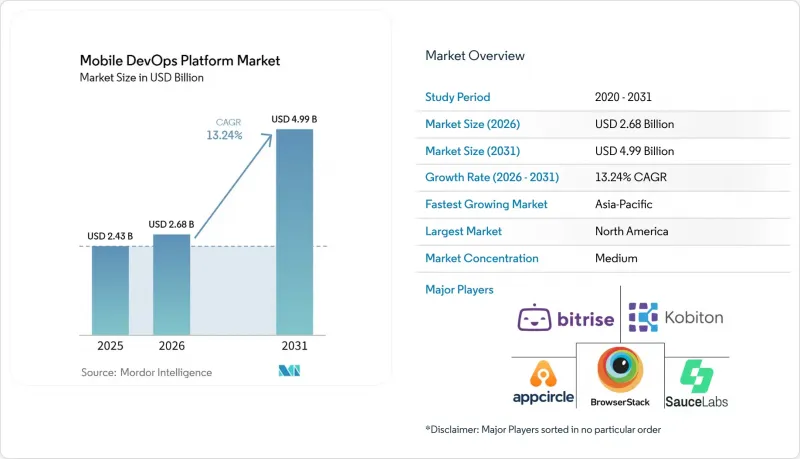
에 의하면, 모바일 DevOps 플랫폼 시장 규모는 2025년에 24억 3,000만 달러로 평가되었고 2026년 26억 8,000만 달러에서 2031년까지 49억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 13.24%를 나타낼 전망입니다.
본 보고서는 구성 요소(소프트웨어 및 서비스), 도입 모델(클라우드, 하이브리드, On-Premise), 기업 규모(대기업 및 중소기업), 개발 프레임워크(네이티브 iOS 개발, 네이티브 Android 개발 등), 최종 사용자(IT 및 통신, BFSI 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 모바일 DevOps 플랫폼 시장 동향 및 인사이트
지속적 배포 및 자동화된 모바일 릴리스 파이프라인에 대한 수요 증가
모바일 DevOps 플랫폼 시장은 소비자 대상 기업들이 모바일 업데이트를 몇 주가 아닌 몇 시간 내에 출시하려고 노력하고 있다는 점에서 혜택을 받고 있습니다. 2025년 JetBrains가 805명의 소프트웨어 전문가를 대상으로 실시한 설문조사에 따르면, 41%의 조직이 GitHub Actions를 통해 배포를 수행하는 반면, Jenkins는 플러그인 생태계 덕분에 대기업에서 여전히 널리 사용되고 있습니다. 많은 기업에서는 클라우드 기반 CI/CD 도구 외에도 여전히 레거시 빌드 서버를 운영하고 있으며, 이는 유지보수 작업 증가와 릴리스 관리의 복잡화를 초래하고 있습니다. 이로 인해 완전한 마이그레이션이 필요하지 않고 기존 오케스트레이터와 연동할 수 있는 플랫폼에 대한 수요가 높아지고 있습니다. 단일 제어 계층을 통해 전체 배포 프로세스를 지원하는 모바일 DevOps 플랫폼 제공업체는 이러한 요구를 충족시킬 수 있습니다. 앱의 신속한 업데이트에 대한 기대가 높아짐에 따라, 조달 팀과 엔지니어링 팀은 릴리스 워크플로우 현대화를 위한 더 큰 압박을 받고 있습니다.
자율적인 파이프라인 관리를 가능하게 하는 AI 및 ML 통합
AI를 활용한 워크플로는 코드 제안에서 자동 테스트, 장애 검증, 시정 조치, 배포 관리에 이르기까지 점차 확대되고 있습니다. Harness는 2026년 6월 ‘Autonomous Worker Agents’를 도입했습니다. 여기에는 Open Policy Agent를 통한 제어 및 파이프라인 액션에 대한 감사 추적과 같은 거버넌스 기능이 포함되어 있습니다. Bitrise의 보고서에 따르면, AI 지원 빌드는 1년 동안 164배 증가한 반면, 팀이 사용자에게 릴리스하는 빈도는 20% 감소했습니다. 이러한 격차는 전달 시스템이 코드 생성의 확대를 따라가지 못할 경우, 테스트 및 릴리스 프로세스에 대한 부담이 증가할 수 있음을 보여줍니다. AI 코딩 도구와 연동되어 리뷰 기록을 보관하는 플랫폼은 엔터프라이즈 고객을 대상으로 더 견고한 입지를 구축할 가능성이 높습니다. 따라서 모바일 DevOps 플랫폼 시장에서는 단순한 관리형 빌드 용량뿐만 아니라 거버넌스 기능의 중요성이 점점 더 커지고 있습니다.
레거시 IT 인프라 통합의 복잡성과 마이그레이션에 수반되는 막대한 오버헤드
수많은 맞춤형 플러그인을 사용하는 Jenkins 파이프라인을 도입한 기업에게 있어 마이그레이션 비용은 여전히 큰 장벽으로 남아 있습니다. 2025년 JetBrains의 조사에 따르면, 32%의 조직이 2개의 CI/CD 도구를 사용하고 있으며, 9%는 3개 이상의 도구를 사용하고 있는 것으로 나타났습니다. 이러한 혼합 환경에서는 플랫폼의 완전한 통합이 장기간 지연될 가능성이 있습니다. 프로비저닝 프로파일, 키 스토어, App Store Connect의 인증 정보를 포함하는 모바일 서명 시스템은 현재의 파이프라인 설정과 밀접하게 연결되어 있습니다. 이러한 프로세스를 재구축하려면 빌드 단계 자체를 마이그레이션하는 것보다 더 많은 작업이 필요할 수 있습니다. ISO/IEC 27001 요구사항 역시 마이그레이션 기간 동안 감사 기록을 유지해야 하므로, 추가적인 복잡성을 초래할 수 있습니다. 따라서 모바일 DevOps 플랫폼 시장은 마이그레이션 계획과 제품 기능 모두를 고려해야 합니다.
부문 분석
2025년, 소프트웨어는 모바일 DevOps 플랫폼 시장 점유율의 72.41%를 차지하며, 이는 기업 내 구독형 CI/CD 플랫폼의 활용을 반영합니다. 2019년부터 2025년까지 조직들은 자체 관리형 빌드 서버에서 소프트웨어 플랫폼으로 전환했습니다. 소프트웨어 카테고리에서는 팀이 공통 운영 환경을 통해 빌드, 테스트, 릴리스, 보안 검토, 워크플로 승인 각 기능에 모듈식으로 접근할 수 있습니다. 또한 라이선스 기반 구매도 지원하므로, 조직은 프로젝트별 서비스 계약 대신 사용자 수, 프로젝트 요구 사항 및 지속적인 소프트웨어 예산에 맞추어 플랫폼 접근 권한을 조정할 수 있습니다. 이러한 구조는 여러 모바일 팀에 공통된 관리 체계를 원하는 기업에게 여전히 매력적입니다.
서비스 시장은 2026년부터 2031년까지 연평균 성장률(CAGR) 16.82%를 나타낼 것으로 예측되며, 이는 소프트웨어 시장 성장률을 상회하는 속도입니다. 플랫폼 도입 후에는 프로덕션 환경 운영에 있어 팀 프로세스의 실질적인 변경이 필요하기 때문에 도입 컨설팅, 파이프라인 마이그레이션, 운영 관리, 워크플로우 설계의 중요성이 점점 더 커지고 있습니다. 많은 조직에서는 진행 중인 용도 제공을 중단하지 않으면서, 플랫폼을 기존의 빌드, 보안, 릴리스, 승인 및 보고 프로세스에 적용할 수 있도록 지원이 필요합니다. 서비스와 플랫폼 라이선스를 결합한 벤더는 보다 견고한 고객 관계를 구축할 수 있습니다. 또한 이러한 서비스는 기존 툴체인에서 마이그레이션하는 동안 발생할 수 있는 업무 중단 위험을 완화할 수도 있습니다.
2025년 모바일 DevOps 플랫폼 시장 규모 중 클라우드 도입이 68.19%를 차지했습니다. 기업들은 하드웨어 관리, 소프트웨어 업데이트, 용량 계획, 러너 가용성 등 레거시 빌드 인프라와 관련된 유지 관리 비용을 절감하기 위해 매니지드 클라우드 러너를 활용해 왔습니다. 또한 클라우드 플랫폼은 애플리케이션 릴리스 활동이 활발해질 때 필요한 용량을 제공합니다. 이는 팀이 여러 용도에 걸쳐 병렬 빌드, 자동 테스트 및 배포 워크플로가 필요한 경우에 유용합니다. 이 모델은 자체 빌드 하드웨어를 유지 관리할 필요 없이 여러 팀을 지원해야 하는 조직에 적합합니다. 표준 모바일 배포 작업을 간소화할 수 있어 가장 널리 채택되는 옵션입니다.
하이브리드 도입은 2031년까지 연평균 성장률(CAGR) 15.43%를 나타낼 것으로 예측됩니다. 규제 대상 산업에서는 이 접근 방식을 채택하여 특정 제어 기능, 소스 리포지토리, 인증 정보, 감사 기록을 On-Premise에 보관하면서 필요에 따라 클라우드 컴퓨팅 용량을 활용하고 있습니다. Bitrise가 EU 운영 데이터센터에 300만 달러를 투자한 것은 고객 데이터를 유럽 관할 구역 내에 보관해야 하는 요구를 충족하기 위함입니다. 국방, 정부 기관 및 규제가 엄격한 금융 서비스 사용자들은 앞으로도 격리된 환경을 계속 필요로 할 가능성이 높습니다. ISO/IEC 27001 인증 및 GDPR(EU 개인정보보호규정)의 데이터 처리 요건은 도입 결정에 있어 중요한 요소로 부상하고 있습니다.
지역별 분석
2025년, 북미는 모바일 DevOps 플랫폼 시장의 36.71% 점유율을 차지했습니다. 이 지역은 소프트웨어 전문 기업의 고밀도 집적, 성숙한 클라우드 인프라, 개발자용 도구에 대한 적극적인 투자라는 장점을 가지고 있습니다. 많은 기업이 기본적인 CI/CD 관행을 릴리스 관리, 가시성, AI를 활용한 파이프라인 기능까지 확장하고 있습니다. 캐나다의 금융 기관 및 정부 기관도 기술 위험 관리에 대한 기대를 바탕으로 하이브리드형 솔루션에 대한 수요를 뒷받침하고 있습니다. 지출이 소수의 주요 플랫폼 기업에 집중되어 있어 대규모 구매자는 가격 결정력을 유지할 수 있습니다.
아시아태평양은 2026년부터 2031년까지 연평균 성장률(CAGR) 17.83%를 나타낼 것으로 예측되며, 가장 빠르게 성장하는 지역이 될 전망입니다. 인도의 확대되는 개발자 기반, 중국의 거대한 용도 플랫폼, 그리고 일본의 제조업 디지털화가 구조화된 엔지니어링 및 릴리스 도구에 대한 수요를 뒷받침하고 있습니다. 한국의 5G 지원 용도 생태계는 자동차 기술 및 게임 사용자들에서의 수요에 기여하고 있습니다. 인도네시아, 태국, 베트남에서는 디지털 금융 서비스 기업들이 소비자용 용도를 확대함에 따라 지역적 수요 클러스터로 발전하고 있습니다.
유럽은 독일, 영국, 프랑스를 필두로 3위 규모 시장을 자랑하는 지역입니다. GDPR(EU 개인정보보호규정), DORA 및 사이버 복원력 법에 따라, 해당 지역의 DevOps 조달에서 규정 준수가 더욱 직접적인 요소가 되고 있습니다. GitLab은 2026년 5월에 버전 19.0을 출시하여, 에어갭이 확보된 규제 환경에서 Duo Agent Platform의 On-Premise 지원을 실현했습니다. 남미에서는 새로운 모바일 플랫폼을 구축하는 핀테크 기업 및 전자상거래 기업들 사이에서 조기 도입이 진행되고 있습니다. 중동 및 아프리카에서는 사우디아라비아와 아랍에미리트의 디지털 정부 및 핀테크에 대한 투자로 수요가 발생하는 한편, 남아프리카공화국과 나이지리아는 빠르게 성장하는 모바일 퍼스트 시장으로 부상하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.01According to Mordor Intelligence, the mobile devOps platform market size was valued at USD 2.43 billion in 2025 and is estimated to grow from USD 2.68 billion in 2026 to reach USD 4.99 billion by 2031, at a CAGR of 13.24% during the forecast period (2026-2031).
This report is Segmented by Component (Software, and Services), Deployment Model (Cloud, Hybrid, and On-Premises), Enterprise Size (Large Enterprises, and Small and Medium-Sized Enterprises), Development Framework (Native IOS Development, Native Android Development, and More), End User (IT and Telecommunication, BFSI, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Mobile DevOps Platform Market Trends and Insights
Accelerating Demand for Continuous Delivery and Automated Mobile Release Pipelines
The Mobile DevOps Platform Market benefits as consumer-facing enterprises seek to release mobile updates in hours instead of weeks. A 2025 JetBrains survey of 805 software professionals found that 41% of organizations deployed via GitHub Actions, while Jenkins remained widely used in large enterprises due to its plugin ecosystem. Many enterprises still operate legacy build servers beside cloud-based CI/CD tools, which increases maintenance work and complicates release management. This creates demand for platforms that connect with current orchestrators rather than requiring a full migration. Mobile DevOps Platform providers that support the full delivery process through a single control layer can address this need. Expectations for quick app updates are placing additional pressure on procurement and engineering teams to modernize release workflows.
AI and ML Integration Enabling Autonomous Pipeline Management
AI-supported workflows are moving from code suggestions to automated testing, failure review, remediation, and deployment management. Harness introduced Autonomous Worker Agents in June 2026, with governance features that include Open Policy Agent controls and audit trails for pipeline actions. Bitrise reported that AI-assisted builds increased 164 times over 1 year, while the rate at which teams shipped to users fell by 20%. The gap shows that code generation can increase pressure on test and release processes if delivery systems do not scale with it. Platforms that work with AI coding tools and preserve review records are likely to have a stronger position with enterprise buyers. The Mobile DevOps Platform Market is therefore placing greater value on governance features rather than managed build capacity alone.
Legacy IT Infrastructure Integration Complexity and High Migration Overhead
Migration costs remain a major obstacle for enterprises that use Jenkins pipelines with large numbers of custom plugins. The 2025 JetBrains survey found that 32% of organizations used 2 CI/CD tools and 9% used 3 or more. These mixed environments can delay full platform consolidation for long periods. Mobile signing systems, including provisioning profiles, keystores, and App Store Connect credentials, are closely tied to current pipeline settings. Rebuilding those processes can require more work than moving the build steps themselves. ISO/IEC 27001 requirements can add further complexity, as organizations must maintain audit records throughout the transition. The Mobile DevOps Platform Market must therefore address both migration planning and product functionality.
Other drivers and restraints analyzed in the detailed report include:
- Rising Cloud-Native Adoption and Hybrid Deployment Architectures
- Mobile-First Digital Transformation Across Healthcare, BFSI, and Telecom Verticals
- Acute Shortage of Qualified Mobile DevOps Engineering Talent
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 72.41% of the Mobile DevOps Platform Market share in 2025, reflecting enterprise use of subscription-based CI/CD platforms. Organizations moved from self-managed build servers to software platforms during the 2019-2025 period. The software category gives teams modular access to build, test, release, security review, and workflow approval functions from a common operating environment. It also supports license-based purchasing, which lets organizations align platform access with user counts, project needs, and recurring software budgets rather than project-specific service engagements. This structure remains attractive for enterprises that want common controls across several mobile teams.
Services are projected to grow at a 16.82% CAGR from 2026 to 2031, faster than software. Implementation consulting, pipeline migration, managed operations, and workflow design are becoming increasingly important after a platform is purchased, as production use requires practical changes to team processes. Many organizations need help adapting a platform to existing build, security, release, approval, and reporting processes without interrupting active application delivery. Vendors that combine services with platform licenses can develop more durable customer relationships. These services can also reduce the risk of disruption during a move from existing toolchains.
Cloud deployment accounted for 68.19% of the Mobile DevOps Platform Market size in 2025. Enterprises have used managed cloud runners to reduce the maintenance costs associated with legacy build infrastructure, including hardware administration, software updates, capacity planning, and runner availability. Cloud platforms also provide capacity when application release activity increases, which is useful when teams need parallel builds, automated tests, and distribution workflows across several applications. This model suits organizations that need to support several teams without maintaining their own build hardware. It has become the largest deployment option because it can simplify standard mobile delivery tasks.
Hybrid deployment is projected to grow at a 15.43% CAGR through 2031. Regulated sectors use this approach to keep selected controls, source repositories, credentials, and audit records on-premises while using cloud computing capacity when needed. Bitrise's USD 3 million investment in an EU-operated data center addressed the need to keep customer data within European jurisdictions. Defense, government, and highly regulated financial services users may continue to require isolated environments. ISO/IEC 27001 certifications and GDPR data processing requirements are becoming important factors in deployment decisions.
Complete Report Scope:
- By Component
- Software
- Services
- By Deployment Model
- Cloud
- Hybrid
- On-Premises
- By Enterprise Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Development Framework
- Native iOS Development
- Native Android Development
- Cross-platform Development
- Progressive Web Applications
- By End User
- IT and Telecommunication
- BFSI
- Automotive and Transportation
- Healthcare and Life Sciences
- Retail and E-Commerce
- Industrial Manufacturing
- Education and Research Institutions
- Government and Administration
- Energy and Utilities
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 36.71% of the Mobile DevOps Platform Market share in 2025. The region benefits from a high concentration of software-focused companies, mature cloud infrastructure, and strong spending on developer tools. Many enterprises are extending basic CI/CD practices to include release management, observability, and AI-assisted pipeline functions. Canadian financial institutions and government agencies also support hybrid demand through technology risk management expectations. Large buyers can retain pricing power because spending is concentrated among a smaller group of major platform companies.
Asia-Pacific is projected to grow at a 17.83% CAGR from 2026 to 2031, making it the fastest-growing regional area. India's growing developer base, China's large application platforms, and Japan's manufacturing digitization support demand for structured engineering and release tooling. South Korea's 5G-enabled application ecosystem contributes to demand from automotive technology and gaming users. Indonesia, Thailand, and Vietnam are developing as a regional demand cluster as digital financial services companies scale consumer applications.
Europe is the 3rd-largest regional area, led by Germany, the United Kingdom, and France. GDPR, DORA, and the Cyber Resilience Act are making compliance a more direct part of DevOps procurement in the region. GitLab released version 19.0 in May 2026 with on-premises support for the Duo Agent Platform in air-gapped regulated environments. South America has early adoption among fintech and e-commerce companies building new mobile platforms. The Middle East and Africa have demand from digital government and fintech investment in Saudi Arabia and the United Arab Emirates, while South Africa and Nigeria represent growing mobile-first markets.
- Bitrise AB
- Appcircle Inc.
- Nevercode Ltd.
- Kobiton, Inc.
- BrowserStack Limited
- Sauce Labs Inc.
- LambdaTest, Inc.
- HeadSpin, Inc.
- Perfecto Mobile, Inc.
- Applause App Quality, Inc.
- Kobiton Testing, Inc.
- Rainforest QA, Inc.
- Testlio, Inc.
- Global App Testing Limited
- Applause GmbH
- Buildkite Pty Ltd.
- Circle Internet Services, Inc.
- Harness, Inc.
- GitLab Inc.
- Atlassian Corporation Plc
- JFrog Ltd.
- CloudBees, Inc.
- Gradle Inc.
- JetBrains s.r.o.
- Embrace Mobile, Inc.
- Instabug, Inc.
- Zimperium, Inc.
- Appium
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Mobile Release Cadence and Continuous Delivery Adoption
- 4.2.2 Device and Operating-System Fragmentation Increasing Automated Testing Demand
- 4.2.3 Rising Enterprise Use of Cross-Platform Mobile Frameworks
- 4.2.4 AI-Assisted Test Authoring and Failure Remediation
- 4.2.5 Mobile Application Security and Privacy Shifted Left Into Delivery Pipelines
- 4.2.6 Managed Apple Silicon Infrastructure Reducing iOS Build Bottlenecks
- 4.3 Market Restraints
- 4.3.1 Apple Platform Governance and Code-Signing Dependencies
- 4.3.2 Real-Device Coverage Costs and Capacity Constraints
- 4.3.3 Flaky Mobile Tests and Low Automation Reliability
- 4.3.4 Fragmented Toolchains and Skills Shortages in Mobile Release Engineering
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Deployment Model
- 5.2.1 Cloud
- 5.2.2 Hybrid
- 5.2.3 On-Premises
- 5.3 By Enterprise Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium-Sized Enterprises
- 5.4 By Development Framework
- 5.4.1 Native iOS Development
- 5.4.2 Native Android Development
- 5.4.3 Cross-platform Development
- 5.4.4 Progressive Web Applications
- 5.5 By End User
- 5.5.1 IT and Telecommunication
- 5.5.2 BFSI
- 5.5.3 Automotive and Transportation
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Retail and E-Commerce
- 5.5.6 Industrial Manufacturing
- 5.5.7 Education and Research Institutions
- 5.5.8 Government and Administration
- 5.5.9 Energy and Utilities
- 5.5.10 Other End Users
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Russia
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Southeast Asia
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Bitrise AB
- 6.4.2 Appcircle Inc.
- 6.4.3 Nevercode Ltd.
- 6.4.4 Kobiton, Inc.
- 6.4.5 BrowserStack Limited
- 6.4.6 Sauce Labs Inc.
- 6.4.7 LambdaTest, Inc.
- 6.4.8 HeadSpin, Inc.
- 6.4.9 Perfecto Mobile, Inc.
- 6.4.10 Applause App Quality, Inc.
- 6.4.11 Kobiton Testing, Inc.
- 6.4.12 Rainforest QA, Inc.
- 6.4.13 Testlio, Inc.
- 6.4.14 Global App Testing Limited
- 6.4.15 Applause GmbH
- 6.4.16 Buildkite Pty Ltd.
- 6.4.17 Circle Internet Services, Inc.
- 6.4.18 Harness, Inc.
- 6.4.19 GitLab Inc.
- 6.4.20 Atlassian Corporation Plc
- 6.4.21 JFrog Ltd.
- 6.4.22 CloudBees, Inc.
- 6.4.23 Gradle Inc.
- 6.4.24 JetBrains s.r.o.
- 6.4.25 Embrace Mobile, Inc.
- 6.4.26 Instabug, Inc.
- 6.4.27 Zimperium, Inc.
- 6.4.28 Appium
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


