

|
시장보고서
상품코드
2118232
중국의 기업 컨텐츠 관리(ECM) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)China Enterprise Content Management (ECM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
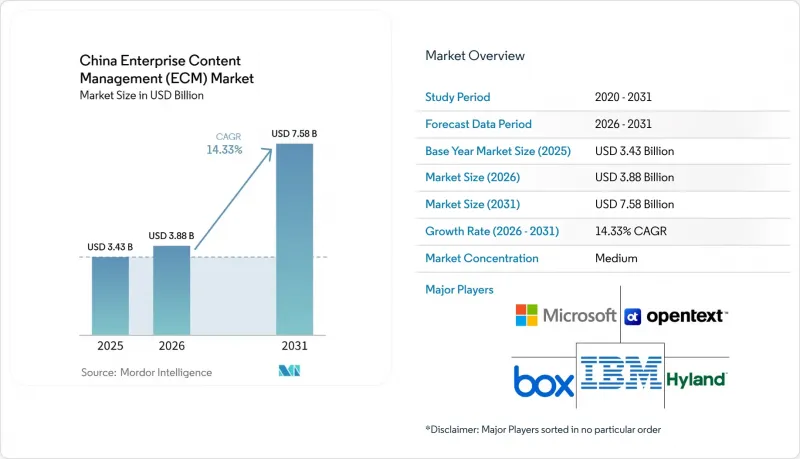
에 의하면, 중국의 기업 컨텐츠 관리(ECM) 시장 규모는 2025년에 34억 3,000만 달러로 평가되었고, 2026년에 38억 8,000만 달러로 추정되고, 2031년까지 75억 8,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 14.33%로 성장할 것으로 전망됩니다.
본 보고서는 솔루션 유형별(문서 관리, 기록 관리 등), 배포 방식별(온프레미스, 클라우드, 하이브리드), 기업 규모별(중소기업, 대기업), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 정부·공공 부문, 의료 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
중국의 기업 컨텐츠 관리(ECM) 시장 동향 및 인사이트
중국 기업의 디지털 기록 전환 가속화
중국 기업에는 여전히 대량의 종이 기록물이 존재하며, 이로 인해 접근 제한이나 처리 시간 지연이 발생하고 보존 위험이 높아지고 있습니다. 이러한 압박은 은행, 에너지, 제약 등 규제가 엄격한 분야에서 가장 심하며, 이러한 분야에서는 아카이브 양이 수년에 걸쳐 축적되는 경우가 많습니다. 따라서 전환 작업은 단순한 현대화 프로젝트에 그치지 않고 실질적인 구매 동인으로 작용하고 있습니다. 또한 캡처, 스캔, 색인 생성, 메타데이터 준비의 중요성도 부각되고 있습니다. 이러한 절차가 전환 후 디지털화된 컨텐츠의 유용성을 좌우하기 때문입니다. 리포지토리 관리와 보다 신속한 데이터 수집, 업계 고유의 문서 구조를 결합할 수 있는 벤더는 중국 기업 컨텐츠 관리(ECM) 시장의 확대에 따라 혜택을 볼 가능성이 높습니다.
AI를 활용한 컨텐츠 분류 및 검색 효율
AI 덕분에 엔터프라이즈 컨텐츠 시스템의 역할은 단순한 저장에서 능동적인 의사결정 지원으로 전환되고 있습니다. 현재 구매자들은 긴 수동 검토 주기가 필요 없이 플랫폼이 파일을 분류하고, 중복을 감지하며, 경쟁 문서를 표시하고, 관련 컨텐츠를 추출해 주기를 기대하고 있습니다. 2026년 1월에 실시된 WPS 365의 ‘Smart Document Library’ 업그레이드에서는 중복 감지 정확도 95%, 경쟁 문서 식별 정확도 80%가 보고되었으며, 이는 컨텐츠 관리가 일상 업무에서 운영 측면에서 얼마나 중요성이 커지고 있는지를 보여줍니다. 이러한 변화는 중국의 기업 컨텐츠 관리(ECM) 시장에서 중요한 의미를 지닙니다. 중국어 업무 기록, 조달 파일, 규제 관련 문서에는 견고한 현지 언어 지원이 요구되기 때문입니다. 또한, 2025년 11월 IBM이 공개한 ‘Core Content Services MCP Server’ 프리뷰에서는 세계 벤더가 AI 모델을 컨텐츠 리포지토리에 직접 연동하고 있음을 보여주며, AI 기반 정보 관리에 대한 기준이 한 단계 높아졌습니다.
복잡한 현지화 및 데이터 상주 요건
데이터 거버넌스 규정이 아키텍처, 호스팅, 릴리스 관리에 영향을 미치기 때문에 현지화는 여전히 중국 기업 컨텐츠 관리(ECM) 시장에서 큰 장벽으로 남아 있습니다. 해외 벤더가 효과적으로 경쟁하기 위해서는 대부분의 경우 독립적인 현지 환경, 보다 엄격한 데이터 분리, 그리고 중국 특유의 운영 관행이 필요합니다. 이로 인해 비용이 증가하고, 세계 제품 주기에 비해 신기능 배포가 지연될 가능성이 있습니다. 반면, 국내 벤더는 자사 플랫폼이 이미 현지 도입 요건을 충족하고 있기 때문에 이러한 상황에서 보다 명확한 방향을 제시할 수 있습니다. 2026년 5월 정부 기관용으로 출시된 ‘WPS 신화 지능형 보안 에디션’은 기밀성이 높은 환경에서 완벽하게 현지화된 스택이 실질적인 경쟁 우위로 자리매김하고 있음을 여실히 보여줍니다.
부문 분석
2025년 중국 기업 컨텐츠 관리(ECM) 시장에서 문서 관리는 26.42%를 차지하며 가장 큰 솔루션 카테고리가 되었습니다. 버전 관리, 중앙 집중식 저장 및 파일 액세스 규칙은 일반적으로 공식적인 컨텐츠 거버넌스의 첫 단계이므로, 많은 구매자에게 여전히 출발점이 되고 있습니다. 이러한 주도적 위상은 기업이 먼저 문서 관리를 안정화한 후, 더 광범위한 저장, 검토 및 프로세스 관리로 전환하는 일반적인 구매 경로를 반영합니다. 기록 관리 및 웹 컨텐츠 관리는 일반적으로 이 첫 번째 단계가 정비된 후에 확대됩니다. 특히, 규정 준수나 퍼블리싱 요구 사항으로 인해 수동 관리가 어려워진 경우, 이러한 경향이 두드러집니다.
워크플로우 및 비즈니스 프로세스 관리는 2031년까지 연평균 성장률(CAGR) 16.94%를 나타낼 것으로 예측되며, 중국 기업 컨텐츠 관리(ECM) 시장에서 가장 빠르게 성장하는 솔루션 분야가 될 전망입니다. 기업들이 승인, 검토 및 컨텐츠 기반의 의사결정을 부서 간에 더 신속하게 진행하고자 함에 따라 수요가 증가하고 있습니다. 디지털 자산 관리 및 사례 관리는 규모는 작지만 여전히 중요한 영역으로 남아 있습니다. 디지털 자산 관리는 기업이 미디어 라이브러리나 브랜드 관련 파일을 처리할 때 중요성이 커지고 있는 반면, 사례 관리는 정부, 법무, 의료 분야에서 더욱 중요하게 여겨지고 있습니다. 전반적인 추세로 볼 때, 구매자들은 현재 컨텐츠 시스템이 단순한 독립형 저장소로서 기능하는 데 그치지 않고, 검토 경로, 보존 기간 로직, AI 기반 검색, 그리고 팀 간 가시성 향상을 지원하기를 기대하고 있습니다. IBM의 ‘2025 MCP Server’ 프리뷰는 AI 모델을 문서 및 메타데이터 조작과 연동하여 저장된 컨텐츠를 실행 가능한 워크플로우의 입력 정보로 변환하는 것을 지원함으로써 이러한 방향성을 반영하고 있습니다.
2025년 중국 기업 컨텐츠 관리(ECM) 시장에서 클라우드는 71.28%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 17.31%를 나타낼 것으로 예측됩니다. 이러한 조합은 클라우드 도입이 성숙한 교체 주기가 아니라 여전히 활발한 확장 단계에 있음을 보여줍니다. 구매자가 클라우드 도입을 선택하는 이유는 설정 시간 단축, 업데이트 작업 간소화, 그리고 분산된 팀 전체에 대한 접근성 확대가 가능하기 때문입니다. 중국 기업 컨텐츠 관리(ECM) 시장에서 클라우드가 주도적인 위치를 차지하고 있는 것은 많은 신규 도입 사례가 인프라 소유 형태에 대한 선호가 아니라 디지털 워크플로우 목표를 출발점으로 시작되고 있다는 사실도 반영하고 있습니다.
수요 동향은 단순히 온프레미스 인프라에서 클라우드로의 전환이라는 단순한 이야기보다 여전히 더 복잡합니다. 기밀성이 높은 업계의 많은 기업들은 온프레미스 호스팅, 접근 및 데이터 흐름에 대한 더 엄격한 거버넌스를 지원하는 관리형 클라우드 모델을 선택하고 있습니다. 반면, 기밀성이 높은 기록과 광범위한 협업 컨텐츠를 분리해야 하는 조직의 경우, 하이브리드 배포가 여전히 중요한 선택지로 남아 있습니다. 물리적 격리와 내부 통제가 조달의 핵심인 국영 기업, 정부 기관 및 보안에 민감한 조직에서는 온프레미스 환경이 여전히 중요한 위치를 차지하고 있습니다. 전 세계 공급업체들은 주권 및 규정 준수에 중점을 둔 도입 전략으로 대응하고 있는 반면, 현지 공급업체들은 국내 스택을 활용하여 신뢰성 장벽을 낮추고 있습니다. 2025년 7월, 화웨이와 공동 개발한 광시 좡족 자치구의 스마트 아카이브 플랫폼이 Ascend AI 및 Kunpeng 920 아키텍처의 호환성 인증을 획득했습니다. 이는 인프라의 현지화와 컨텐츠 플랫폼의 검증이 점점 더 밀접하게 연결되고 있음을 보여줍니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the China enterprise content management (ECM) market size is projected to be USD 3.43 billion in 2025, USD 3.88 billion in 2026, and reach USD 7.58 billion by 2031, growing at a CAGR of 14.33% from 2026 to 2031.
This report is Segmented by Solution Type (Document Management, Records Management, and More), Deployment Mode (On-Premises, Cloud, and Hybrid), Enterprise Size (Small and Medium Enterprises, and Large Enterprises), and End-User Industry (BFSI, Government and Public Sector, Healthcare, and More). The Market Forecasts are Provided in Terms of Value (USD).
China Enterprise Content Management (ECM) Market Trends and Insights
Accelerating Digital Records Migration in Chinese Enterprises
Chinese enterprises still carry a large volume of paper-heavy records that limit access, slow response times, and increase retention risk. This pressure is strongest in regulated fields such as banking, energy, and pharmaceuticals, where archive volumes often stretch across many years. Migration work is therefore becoming a practical buying trigger, not just a modernization project. It also underscores the importance of capture, scanning, indexing, and metadata preparation, as these steps determine how useful digitized content will be after migration. Vendors that can pair repository control with faster ingest and better industry-specific document structures are likely to benefit as the China Enterprise Content Management (ECM) Market expands.
AI-Driven Content Classification and Retrieval Efficiency
AI is shifting the role of enterprise content systems from storage toward active decision support. Buyers now expect platforms to classify files, detect duplication, flag conflicts, and surface relevant content without long manual review cycles. WPS 365's Smart Document Library upgrade in January 2026 reported 95% duplicate-detection accuracy and 80% conflict-identification accuracy, demonstrating how content control is becoming more operational in daily work. This change matters in the China Enterprise Content Management (ECM) Market because Chinese-language business records, procurement files, and regulatory documents require robust local-language support. IBM's November 2025 preview of its Core Content Services MCP Server also showed that global vendors are linking AI models directly to content repositories, raising the bar for AI-ready information management.
Complex Localization and Data Residency Requirements
Localization remains a meaningful barrier in the China Enterprise Content Management (ECM) Market because data governance rules affect architecture, hosting, and release management. Foreign suppliers often need separate local environments, tighter data segregation, and China-specific operating practices to compete effectively. That adds cost and can slow the rollout of new features when compared with their global product cycles. Domestic vendors have a clearer path in these situations because their platforms are already aligned with local deployment expectations. The launch of the WPS Xinhua Intelligent Security Version for government office use in May 2026 highlights how fully localized stacks are being positioned as a practical advantage in sensitive environments.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-First Enterprise Software Procurement
- Regulatory Demand for Audit-Ready Information Retention
- High Switching Costs from Legacy Document Repositories
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Document Management accounted for 26.42% of the China Enterprise Content Management (ECM) Market in 2025, making it the largest solution category. It remains the starting point for many buyers because version control, central storage, and file access rules are usually the first steps in formal content governance. This leadership also reflects a common purchase path in which enterprises stabilize documents first, then move to broader retention, review, and process control. Records Management and Web Content Management usually expand after that first layer is in place, especially when compliance or publishing needs become harder to manage manually.
Workflow and Business Process Management is projected to grow at a 16.94% CAGR through 2031, making it the fastest-moving solution segment in the China Enterprise Content Management (ECM) Market. Demand is rising because enterprises want approvals, reviews, and content-based decisions to move faster across departments. Digital Asset Management and Case Management remain smaller but important layers, with Digital Asset Management gaining relevance where enterprises handle media libraries and branded files, while Case Management matters more in government, legal, and healthcare settings. The wider pattern is that buyers now expect content systems to support review paths, retention logic, AI-supported search, and better visibility across teams rather than function as stand-alone repositories. IBM's 2025 MCP Server preview reflects this direction because it links AI models with document and metadata operations, helping turn stored content into actionable workflow input.
Cloud accounted for 71.28% of the China Enterprise Content Management (ECM) Market in 2025 and is forecast to grow at a 17.31% CAGR through 2031. That combination shows that cloud adoption is still in an active expansion stage rather than a mature replacement cycle. Buyers are choosing cloud deployments because they reduce setup time, simplify updates, and enable broader access across distributed teams. The leading position of cloud in the China Enterprise Content Management (ECM) Market also reflects the fact that many new deployments are starting from digital workflow goals rather than from infrastructure ownership preferences.
The shape of demand is still more nuanced than a simple shift away from local infrastructure. Many enterprises in sensitive sectors are choosing controlled cloud models that support local hosting and tighter governance over access and data flow, while hybrid deployment remains relevant for organizations that need to separate sensitive records from broader collaboration content. On-premises environments still hold an important place in state-owned enterprises, government bodies, and security-sensitive organizations where physical isolation and internal control remain central to procurement. Global suppliers are adapting with sovereign and compliance-focused deployment strategies, while local suppliers are using domestic stacks to reduce trust barriers. In July 2025, a Guangxi smart archive platform developed with Huawei passed compatibility certifications for the Ascend AI and Kunpeng 920 architectures, demonstrating how infrastructure localization and content platform validation are increasingly linked.
Complete Report Scope:
- By Solution Type
- Document Management
- Records Management
- Workflow and Business Process Management
- Case Management
- Digital Asset Management
- Web Content Management
- Other Solutions
- By Deployment Mode
- On-Premises
- Cloud
- Hybrid
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Industry
- BFSI
- Government and Public Sector
- Healthcare
- IT and Telecommunications
- Manufacturing
- Retail
- Media and Entertainment
- Education
- Energy and Utilities
- Other End-User Industries
List of Companies Covered in this Report:
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software, Inc.
- Box, Inc.
- Oracle Corporation
- SAP SE
- Adobe Inc.
- Newgen Software Technologies Limited
- Laserfiche Inc.
- M-Files, Inc.
- DocuWare GmbH
- Alfresco Software, Inc.
- Tencent Cloud
- Yonyou Network Technology
- Alibaba Cloud
- Kingsoft Office Software
- Tungsten Automation Corporation
- Xerox Holdings Corporation
- Zoho Corporation Private Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Digital Records Migration in Chinese Enterprises
- 4.2.2 AI-Driven Content Classification and Retrieval Efficiency
- 4.2.3 Cloud-First Enterprise Software Procurement
- 4.2.4 Regulatory Demand for Audit-Ready Information Retention
- 4.2.5 Workflow Automation for High-Volume Document Operations
- 4.2.6 Cross-Platform Integration With ERP, CRM, and Case Systems
- 4.3 Market Restraints
- 4.3.1 Complex Localization and Data Residency Requirements
- 4.3.2 High Switching Costs From Legacy Document Repositories
- 4.3.3 Cybersecurity and Sensitive Data Exposure Risks
- 4.3.4 Fragmented Buyer Readiness Across Mid-Market Enterprises
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution Type
- 5.1.1 Document Management
- 5.1.2 Records Management
- 5.1.3 Workflow and Business Process Management
- 5.1.4 Case Management
- 5.1.5 Digital Asset Management
- 5.1.6 Web Content Management
- 5.1.7 Other Solutions
- 5.2 By Deployment Mode
- 5.2.1 On-Premises
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 Government and Public Sector
- 5.4.3 Healthcare
- 5.4.4 IT and Telecommunications
- 5.4.5 Manufacturing
- 5.4.6 Retail
- 5.4.7 Media and Entertainment
- 5.4.8 Education
- 5.4.9 Energy and Utilities
- 5.4.10 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 OpenText Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Hyland Software, Inc.
- 6.4.5 Box, Inc.
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Adobe Inc.
- 6.4.9 Newgen Software Technologies Limited
- 6.4.10 Laserfiche Inc.
- 6.4.11 M-Files, Inc.
- 6.4.12 DocuWare GmbH
- 6.4.13 Alfresco Software, Inc.
- 6.4.14 Tencent Cloud
- 6.4.15 Yonyou Network Technology
- 6.4.16 Alibaba Cloud
- 6.4.17 Kingsoft Office Software
- 6.4.18 Tungsten Automation Corporation
- 6.4.19 Xerox Holdings Corporation
- 6.4.20 Zoho Corporation Private Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


