

|
시장보고서
상품코드
2118238
싱가포르의 기업 컨텐츠 관리(ECM) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Singapore Enterprise Content Management (ECM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
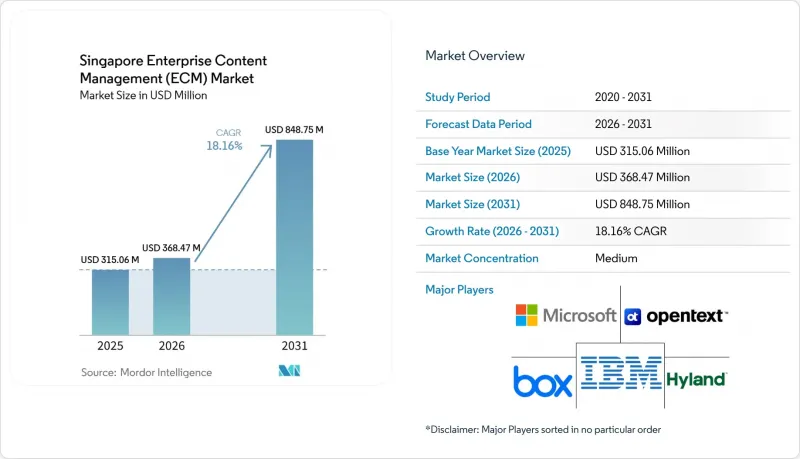
에 의하면, 싱가포르의 기업 컨텐츠 관리(ECM) 시장 규모는 2025년에 3억 1,506만 달러로 평가되었고, 2026년 3억 6,847만 달러에서 2031년까지 8억 4,875만 달러에 이를 것으로 추정되며, 2026-2031년 예측 기간에서 CAGR은 18.16%를 나타낼 전망입니다.
본 보고서는 솔루션 유형별(문서 관리, 기록 관리 등), 배포 모드별(온프레미스, 클라우드, 하이브리드), 기업 규모별(중소기업, 대기업), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 정부·공공 부문, 의료, IT 및 통신 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
싱가포르의 기업 컨텐츠 관리(ECM) 시장 동향 및 인사이트
컨텐츠 워크플로우에 통합된 AI 코파일럿
AI 코파일럿은 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 저장된 정보를 처리하는 방식을 변화시키고 있습니다. 이는 사용자가 플랫폼에 대해 단순히 파일을 검색하는 것뿐만 아니라 업무를 안내해 줄 것을 기대하게 되었기 때문입니다. 이러한 도구는 문서 처리 중에 분류 제안, 승인 경로 지정, 예외 추출을 수행할 수 있어 운영 팀과 규정 준수 팀의 수작업을 줄여줍니다. 하이랜드(Highland)는 2026년 6월 ‘엔터프라이즈 컨텍스트 엔진(Enterprise Context Engine)’을 출시했습니다. 이 제품은 의료, 금융 서비스, 보험, 정부 기관을 위한 산업별 온톨로지를 특징으로 하며, 벤더가 도메인 특화형 AI를 컨텐츠 시스템에 어떻게 통합하고 있는지를 보여줍니다. 또한, GovTech사는 싱가포르 정부 기관에 ‘AISAY v2’를 도입했습니다. 이 플랫폼은 대량의 문서 세트를 몇 초 만에 처리하여 워크플로우에서 사용할 수 있는 구조화된 JSON 형식의 출력을 생성할 수 있습니다. 이러한 변화로 인해 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 수요가 증가하고 있습니다. 이는 구매자들이 AI를 활용한 컨텐츠 처리를 미래의 추가 기능이 아닌, 일상적인 프로세스 관리의 일부로 인식하게 되었기 때문입니다.
데이터 상주 요건 및 주권 요건
데이터 거주성에 관한 규정은 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 특히 기밀성이 높은 재무, 개인정보 또는 의료 기록을 관리하는 조직에게 있어 구매의 핵심 판단 기준이 되고 있습니다. 싱가포르의 PDPA(개인정보보호법)는 개인 데이터의 취급 및 전송 방법에 대한 의무를 부과하고 있으며, 컨텐츠 플랫폼 선정에 있어 국경을 초월한 관리는 여전히 중요한 요소로 남아 있습니다. 이 문제는 BFSI(은행 및 금융 및 보험) 및 의료 분야에서 더욱 두드러지며, 해당 분야의 컨텐츠 저장소에는 명확한 관할권에 의한 보호와 더욱 강력한 거버넌스 관리가 필요한 기록이 보관되어 있습니다. 마이크로소프트가 2025-2029년 싱가포르의 클라우드 및 AI 인프라에 55억 달러를 투자하는 것은 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 이러한 수요를 뒷받침하는 데 필요한 현지 대응 역량을 강화하기 위한 조치입니다. 그 결과, 클라우드 성능과 법적 보장을 모두 충족시킬 수 있는 벤더는 싱가포르의 기업 컨텐츠 관리(ECM) 시장 전반에 걸친 경쟁 평가에서 더 유리한 입지를 차지하게 될 것입니다.
레거시 시스템과의 통합 복잡성
통합의 복잡성은 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 여전히 가장 큰 구조적 제약으로 남아 있습니다. 특히, 오랫동안 정보 시스템을 운영해 온 대기업에서 두드러지게 나타납니다. BFSI(은행 및 금융 및 보험) 및 정부 기관의 오래된 리포지토리에는 대개 사용자 정의 메타데이터 구조, 포인트-투-포인트 링크, 그리고 ERP, HRMS, 핵심 운영 체제와의 연결에 관한 문서화가 불충분한 부분이 포함되어 있습니다. 이로 인해 마이그레이션은 많은 구매자가 당초 예상했던 것보다 더 많은 시간과 비용이 소요되며, 단계적 마이그레이션 계획에 대한 의존도가 높아집니다. 2026년 5월, 주택개발청(HDB)이 GeBIZ를 통해 실시한 AI 기반 지식 관리 시스템 입찰에서는 기존 정보 시스템, 문서 보관 시스템 및 역할 기반 접근 제어와의 통합이 명시적으로 요구되어, 통합 부담이 얼마나 중요한지 여실히 드러났습니다. 이 때문에 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서는 조달 승인이 이미 확보된 경우라 하더라도 도입 일정이 당초 계획보다 훨씬 더 길어질 가능성이 있습니다.
부문 분석
2025년에는 문서 관리가 32.14%로 가장 큰 점유율을 차지했으며, 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 구매자에게 가장 명확한 진입 지점이 되었습니다. BFSI(은행 및 금융 및 보험) 기관들이 보존 기간 및 감사 요건에 부합하는 방식으로 대출 파일, KYC(고객 신원 확인) 기록, 규제 관련 문서를 확실하게 관리해야 했기 때문에 이 분야는 계속해서 중심적인 위치를 차지했습니다. 싱가포르의 기업 컨텐츠 관리(ECM) 업계에서 이 분야가 여전히 중요한 위치를 차지한 이유는 규정 준수를 위한 문서 처리가 지속적인 업무이며 단기적인 예산 변동의 영향을 덜 받기 때문입니다. 기록 관리 및 사례 관리의 규모는 비교적 작았지만, 조직이 규제 대상 파일의 라이프사이클 관리를 강화하거나 체계적인 처리가 필요한 상황에서는 여전히 중요한 역할을 수행했습니다.
워크플로우 및 비즈니스 프로세스 관리는 2026-2031년 연평균 성장률(CAGR) 20.83%를 나타낼 것으로 예측되며, 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 가장 빠르게 성장하는 솔루션 분야가 될 전망입니다. 이러한 성장은 과거 수작업으로 이루어지던 승인 경로 설정, 예외 처리, 팀 간 업무 인계 과정에서 AI 도입이 확산되고 있는 것이 원동력이 되고 있습니다. 디지털 자산 관리는 미디어, 소매, 마케팅 부문의 보다 특화된 요구를 지속적으로 충족시켜 온 반면, 웹 컨텐츠 관리는 금융 서비스 및 공공 부문의 출판 및 정보 공개 워크플로우를 뒷받침했습니다. 문서 캡처 및 이메일 아카이빙을 포함하는 ‘기타 솔루션’ 그룹은 초기 단계의 디지털화 프로그램을 통해 싱가포르의 기업 컨텐츠 관리(ECM) 시장에 진입하는 중견 기업 구매자들에게 계속해서 중요한 역할을 수행했습니다.
2025년에는 클라우드 도입이 79.41%의 점유율을 차지했으며, 연평균 성장률(CAGR) 21.24%로 가장 빠르게 성장하는 도입 형태가 되어, 싱가포르의 기업 컨텐츠 관리(ECM) 시장이 얼마나 확고하게 ‘클라우드 우선’ 구매 태도로 전환되고 있는지를 여실히 보여주었습니다. 이는 기존 아키텍처와 새로운 아키텍처로 양분된 시장을 의미하는 것은 아닙니다. 신규 투자의 대부분이 클라우드를 처음 시도하는 것이 아니라, 그 활용을 확대하는 것이기 때문입니다. 클라우드가 가장 규모가 크고 가장 빠르게 성장하는 부문이라는 사실은 이 모델에 대한 기업의 신뢰가 이미 시범 운영 단계를 넘어섰음을 시사합니다. 많은 구매자에게 있어 클라우드는 이제 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 새로운 컨텐츠 프로그램의 기본 아키텍처가 되었습니다.
이러한 모멘텀은 현지 인프라 확충과 거버넌스가 확립된 호스팅 환경에 대한 신뢰 증대에 힘입어 유지되고 있습니다. 마이크로소프트가 싱가포르에서 수년에 걸쳐 진행해 온 인프라 구축 노력은 주권형 및 AI 지원 워크로드에 필요한 처리 능력을 강화하고 있습니다. 특정 컨텐츠 클래스에 대해 보다 엄격한 관리가 필요한 대규모 BFSI(은행 및 금융 및 보험) 기관 및 정부 기관 사이에서는 하이브리드 배포가 여전히 실용적인 역할을 수행하고 있으며, 기밀 정보나 기밀 지정 자료를 다루는 제한된 이용 사례에서는 온프레미스 시스템이 여전히 필요했습니다. 그럼에도 불구하고 장기적인 방향성은 여전히 기존 배포 형태에서 더욱 벗어나는 추세를 보이고 있으며, 이에 따라 클라우드는 싱가포르의 기업 컨텐츠 관리(ECM) 시장에서 중심적인 위치를 계속 차지할 것으로 예측됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the Singapore enterprise content management (ECM) market size was valued at USD 315.06 million in 2025 and estimated to grow from USD 368.47 million in 2026 to reach USD 848.75 million by 2031, at a CAGR of 18.16% during the forecast period 2026-2031.
This report is Segmented by Solution Type (Document Management, Records Management, and More), Deployment Mode (On-Premises, Cloud, and Hybrid), Enterprise Size (Small and Medium Enterprises, and Large Enterprises), and End-User Industry (BFSI, Government and Public Sector, Healthcare, IT and Telecommunications, and More). The Market Forecasts are Provided in Terms of Value (USD).
Singapore Enterprise Content Management (ECM) Market Trends and Insights
AI Copilots Embedded in Content Workflows
AI copilots are changing how the Singapore enterprise content management (ECM) market handles stored information, because users now expect platforms to guide work rather than only retrieve files. These tools can suggest classifications, route approvals, and surface exceptions during document handling, reducing manual effort for operations and compliance teams. Hyland launched its Enterprise Context Engine in June 2026, featuring sector-specific ontologies for healthcare, financial services, insurance, and government, demonstrating how vendors are integrating domain-aware AI into content systems. GovTech also deployed AISAY v2 in Singapore government agencies, and the platform can process large document sets in seconds and return structured JSON outputs for workflow use. This shift is boosting demand in the Singapore enterprise content management (ECM) market, as buyers now see AI-driven content handling as part of day-to-day process control rather than a future add-on.
Data Residency and Sovereignty Requirements
Data residency rules are becoming a core buying factor in the Singapore enterprise content management (ECM) market, especially for organizations that manage sensitive financial, personal, or clinical records. Singapore's PDPA imposes obligations on how personal data is handled and transferred, keeping cross-border controls central to content platform selection. This issue is more visible in BFSI and healthcare, where content repositories hold records that need clear jurisdictional protection and stronger governance controls. Microsoft's USD 5.5 billion investment in cloud and AI infrastructure in Singapore from 2025 through 2029 reinforces the local capacity needed to support this demand in the Singapore enterprise content management (ECM) market. As a result, vendors that can align cloud performance with jurisdictional assurance are better placed in competitive evaluations across the Singapore enterprise content management (ECM) market.
High Integration Complexity With Legacy Systems
Integration complexity remains the biggest structural restraint in the Singapore enterprise content management (ECM) market, especially among large enterprises with long-established information systems. Older repositories in BFSI and government often include custom metadata structures, point-to-point links, and poorly documented connections to ERP, HRMS, and core operating systems. This makes migration slower, costlier, and more dependent on staged transition plans than many buyers first expect. A May 2026 GeBIZ tender from the Housing and Development Board for an AI-driven knowledge management system explicitly required integration with existing information systems, document storage, and role-based access controls, underscoring the centrality of the integration burden. Because of this, deployment timelines in the Singapore enterprise content management (ECM) market can stretch well beyond initial plans even when procurement approval is already in place.
Other drivers and restraints analyzed in the detailed report include:
- Zero Trust Content Access Controls
- Cloud Migration of Legacy Repositories
- User Resistance to Content Governance Discipline
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Document management held the largest share at 32.14% in 2025, which made it the clearest entry point for buyers in the Singapore enterprise content management (ECM) market. It remained central because BFSI institutions needed reliable control over loan files, KYC records, and regulatory correspondence that aligned with retention and audit expectations. This part of the Singapore enterprise content management (ECM) industry also kept its weight because compliance-driven document handling is recurring and less exposed to short-term budget swings. Records management and case management stayed smaller, but they remained important where organizations needed stronger lifecycle control and structured handling of regulated files.
Workflow and business process management is projected to grow at a 20.83% CAGR from 2026 to 2031, making it the fastest-growing solution area in the Singapore enterprise content management (ECM) market. Growth is being driven by the broader adoption of AI for approval routing, exception handling, and cross-team handoffs that were once handled manually. Digital asset management continued to serve more focused needs in media, retail, and marketing functions, while web content management supported publishing and disclosure workflows across financial services and the public sector. The other solutions group, which includes document capture and email archiving, remained relevant for mid-market buyers entering the Singapore enterprise content management (ECM) market through early-stage digitization programs.
Cloud deployment held a 79.41% share in 2025 and ranked as the fastest-growing mode at a 21.24% CAGR, underscoring how firmly the Singapore enterprise content management (ECM) market has aligned around cloud-first buying. This is not a split market between old and new architectures, because most new investments are now expanding cloud use rather than testing it for the first time. The fact that cloud is both the largest and fastest-growing segment suggests that enterprise confidence in this model has already moved beyond the pilot stage. For many buyers, cloud is now the default architecture for new content programs in the Singapore enterprise content management (ECM) market.
That momentum is supported by local infrastructure expansion and stronger confidence in governed hosting environments. Microsoft's multiyear infrastructure commitment in Singapore is reinforcing the capacity needed for sovereign and AI-ready workloads. Hybrid deployment still held a practical role among large BFSI institutions and government agencies that needed tighter control over selected content classes, while on-premises systems remained necessary in limited use cases involving sensitive or classified material. Even so, the longer-term direction still points toward additional migration away from traditional deployments, which should keep the cloud at the center of the Singapore enterprise content management (ECM) market.
Complete Report Scope:
- By Solution Type
- Document Management
- Records Management
- Workflow and Business Process Management
- Case Management
- Digital Asset Management
- Web Content Management
- Other Solutions
- By Deployment Mode
- On-Premises
- Cloud
- Hybrid
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By End-User Industry
- BFSI
- Government and Public Sector
- Healthcare
- IT and Telecommunications
- Manufacturing
- Retail
- Media and Entertainment
- Education
- Energy and Utilities
- Other End-User Industries
List of Companies Covered in this Report:
- Microsoft Corporation
- OpenText Corporation
- IBM Corporation
- Hyland Software, Inc.
- Oracle Corporation
- Box, Inc.
- Adobe Inc.
- Xerox Holdings Corporation
- M-Files Corporation
- Alfresco Software, Inc.
- DocuWare GmbH
- Datamatics Global Services Limited
- Newgen Software Technologies Limited
- Laserfiche, Inc.
- Yonyou Singapore
- Fujifilm Business Innovation Corp
- KYOCERA Document Solutions Singapore Pte. Ltd
- KnowledgeLake, Inc.
- iManage, LLC
- Egnyte, Inc.
- Objective Corporation Limited
- Zoho Corporation Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI Copilots Embedded in Content Workflows
- 4.2.2 Data Residency and Sovereignty Requirements
- 4.2.3 Zero Trust Content Access Controls
- 4.2.4 Cloud Migration of Legacy Repositories
- 4.2.5 Industry-Specific Compliance Automation
- 4.2.6 No-Code Workflow Orchestration Demand
- 4.3 Market Restraints
- 4.3.1 High Integration Complexity With Legacy Systems
- 4.3.2 User Resistance to Content Governance Discipline
- 4.3.3 Vendor Lock-In Concerns in Platform Suites
- 4.3.4 Skills Gap in Intelligent Content Operations
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Solution Type
- 5.1.1 Document Management
- 5.1.2 Records Management
- 5.1.3 Workflow and Business Process Management
- 5.1.4 Case Management
- 5.1.5 Digital Asset Management
- 5.1.6 Web Content Management
- 5.1.7 Other Solutions
- 5.2 By Deployment Mode
- 5.2.1 On-Premises
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Enterprise Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 Government and Public Sector
- 5.4.3 Healthcare
- 5.4.4 IT and Telecommunications
- 5.4.5 Manufacturing
- 5.4.6 Retail
- 5.4.7 Media and Entertainment
- 5.4.8 Education
- 5.4.9 Energy and Utilities
- 5.4.10 Other End-User Industries
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 OpenText Corporation
- 6.4.3 IBM Corporation
- 6.4.4 Hyland Software, Inc.
- 6.4.5 Oracle Corporation
- 6.4.6 Box, Inc.
- 6.4.7 Adobe Inc.
- 6.4.8 Xerox Holdings Corporation
- 6.4.9 M-Files Corporation
- 6.4.10 Alfresco Software, Inc.
- 6.4.11 DocuWare GmbH
- 6.4.12 Datamatics Global Services Limited
- 6.4.13 Newgen Software Technologies Limited
- 6.4.14 Laserfiche, Inc.
- 6.4.15 Yonyou Singapore
- 6.4.16 Fujifilm Business Innovation Corp
- 6.4.17 KYOCERA Document Solutions Singapore Pte. Ltd
- 6.4.18 KnowledgeLake, Inc.
- 6.4.19 iManage, LLC
- 6.4.20 Egnyte, Inc.
- 6.4.21 Objective Corporation Limited
- 6.4.22 Zoho Corporation Pvt. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


