

|
시장보고서
상품코드
2118859
의사결정 인텔리전스 소프트웨어 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Decision Intelligence Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
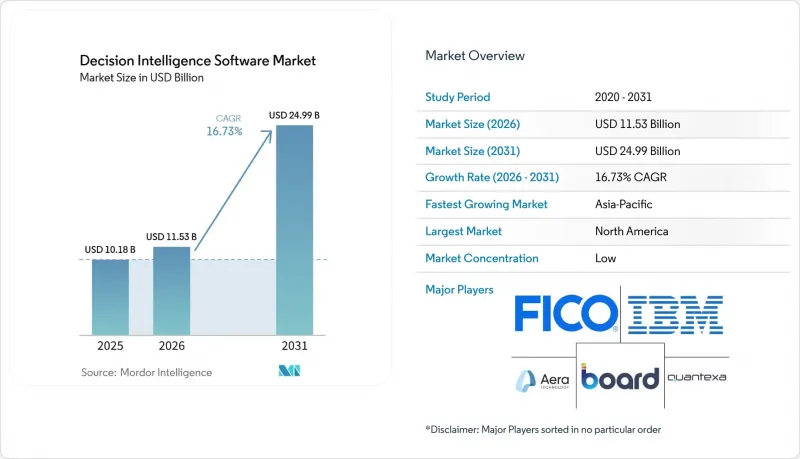
에 의하면, 의사결정 인텔리전스 소프트웨어 시장 규모는 2025년 101억 8,000만 달러로 평가되었고, 2026년 115억 3,000만 달러에서 2031년까지 249억 9,000만 달러로 확대될 전망이며, 2026-2031년 CAGR 16.73%를 나타낼 것으로 예측됩니다.
본 보고서는 제공 형태별(소프트웨어 및 서비스), 의사결정 유형별(지원형 의사결정 지원 등), 도입 모델별(클라우드, 하이브리드, 온프레미스), 업무 기능별(재무 및 회계, 마케팅 및 영업 등), 기업 규모별(대기업 등), 최종 사용자별(BFSI 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 의사결정 인텔리전스 소프트웨어 시장 동향 및 인사이트
기업 내 AI 및 머신러닝 도입
기업의 AI 투자는 시범 단계를 넘어, 모델의 출력을 거버넌스가 확립된 감사 가능한 의사 결정으로 변환하는 플랫폼에 대한 수요를 견인하고 있습니다. 조직에는 고객, 운영 및 위험 관련 워크플로우 전반에 걸쳐 AI가 활용될 때 정책을 일관되게 적용할 수 있는 도구가 필요합니다. 또한, 기술 역량 격차의 존재는 비즈니스 사용자의 기술적 부담을 줄여주는 벤더 관리형 플랫폼을 뒷받침하고 있습니다. IBM은 정책 문구를 감사 가능한 의사결정 흐름으로 변환하는 자연어 처리 기반의 ‘Decision Assistant’를 도입하여, 벤더들이 이러한 요구 사항을 어떻게 충족하고 있는지 보여주고 있습니다. 따라서 의사결정 인텔리전스 소프트웨어 시장에서는 단독 머신러닝 도구보다 도입 지원과 명확한 거버넌스를 결합한 플랫폼이 선호되고 있습니다. 이러한 추세는 감독 기능을 약화시키지 않으면서 의사결정 로직에 대한 접근을 가능하게 하는 공급업체를 뒷받침합니다.
실시간 데이터 기반 의사결정에 대한 수요
조직에서는 지연이 따르는 보고 주기가 아닌, 실시간 데이터를 기반으로 한 의사결정을 추구하는 경향이 강해지고 있습니다. 이는 신용, 부정, 재고, 고객 서비스와 관련된 의사결정을 신속하고 일관되게 수행해야 하는 경우에 특히 중요합니다. Provenir사의 보고서에 따르면, 조사 대상 금융 기관의 60%가 2026년의 주요 투자 계획 분야로 AI와 의사결정 인텔리전스를 꼽았습니다. 실시간 시스템은 수동 검토가 필요해지기 전에 최신 신호를 처리하고 정의된 정책을 적용할 수 있습니다. 또한 은행은 감독 당국의 심사를 위해 명확한 의사결정 기록을 필요로 하므로, 속도와 문서화는 동등하게 중요합니다. 이러한 수요 증가로 인해 금융 서비스, 공급망, 디지털 커머스 분야에서 거버넌스가 확보된 실행 도구의 역할이 강화되고 있습니다.
데이터 보안, 개인정보 보호 및 데이터 주권에 대한 우려
기밀 정보의 저장 및 처리를 제한하는 관할권에서는 데이터 주권이 조달 요건으로 자리 잡고 있습니다. EU AI법은 2026년 8월부터 고위험 AI 시스템에 적용되며, 이러한 시스템에 대한 데이터 거버넌스 의무를 규정하고 있습니다. 이러한 요건으로 인해 조직이나 국경을 넘어 개인 데이터가 이동하는 데 의존하는 프로젝트가 지연될 가능성이 있습니다. 영국 국세관세청(HM Revenue and Customs)은 주권 데이터 및 AI 혁신을 위한 1억 7,500만 파운드(2억 2,100만 달러) 규모의 계약에서 Quantexa를 선정했습니다. 이 계약은 공공 부문 조달 담당자들이 공유형 클라우드 서비스보다는 국내에서 완전히 운영되는 시스템을 선호할 가능성이 있음을 보여줍니다. 따라서 주권적 도입 역량을 갖춘 공급업체는 멀티테넌트형 아키텍처를 고려하지 않을 수 있는 조달 담당자들에게 서비스를 제공할 수 있습니다.
부문 분석
2025년, 소프트웨어는 의사결정 인텔리전스 소프트웨어 시장 점유율의 69.74%를 차지한 것으로 평가되었으며, 이는 모델링, 추론, 거버넌스 및 성과 추적을 결합한 플랫폼에 대한 수요를 반영합니다. 통합 플랫폼은 조직이 의사결정 규칙과 모델 버전을 단일 관리 환경에서 유지할 수 있도록 지원합니다. 이러한 구조는 여러 포인트 제품을 조합하여 사용할 때 발생할 수 있는 설명 책임의 공백을 줄여줍니다. FICO, SAS, IBM, Quantexa 및 Aera Technology는 2025-2026년 생성형 AI 및 에이전트 기능을 도입하여 플랫폼의 기능을 확장했습니다. 이러한 플랫폼은 명시적 의사결정 모델, AI를 통한 기능 확장 및 운영 거버넌스를 통합하도록 설계되었습니다. 의사결정 인텔리전스 소프트웨어 시장에서는 정책, 실행 및 기록을 위한 공통 소프트웨어 계층이 계속해서 중시되고 있습니다. 이러한 요구 사항은 대규모 기업 도입에서 소프트웨어 주도형 비즈니스 모델을 뒷받침하고 있습니다.
구매자들이 통합, 맞춤형 모델 및 관리형 거버넌스에 대한 지원을 요구하는 가운데, 서비스 시장은 2031년까지 연평균 성장률(CAGR) 17.91%로 확대될 것으로 예측됩니다. 많은 조직에서는 이러한 기능을 사내에서 구축하고 유지 관리할 충분한 전문 인력을 확보하지 못하고 있습니다. 서비스 제공업체는 데이터 준비, 워크플로 설계, 테스트 및 도입 후 지속적인 변경을 지원할 수 있습니다. Sendero Consulting은 2026년 4월, 에너지, 제조 및 소비재 부문의 고객을 지원하기 위해 Aera Technology와의 제휴를 발표했습니다. 노코드 기능을 통해 비즈니스 사용자가 기본적인 의사결정 로직을 직접 구축할 수 있게 되므로, 도입 작업의 일부가 경감될 가능성이 있습니다. 그러나 고객이 복잡한 통합이나 산업별 거버넌스를 필요로 하는 의사결정 인텔리전스 소프트웨어 시장에서는 서비스가 여전히 중요한 역할을 합니다. 소프트웨어 도입에는 지속적인 설정 및 운영 지원이 필요한 경우가 많기 때문에 이 두 가지 제공 형태는 계속해서 밀접하게 연관되어 있습니다.
2025년, 의사결정 인텔리전스 소프트웨어 시장에서 ‘지원형 의사결정 지원’이 38.42%의 점유율을 차지했습니다. 이는 인간의 판단을 지원하는 추천 엔진이나 대시보드가 널리 활용되고 있음을 반영합니다. 많은 조직에서는 여전히 인적 점검 단계를 마련하여 영향력이 큰 의사결정에 대한 최종 확인을 수행하고 있습니다. 이러한 접근 방식을 통해 사용자는 선택지를 검토하고, 가정을 검증하며, 필요에 따라 권장 사항을 수정할 수 있습니다. 이는 특히 비즈니스에서 더 깊은 인사이트가 필요하거나, 실행을 위임할 준비가 되어 있지 않은 경우에 널리 정착되어 있습니다. 재무 리스크 및 공급망 담당 팀은 속도와 관리 모두를 필요로 하는 상충 관계의 판단에 있어 확장형 의사결정 도구를 도입하고 있습니다. 이러한 도구는 선택지를 제시하면서도 최종 판단은 책임 있는 직원에게 맡길 수 있습니다. 의사결정 인텔리전스 소프트웨어 시장에서 이 부문은 기존 거버넌스 모델 내에서 AI를 도입하기 위한 실용적인 수단으로 자리 잡고 있습니다.
기업들이 정의된 업무 활동에 AI 에이전트를 활용함에 따라, 자율형 의사결정 자동화는 2031년까지 연평균 성장률(CAGR) 17.64%로 확대될 것으로 예측됩니다. 이러한 시스템은 개별 사안마다 별도의 승인을 받지 않고도 발주, 가격 조정, 규정 준수 경보의 에스컬레이션을 수행할 수 있습니다. 운영 모델은 명확한 의사 결정 권한, 에스컬레이션 절차 및 모니터링 관리에 의존합니다. ISO/IEC 42001은 규제 대상 도입 환경에서 거버넌스를 지원할 수 있는 AI 관리 시스템 프레임워크를 제공합니다. 자율적인 의사결정이 어떻게 설계, 적용 및 검토되는지를 문서화할 수 있는 공급업체는 기밀성이 높은 이용 사례에서 더 확고한 입지를 차지하고 있습니다. 도입의 성패는 조직이 기술적 역량과 동일한 속도로 거버넌스를 확대할 수 있는지 여부에 달려 있습니다. 의사 결정 인텔리전스 소프트웨어 시장에서는 예외 사항이나 정책 변경에 대해 앞으로도 인간의 감독이 계속 필요할 것입니다.
지역별 분석
북미는 대기업, AI 도입 경험이 풍부한 구매자, 그리고 집중된 공급업체 생태계의 뒷받침을 받아 2025년 의사결정 인텔리전스 소프트웨어 시장에서 31.56%의 점유율을 차지했습니다. 미국은 BFSI(은행 및 금융 및 보험), 헬스케어, 기술 분야의 지역 수요 대부분을 주도하고 있습니다. AT&T는 2026년 7월, ‘H2O AI Super Agent’를 고객 경험, 사기 방지, 현장 업무 및 조사 워크플로우에 도입했습니다. 이 회사에 따르면, 이 시스템은 하루에 450억 개의 토큰을 처리하며 최대 90%의 비용 절감을 달성했다고 합니다. 또한, 이 지역에서는 NIST AI 위험 관리 프레임워크를 통해 AI 위험 관리를 위한 지침이 확립되어 있습니다. 캐나다는 공공 부문의 디지털 전환 요구와 관련하여 주권적 의사결정의 두 번째 거점으로 부상하고 있습니다.
아시아태평양은 중국, 인도, 일본, 한국 및 동남아시아의 디지털 전환에 힘입어 2031년까지 연평균 성장률(CAGR) 18.21%로 확대될 것으로 예측됩니다. 중국은 2026년 정부 활동 계획에서 AI 에이전트를 국가 우선 과제로 설정하고, 2027년까지 기업 내 AI 에이전트 도입률을 70% 이상으로 끌어올리는 것을 목표로 하고 있습니다. 중국 지휘통제학회의 추산에 따르면, 중국의 기업용 AI 에이전트 시장 규모는 2025년에 212억 위안(30억 달러)에 달했습니다. 동 학회는 2026년에는 449억 위안(62억 달러)에 이를 것으로 예측했습니다. 같은 출처에 따르면, 중국 제조업 분야의 AI 도입률은 2024년 9.6%에서 2025년에는 47.5%로 상승했습니다. 인도, 한국, 동남아시아에서의 ‘클라우드 퍼스트’ 도입은 구매자가 기존 시스템과의 통합에 따른 제약 중 일부를 피하는 데 도움이 됩니다.
2025년 의사결정 인텔리전스 소프트웨어 시장에서 유럽은 큰 점유율을 차지했으며, 독일, 영국, 프랑스가 주요 도입 거점으로 자리 잡고 있습니다. Bitkom의 보고서에 따르면, 직원 20명 이상의 독일 기업에서 AI 이용률은 2025년 17%에서 2026년 41%로 상승했습니다. Quantexa가 영국 국세청(HM Revenue and Customs)과 체결한 1억 7,500만 파운드(2억 2,100만 달러 상당) 규모의 계약은 영국 내 국가 데이터 및 AI 시스템에 대한 수요를 반영하고 있습니다. EU AI법은 지역 전역의 고위험 용도에 대해 명확한 거버넌스 요건을 추가하고 있습니다. 중동 및 아프리카은 아직 초기 단계에 있지만, 사우디아라비아와 아랍에미리트(UAE)의 공공 투자를 통해 발전하고 있습니다. 남미에서는 신용 심사 플랫폼을 이용하는 은행과, 공급망 및 수확량 결정에 AI를 활용하는 농업 관련 기업들 수요가 나타나고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the decision intelligence software market size is projected to expand from USD 10.18 billion in 2025 and USD 11.53 billion in 2026 to USD 24.99 billion by 2031, registering a CAGR of 16.73% between 2026 and 2031.
This report is Segmented by Offering (Software, and Services), Decision Type (Assisted Decision Support, and More), Deployment Model (Cloud, Hybrid, and On-Premises), Business Function (Finance and Accounting, Marketing and Sales, and More), Enterprise Size (Large Enterprises, and More), End Users (BFSI, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Decision Intelligence Software Market Trends and Insights
Enterprise Adoption of AI and Machine Learning
Enterprise AI spending has moved beyond pilots, driving demand for platforms that convert model outputs into governed, auditable decisions. Organizations need tools that can apply policies consistently when AI is used across customer, operational, and risk-related workflows. The skills gap also favors vendor-managed platforms that reduce the technical burden for business users. IBM has introduced a natural-language Decision Assistant that converts policy text into auditable decision flows, showing how vendors are addressing this requirement. The Decision Intelligence Software Market, therefore, favors platforms that combine deployment support with clear governance rather than isolated machine-learning tools. This pattern supports suppliers that can make decision logic accessible without weakening oversight.
Demand for Real-Time Data-Driven Decision-Making
Organizations increasingly require decisions from live data rather than delayed reporting cycles. This is especially important when credit, fraud, inventory, and customer service decisions must be made quickly and consistently. Provenir reported that 60% of surveyed financial institutions identified AI and decision intelligence as their leading planned investment area in 2026. Real-time systems can process current signals and apply defined policies before a manual review becomes necessary. Banks also need clear decision trails for supervisory review, which makes speed and documentation equally important. The resulting demand strengthens the role of governed execution tools in financial services, supply chains, and digital commerce.
Data Security, Privacy, and Sovereignty Concerns
Data sovereignty has become a procurement requirement in jurisdictions that restrict the storage and processing of sensitive information. The EU AI Act applies to high-risk AI systems from August 2026 and establishes data governance duties for those systems. These requirements can delay projects that depend on personal data moving across organizational or national boundaries. HM Revenue and Customs selected Quantexa for a GBP 175 million (USD 221 million) contract to transform sovereign data and AI. The agreement shows that public buyers may prefer nationally contained systems instead of shared cloud services. Suppliers with sovereign deployment capabilities can therefore serve buyers that may not consider a multi-tenant architecture.
Other drivers and restraints analyzed in the detailed report include:
- Cloud Expansion and Scalable Decisioning Infrastructure
- Risk Reduction and Operational Cost Optimization
- Data Fragmentation and Legacy-System Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 69.74% of the Decision Intelligence Software Market share in 2025, reflecting demand for platforms that combine modeling, inference, governance, and outcome tracking. A unified platform helps organizations keep decision rules and model versions in a single, controlled environment. This structure reduces accountability gaps that can arise when multiple point products are assembled. FICO, SAS, IBM, Quantexa, and Aera Technology have expanded platform capabilities with generative AI and agentic functions during 2025 and 2026. Their platforms are designed to combine explicit decision models, AI augmentation, and operational governance. The Decision Intelligence Software Market continues to favor a common software layer for policies, execution, and records. These requirements support software-led commercial models across large enterprise deployments.
Services are projected to expand at a CAGR of 17.91% through 2031 as buyers seek help with integration, custom models, and managed governance. Many organizations cannot hire enough specialists to build and maintain those capabilities internally. Service providers can support data preparation, workflow design, testing, and ongoing changes after implementation. Sendero Consulting announced a partnership with Aera Technology in April 2026 to support clients in the energy, manufacturing, and consumer sectors. No-code functions may reduce some implementation work by allowing business users to build basic decision logic directly. Services will still matter in the Decision Intelligence Software Market, where customers need complex integrations or sector-specific governance. The two offerings remain linked because software adoption frequently requires continued configuration and operational support.
Assisted decision support held 38.42% of the Decision Intelligence Software Market in 2025, reflecting the broad use of recommendation engines and dashboards that support human judgment. Most organizations still use people as a formal checkpoint for high-impact decisions. This approach allows users to examine options, test assumptions, and override recommendations when needed. It is particularly established where the business needs greater insight but is not ready to delegate execution. Financial risk and supply chain teams have adopted augmented decision-making tools for trade-offs that require both speed and control. These tools can generate options while leaving the final action with an accountable employee. The Decision Intelligence Software Market retains this segment as a practical route to adopt AI within existing governance models.
Autonomous decision automation is projected to expand at a CAGR of 17.64% through 2031 as enterprises use AI agents for defined operational actions. These systems can place purchase orders, adjust prices, and escalate compliance alerts without individual approval for every event. The operating model depends on clear decision rights, escalation paths, and monitoring controls. ISO/IEC 42001 provides an AI management system framework that can support governance in regulated deployments. Vendors that can document how autonomous decisions are designed, applied, and reviewed have a stronger position in sensitive use cases. Adoption will depend on whether organizations can extend governance at the same pace as technical capability. The Decision Intelligence Software Market will continue to require human oversight for exceptions and policy changes.
Complete Report Scope:
- By Offering
- Software
- Services
- By Decision Type
- Assisted Decision Support
- Augmented Decision Making
- Autonomous Decision Automation
- By Deployment Model
- Cloud
- Hybrid
- On-Premises
- By Business Function
- Finance and Accounting
- Marketing and Sales
- Operations and Supply Chain
- Human Resources
- Research and Development
- Other Business Functions
- By Enterprise Size
- Large Enterprises
- Small and Mid-sized Enterprises
- By End Users
- IT and Telecommunication
- BFSI
- Automotive and Transportation
- Healthcare and Life Sciences
- Energy and Utilities
- Industrial Manufacturing
- Travel and Hospitality
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 31.56% of the Decision Intelligence Software Market share in 2025, supported by large enterprises, experienced AI buyers, and a concentrated supplier ecosystem. The United States drives much of the regional demand across BFSI, healthcare, and technology. AT&T deployed H2O AI Super Agent in July 2026 across customer experience, fraud prevention, field operations, and research workflows. The company stated that the system processed 45 billion tokens daily and achieved cost reductions of up to 90%. The region also has established guidance for AI risk management through the NIST AI Risk Management Framework. Canada is emerging as a secondary center for sovereign decisioning tied to public-sector digital transformation needs.
Asia-Pacific is projected to expand at a CAGR of 18.21% through 2031, supported by digital transformation in China, India, Japan, South Korea, and Southeast Asia. China identified AI agents as a national priority in its 2026 government work program and targeted enterprise AI agent application penetration above 70% by 2027. The China Command and Control Society estimated that China's enterprise AI agent sector reached CNY 21.2 billion (USD 3.0 billion) in 2025. It projected CNY 44.9 billion (USD 6.2 billion) for 2026. The same source reported that AI adoption in manufacturing in China rose from 9.6% in 2024 to 47.5% in 2025. Cloud-first deployments in India, South Korea, and Southeast Asia can help buyers avoid some legacy integration constraints.
Europe accounted for a significant share of the Decision Intelligence Software Market in 2025, with Germany, the United Kingdom, and France as major adoption centers. Bitkom reported that AI use among German companies with 20 or more employees rose from 17% in 2025 to 41% in 2026. Quantexa's GBP 175 million contract, equivalent to USD 221 million, with HM Revenue and Customs reflects demand for sovereign data and AI systems in the United Kingdom. The EU AI Act adds a clear governance requirement for high-risk applications across the region. The Middle East and Africa are at an earlier stage but are advancing through public investment in Saudi Arabia and the UAE. South America is seeing demand from banks using credit decision platforms and agribusiness organizations using AI for supply chain and yield decisions.
- Quantexa Ltd
- Aera Technology, Inc.
- Fair Isaac Corporation
- Board International S.A.
- Pyramid Analytics BV
- H2O.ai, Inc.
- Provenir, Inc.
- Tellius, Inc.
- Rulex, Inc.
- Pecan AI, Inc.
- Diwo, Inc.
- Peak Technologies Ltd.
- Rainbird Technologies Ltd.
- Sparkling Logic, Inc.
- FlexRule, Inc.
- InRule Technology, Inc.
- Decisions, LLC
- Cogility Software Corporation
- Trisotech, Inc.
- Gurobi Optimization, LLC
- RelationalAI, Inc.
- Domo, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Enterprise Adoption of AI and Machine Learning
- 4.2.2 Demand for Real-Time Data-Driven Decision-Making
- 4.2.3 Cloud Expansion and Scalable Decisioning Infrastructure
- 4.2.4 Risk Reduction and Operational Cost Optimization
- 4.2.5 Agentic Workflows Requiring Governed Decision Execution
- 4.2.6 Decision Provenance and Outcome Feedback Loops
- 4.3 Market Restraints
- 4.3.1 Data Security, Privacy, and Sovereignty Concerns
- 4.3.2 Data Fragmentation and Legacy-System Integration Complexity
- 4.3.3 Difficulty Demonstrating Decision-Level ROI and Accountability
- 4.3.4 Shortage of Decision Architects and Responsible-AI Specialists
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Decision Type
- 5.2.1 Assisted Decision Support
- 5.2.2 Augmented Decision Making
- 5.2.3 Autonomous Decision Automation
- 5.3 By Deployment Model
- 5.3.1 Cloud
- 5.3.2 Hybrid
- 5.3.3 On-Premises
- 5.4 By Business Function
- 5.4.1 Finance and Accounting
- 5.4.2 Marketing and Sales
- 5.4.3 Operations and Supply Chain
- 5.4.4 Human Resources
- 5.4.5 Research and Development
- 5.4.6 Other Business Functions
- 5.5 By Enterprise Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Mid-sized Enterprises
- 5.6 By End Users
- 5.6.1 IT and Telecommunication
- 5.6.2 BFSI
- 5.6.3 Automotive and Transportation
- 5.6.4 Healthcare and Life Sciences
- 5.6.5 Energy and Utilities
- 5.6.6 Industrial Manufacturing
- 5.6.7 Travel and Hospitality
- 5.6.8 Other End Users
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Russia
- 5.7.3.5 Spain
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Southeast Asia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Middle East
- 5.7.5.1.1 Saudi Arabia
- 5.7.5.1.2 United Arab Emirates
- 5.7.5.1.3 Rest of Middle East
- 5.7.5.2 Africa
- 5.7.5.2.1 South Africa
- 5.7.5.2.2 Nigeria
- 5.7.5.2.3 Rest of Africa
- 5.7.5.1 Middle East
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Quantexa Ltd
- 6.4.2 Aera Technology, Inc.
- 6.4.3 Fair Isaac Corporation
- 6.4.4 Board International S.A.
- 6.4.5 Pyramid Analytics BV
- 6.4.6 H2O.ai, Inc.
- 6.4.7 Provenir, Inc.
- 6.4.8 Tellius, Inc.
- 6.4.9 Rulex, Inc.
- 6.4.10 Pecan AI, Inc.
- 6.4.11 Diwo, Inc.
- 6.4.12 Peak Technologies Ltd.
- 6.4.13 Rainbird Technologies Ltd.
- 6.4.14 Sparkling Logic, Inc.
- 6.4.15 FlexRule, Inc.
- 6.4.16 InRule Technology, Inc.
- 6.4.17 Decisions, LLC
- 6.4.18 Cogility Software Corporation
- 6.4.19 Trisotech, Inc.
- 6.4.20 Gurobi Optimization, LLC
- 6.4.21 RelationalAI, Inc.
- 6.4.22 Domo, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


