

|
시장보고서
상품코드
2118905
스페인의 전선 및 케이블 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Spain Wire and Cable - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
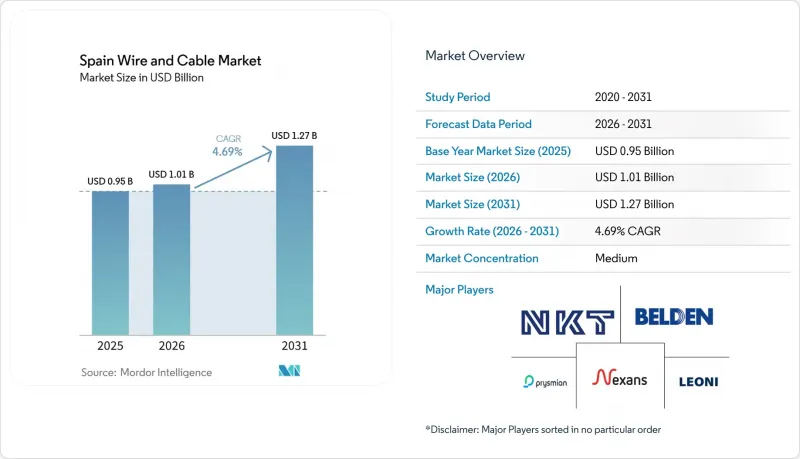
스페인의 전선 및 케이블 시장 규모는 2025년에 9억 5,000만 달러로 평가되었고, 2026년 10억 1,000만 달러에서 2031년까지 12억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.69%를 나타낼 전망입니다.
본 보고서는 전압별(초고압·고압 등), 케이블 유형별(전력 케이블, 광섬유 케이블 등), 도체 재료별(구리 등), 설치 방법별(가공 배선 등), 최종 사용자 산업별(통신·데이터센터, 자동차·모빌리티 등), 절연별(절연형, 비절연형)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
스페인의 전선 및 케이블 시장 동향 및 인사이트
재생에너지 발전 및 송전망 강화
스페인의 전선 및 케이블 시장은 Redeia사가 2025년에 송전망에 15억 5,100만 유로(17억 1,000만 달러)를 투자하기로 결정하였고, 2024년 대비 40.4% 증가함에 따라 투자 확대 국면에 접어들었습니다. 2025-2030년 국가 계획에서는 송전망 지출로 135억 9,000만 유로(149억 5,000만 달러)를 목표로 하고 있으며, 이는 이전 5개년 계획보다 66% 증가한 수치입니다. 유럽투자은행은 2025년에 스페인의 송전망 프로젝트에 19억 유로(20억 9,000만 달러)를 대출해 주었습니다. 2026년 7월의 송전망 갱신 계획에 따르면, 신규 송전선의 연장 거리가 6,700km로 확대되었으며, 에너지 소비량이 많은 대규모 사용자를 위한 송전망 연결 지점이 12% 증가했습니다. 안달루시아와 아라곤을 비롯한 태양광 발전이 활발한 지역에서는 지속적인 열 부하를 견딜 수 있는 XLPE 절연·알루미늄 피복 초고압 제품에 대한 수요가 점점 더 높아지고 있습니다. 이러한 사양의 변화로 인해 송전 프로젝트에 참여하는 공급업체의 경우 1km당 설치 단가가 상승하게 됩니다.
FTTH(Fiber-to-the-Home) 및 5G 네트워크의 확대
스페인의 전선 및 케이블 시장은 2026년 3월 기준 1,800만 회선 이상의 가동 중인 FTTH 회선의 혜택을 받고 있으며, 이는 고정 광대역 연결의 91% 이상을 차지합니다. PremiumFiber는 MasOrange, Vodafone Spain, GIC의 합작 투자사로 2025년 12월에 영업을 시작했으며, 1,200만 명 이상의 FTTH 가입자를 확보하고 있습니다. 이 구조에서는 광섬유 인프라를 각 사업자가 개별적으로 중복 구축하는 네트워크가 아닌, 공유되는 도매 자산으로 취급합니다. 이러한 접근 방식을 통해 사업자가 공통 경로에 용량을 추가할 때, 광섬유 수가 많고 직경이 작은 어셈블리가 유리하게 작용할 가능성이 있습니다. 이러한 제품은 단순한 액세스 구축에 사용되는 기존의 단일 모드 케이블보다 더 높은 가치를 기대할 수 있습니다. 또한, 5G 백홀의 확대도 마드리드, 바르셀로나, 발렌시아 및 기타 인구 밀집 도시권에서의 광섬유 경로 수요를 뒷받침하고 있습니다.
구리와 알루미늄의 가격 변동
구리와 알루미늄의 가격 비율은 2026년 1월에 4.3배에 달했으며, 6월 하순에도 4.2배 전후로 유지되었습니다. 이 수준은 케이블 구매자가 일반적으로 자재 선택을 재검토하는 3.5배-4.0배 범위를 상회합니다. 프리즘(Prismian)사의 보고서에 따르면, 해당사의 케이블에 포함된 알루미늄의 중량 비율은 약 40%를 차지하며, 지난 5년간 3% 상승했습니다. 소재 대체가 진행되면 케이블의 물리적 출하량이 안정적이라 하더라도 구리를 많이 사용하는 제품의 수익이 감소할 가능성이 있습니다. 또한, 스페인 제조업체들은 알루미늄 합금 도체에 대응하기 위해 연선 라인과 어닐링 라인을 개조하는 데 드는 비용 문제에도 직면해 있습니다. 소규모 국내 제조업체들은 가격 측면의 압박을 감수하지 않고서는 이러한 투자 비용을 감당하는 데 어려움을 겪을 가능성이 있습니다.
부문별 분석
2025년, 저전압 케이블은 주택용 배선, 상업 시설의 인테리어 공사, 기계용 배선 및 전기차(EV) 충전용 배전 회로 수요에 힘입어 부문 총 매출의 42.11%를 차지했습니다. 스페인의 전선 및 케이블 시장은 일상적인 전기 활동의 가장 광범위한 기반을 뒷받침하고 있습니다. 주택 프로젝트에는 건축용 전선이, 상업시설에는 전력, 제어 및 안전 관련 배선이 필요합니다. 산업용 고객은 기계, 내부 배전 및 개보수 공사에 동일한 전압 수준을 사용합니다. 이러한 다양한 용도로 인해 이 부문은 단일 프로젝트 유형에 대한 의존도가 낮습니다. 중전압 케이블은 변전소와 산업 단지, 물류 거점, 대규모 상업시설 및 재생에너지 집전 네트워크를 연결합니다. 발레아레스 제도에서는 송전망 계획의 일환으로 11억 6,900만 유로(12억 9,000만 달러)가 배정되어, 섬의 송전망 강화를 위한 중전압 장비 조달을 지원하고 있습니다. 섬 지역의 프로젝트는 본토의 주택 건설 활동에 대한 의존도가 낮은 수요를 창출하고 있습니다.
초고압 및 고압 케이블은 2031년까지 연평균 성장률(CAGR) 5.12%를 나타낼 것으로 예측되며, 이는 전압 분류 중 가장 빠르게 성장하는 부문이 될 것입니다. Redeia사는 2025년에 송전망 정비 및 강화에 14억 2,400만 유로(15억 7,000만 달러)를 투자했습니다. 스페인의 이 전압 등급 전선 및 케이블 시장 규모는 2030년까지 계획된 6,700km의 송전망 확장의 혜택을 받고 있습니다. 비스케이 만의 HVDC(고전압 직류) 송전선은 총 길이 300km, 400kV의 해저 케이블 시스템을 통해 스페인의 가티카와 프랑스의 큐브네즈를 연결합니다. 이 송전선은 2028년에 가동을 시작할 예정입니다. 이러한 공사에는 특수한 직류 케이블용 복합재료와 전용 해저 매설 능력이 필요합니다. 이러한 요건을 충족할 수 있는 업체는 전 세계적으로 극소수에 불과합니다. 이로 인해 저전압 부문과는 다른 경쟁 환경이 형성되고 있습니다.
2025년, 전력 케이블은 전체 부문 매출의 33.12%를 차지했으며, 가정용 회로부터 대규모 송전 시스템에 이르기까지 폭넓은 용도로 활용되었습니다. 모든 전압 범위에서 중요한 역할을 수행하고 있기 때문에 전력 케이블은 케이블 유형별 최대 카테고리가 되었습니다. 수요는 신규 설치, 유지보수 작업 및 교체 수요에서 발생하고 있습니다. 전력 회사는 네트워크 구축을 위해 대량을 구매하고 있습니다. 건설 업계의 사용자들은 건물 및 상업시설용 제품을 필요로 합니다. 재생에너지 프로젝트에서는 집전, 배전 및 연결용 케이블이 필요합니다. 이처럼 폭넓은 용도가 있기 때문에 전력 케이블은 해당 부문의 총 매출에서 중심적인 위치를 계속 차지하고 있습니다. 신호·제어 제품은 산업 자동화 및 빌딩 관리 시스템을 뒷받침하고 있습니다.
광섬유 케이블은 광대역 및 데이터센터 인프라에 힘입어 2031년까지 연평균 성장률(CAGR) 6.11%로 확대될 것으로 예측됩니다. 2026년 3월 기준으로, 가동 중인 FTTH 회선 수는 1,800만 회선을 돌파했습니다. PremiumFiber는 1,200만 건 이상의 건물을 커버하는 것에서 시작하여, 도매 수요에 대응하기 위해 지속적으로 덕트 용량을 확충하고 있습니다. 네트워크 공유 계약으로 인해 공동 인프라의 용량 증설이 필요해질 경우, 케이블 추가 구매로 이어질 가능성이 있습니다. 광섬유가 구리선 기반의 동축 광대역 설계를 대체함에 따라 동축 케이블 및 데이터 케이블 시장 점유율은 계속해서 하락하고 있습니다. 데이터센터에서는 일반적인 FTTH의 성능 요구 사항을 뛰어넘는 광섬유 수가 많고 콤팩트한 광 어셈블리가 사용되고 있습니다. 이로 인해 통신 및 데이터센터 분야에서 더 높은 부가가치를 지닌 광케이블 카테고리가 형성되고 있습니다. 제품 구성의 변화는 스페인 전선 및 케이블 시장에서 디지털 인프라의 중요성을 점점 더 잘 반영하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the Spain wire and cable market size was valued at USD 0.95 billion in 2025 and is estimated to grow from USD 1.01 billion in 2026 to reach USD 1.27 billion by 2031, at a CAGR of 4.69% during the forecast period (2026-2031).
This report is Segmented by Voltage (Extra- and High-Voltage, and More), Cable Type (Power Cable, Fiber-Optic Cable, and More), Conductor Material (Copper, and More), Installation (Overhead, and More), End-User Vertical (Telecommunications and Data Centers, Automotive and Mobility, and More), and Insulation (Insulated, and Non-Insulated). The Market Forecasts are Provided in Terms of Value (USD).
Spain Wire and Cable Market Trends and Insights
Renewable Generation and Grid Reinforcement
The Spain wire and cable market entered a higher investment cycle as Redeia committed EUR 1.551 billion (USD 1.71 billion) to the transmission grid in 2025, a 40.4% increase from 2024. The national 2025-2030 plan targets EUR 13.59 billion (USD 14.95 billion) in transmission spending, 66% above the prior five-year plan. The European Investment Bank financed EUR 1.9 billion (USD 2.09 billion) in Spanish grid projects during 2025. The July 2026 network update extended the plan to 6,700 km of new transmission lines and increased the number of grid positions for large energy-intensive users by 12%. Solar-heavy areas, including Andalusia and Aragon, increasingly require XLPE-insulated, aluminum-sheathed extra-high-voltage products that can withstand sustained thermal loads. This specification shift raises the value of each installed kilometer for suppliers serving transmission projects.
Fiber-to-the-Home and 5G Network Expansion
The Spain wire and cable market benefits from more than 18 million active FTTH lines in March 2026, representing over 91% of fixed broadband connections. PremiumFiber began operating in December 2025 as a joint venture of MasOrange, Vodafone Spain, and GIC, with coverage of more than 12 million FTTH premises. The structure treats fiber infrastructure as a shared wholesale asset rather than a network duplicated by every operator. This approach can favor high-fiber-count, small-diameter assemblies when operators add capacity to common routes. Such products can command a higher value than conventional single-mode cable used in simple access deployment. The expansion of 5G backhaul also supports demand for fiber routes in Madrid, Barcelona, Valencia, and other densely populated urban areas.
Copper and Aluminum Price Volatility
The copper-to-aluminum price ratio reached 4.3x in January 2026 and remained close to 4.2x in late June. This level exceeded the 3.5x-4.0x range at which cable buyers typically reconsider material choices. Prysmian reported that aluminum accounted for around 40% of its cable content by weight, up 3 percentage points over the past 5 years. Material substitution can reduce revenue from copper-intensive products, even when physical cable volumes remain stable. Spanish manufacturers also face costs related to adapting stranding and annealing lines for aluminum alloy conductors. Smaller domestic producers may struggle to absorb these investments without accepting pricing pressure.
Other drivers and restraints analyzed in the detailed report include:
- Electrification of Transport and Charging Infrastructure
- Data Center and Industrial Digitalization Investments
- Permitting Delays and Grid Congestion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Low-voltage cables held 42.11% of total sector revenue in 2025, supported by residential wiring, commercial fit-outs, machine wiring, and EV charging distribution circuits. The Spain wire and cable market serves the broadest base of everyday electrical activity. Residential projects require building wire, while commercial facilities need power, control, and safety-related wiring. Industrial customers use the same voltage tier for machinery, internal distribution, and retrofit work. These varied uses make the category less dependent on a single project type. Medium-voltage cables connect substations with industrial parks, logistics sites, large commercial facilities, and renewable collection networks. The Balearic Islands' allocation of EUR 1.169 billion (USD 1.29 billion) under the grid plan supports the procurement of medium-voltage equipment for island reinforcement. Island projects offer demand that is less tied to mainland residential construction activity.
Extra- and high-voltage cables are projected to record a 5.12% CAGR through 2031, making this the fastest-growing voltage tier. Redeia invested EUR 1.424 billion (USD 1.57 billion) in transmission grid development and reinforcement during 2025. The Spain wire and cable market size for this tier benefits from the planned 6,700 km network expansion through 2030. The Bay of Biscay HVDC link will connect Gatika in Spain with Cubnezais in France through a 300 km, 400 kV submarine cable system. The link is scheduled to become operational in 2028. Such work requires specialized DC cable compounds and dedicated subsea installation capacity. Only a limited group of global manufacturers can fulfill those requirements. This creates a different competitive setting from the low-voltage segment.
Power cables accounted for 33.12% of total sector revenue in 2025 and served applications from household circuits to major transmission systems. Their role across the voltage range makes them the largest cable-type category. Demand comes from new installations, maintenance work, and replacement needs. Utilities purchase large volumes for network development. Construction users need products for buildings and commercial facilities. Renewable projects require cables for collection, distribution, and connection. This wide range of uses keeps power cables central to the sector's total revenue. Signal and control products support industrial automation and building management systems.
Fiber-optic cables are forecast to expand at a 6.11% CAGR through 2031, supported by broadband and data center infrastructure. The active FTTH base exceeded 18 million lines in March 2026. PremiumFiber began with coverage of more than 12 million premises and continues to add duct capacity for wholesale demand. Network-sharing agreements can lead to added cable purchases when joint infrastructure needs more capacity. Coaxial and data cables continue to lose share as fiber replaces copper-based coaxial broadband designs. Data centers use high-fiber-count and compact optical assemblies that exceed typical FTTH performance requirements. This creates a higher-value optical category within the telecommunications and data centers vertical. The type mix increasingly reflects the importance of digital infrastructure in the Spain wire and cable market.
Complete Report Scope:
- By Voltage
- Extra- and High-Voltage (Greater Than 35 kV)
- Medium-Voltage (1-35 kV)
- Low-Voltage (Less Than 1 kV)
- By Cable Type
- Power Cable
- Fiber-Optic Cable
- Signal and Control Cable
- Coaxial and Data Cable
- By Conductor Material
- Copper
- Aluminum
- Optical Glass / Polymer
- By Installation
- Overhead
- Underground
- Submarine
- By End-User Vertical
- Residential Construction
- Commercial Construction
- Power Infrastructure (Utilities and Renewables)
- Telecommunications and Data Centers
- Oil and Gas and Petrochemicals
- Automotive and Mobility
- Industrial Manufacturing
- By Insulation
- Insulated
- Non-Insulated
List of Companies Covered in this Report:
- Prysmian Cables Spain, S.A.U.
- Nexans
- Top Cable, S.A.
- Miguelez, S.L.
- LA FARGA YOURCOPPERSOLUTIONS, S.A.
- NKT A/S
- Sumitomo Electric Bordnetze SE
- Telefonica de Espana, S.A.U.
- Cervi
- RCT Cables
- Cabelte
- Brugg Cables
- LAPP Espana
- Belden Inc.
- CommScope, Inc.
- TE Connectivity Ltd.
- Amphenol Corporation
- Leoni AG
- Hellenic Cables S.A.
- Tele-Fonika Kable S.A.
- Elsewedy Electric S.A.E.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Renewable Generation and Grid Reinforcement
- 4.2.2 Fiber-to-the-Home and 5G Network Expansion
- 4.2.3 Electrification of Transport and Charging Infrastructure
- 4.2.4 Data Center and Industrial Digitalization Investments
- 4.2.5 EU-Funded Cross-Border and Island Interconnections
- 4.2.6 Premiumization Toward Fire-Safe and Low-Smoke Cables
- 4.3 Market Restraints
- 4.3.1 Copper and Aluminum Price Volatility
- 4.3.2 Permitting Delays and Grid Congestion
- 4.3.3 Construction Cyclicality and Residential Demand Normalization
- 4.3.4 Skilled Installation Capacity Constraints
- 4.4 Industry Supply Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 The Impact of Macroeconomic Factors on the Market
- 4.8 Investment Analysis
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Voltage
- 5.1.1 Extra- and High-Voltage (Greater Than 35 kV)
- 5.1.2 Medium-Voltage (1-35 kV)
- 5.1.3 Low-Voltage (Less Than 1 kV)
- 5.2 By Cable Type
- 5.2.1 Power Cable
- 5.2.2 Fiber-Optic Cable
- 5.2.3 Signal and Control Cable
- 5.2.4 Coaxial and Data Cable
- 5.3 By Conductor Material
- 5.3.1 Copper
- 5.3.2 Aluminum
- 5.3.3 Optical Glass / Polymer
- 5.4 By Installation
- 5.4.1 Overhead
- 5.4.2 Underground
- 5.4.3 Submarine
- 5.5 By End-User Vertical
- 5.5.1 Residential Construction
- 5.5.2 Commercial Construction
- 5.5.3 Power Infrastructure (Utilities and Renewables)
- 5.5.4 Telecommunications and Data Centers
- 5.5.5 Oil and Gas and Petrochemicals
- 5.5.6 Automotive and Mobility
- 5.5.7 Industrial Manufacturing
- 5.6 By Insulation
- 5.6.1 Insulated
- 5.6.2 Non-Insulated
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Vendor Positioning Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Prysmian Cables Spain, S.A.U.
- 6.4.2 Nexans
- 6.4.3 Top Cable, S.A.
- 6.4.4 Miguelez, S.L.
- 6.4.5 LA FARGA YOURCOPPERSOLUTIONS, S.A.
- 6.4.6 NKT A/S
- 6.4.7 Sumitomo Electric Bordnetze SE
- 6.4.8 Telefonica de Espana, S.A.U.
- 6.4.9 Cervi
- 6.4.10 RCT Cables
- 6.4.11 Cabelte
- 6.4.12 Brugg Cables
- 6.4.13 LAPP Espana
- 6.4.14 Belden Inc.
- 6.4.15 CommScope, Inc.
- 6.4.16 TE Connectivity Ltd.
- 6.4.17 Amphenol Corporation
- 6.4.18 Leoni AG
- 6.4.19 Hellenic Cables S.A.
- 6.4.20 Tele-Fonika Kable S.A.
- 6.4.21 Elsewedy Electric S.A.E.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


