

|
시장보고서
상품코드
2119151
팽창성 마이크로스피어 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Expandable Microspheres - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
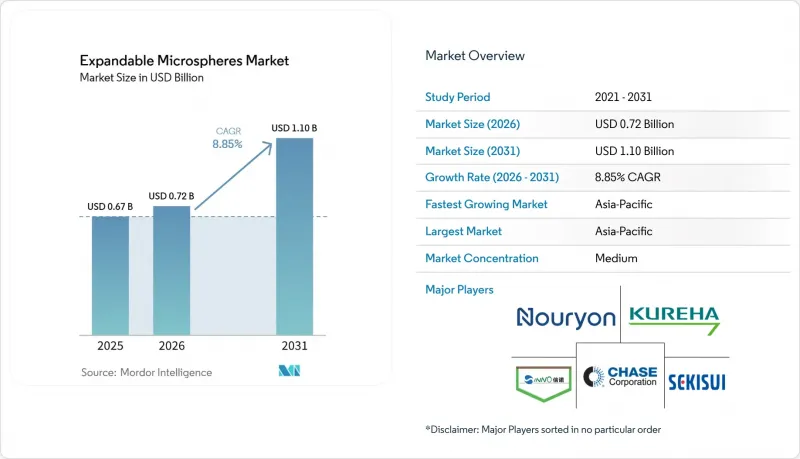
에 의하면, 팽창성 마이크로스피어 시장 규모는 2025년에 6억 7,000만 달러로 평가되었습니다. 2026년 7억 2,000만 달러에서 2031년까지 11억 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 8.85%를 나타낼 전망입니다.
본 보고서는 유형별(건식 및 습식), 폴리머 유형별(폴리아크릴에스테르(PAE), 폴리비닐아세테이트(PVA), 비닐아세테이트-에틸렌(VAE)), 최종 사용자 산업별(자동차, 건설 등),지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 팽창성 마이크로스피어 시장 동향 및 인사이트
경량 폴리머 개질 소재에 대한 수요 증가
제품 경량화에 대한 요구가 기계적 성능을 유지하는 충전제 시스템 수요를 견인하고 있습니다. 팽창성 마이크로스피어는 중량비 기준으로 1%-2%의 사용량으로 부품의 밀도를 최대 40%까지 낮출 수 있습니다. 이러한 효율성 덕분에 제조업체들이 공정을 대폭 변경하지 않고도 경량화를 도모할 수 있는 폴리머 컴파운드에 팽창성 마이크로스피어를 채택하는 사례가 증가하고 있습니다. 미국, 중국, 유럽연합(EU)의 연비 규제는 자동차 부품 경량화의 가치를 더욱 높이고 있습니다. 배터리식 전기차(BEV)의 보급은 특히 배터리 시스템 주변의 조립 부품에서 질량 저감에 대한 압력을 더욱 강화하고 있습니다. 누리온(Nurion)사에 따르면, ‘Expancel HP 92’는 자동차 언더바디 코팅에서 저밀도와 내압성을 동시에 확보하여 이러한 용도의 성능 요건을 충족한다고 합니다.
단열재 및 에너지 절약형 건축자재에서의 채택 확대
에너지 절약형 건축의 발전에 따라, 기존 코팅, 경량 콘크리트, 이음매 재료, 벽 패널에 배합 가능한 단열 첨가제에 대한 수요가 높아지고 있습니다. 발포성 마이크로스피어는 폐쇄 기공 구조를 형성함으로써 열전도율을 낮추고, 운송 중량을 줄일 수 있습니다. 이를 통해 건축자재 제조업체는 건축 시스템 전체를 재설계하지 않고도 단열 성능을 향상시킬 수 있게 됩니다. 개정된 ‘건축물의 에너지 성능에 관한 지침’은 2024년 5월에 발효되어, 유럽연합(EU) 전역의 신축 건물 및 개보수 공사에 대한 요건을 규정하고 있습니다. 이러한 요건으로 인해 단열재에 사용되는 자재의 조달 주기가 장기화될 것으로 예측됩니다. 또한, 팽창성 마이크로스피어 시장은 남아시아 및 동남아시아에서 사용되는 조립식 패널용 팽창성 코팅 및 초박형 단열층 분야에서도 새로운 비즈니스 기회를 모색하고 있습니다.
특수 폴리머 및 발포제 원자재 가격 변동
발포성 마이크로스피어의 생산은 아크릴로니트릴, 메타크릴로니트릴, 그리고 이소부탄 및 이소펜탄과 같은 저비점 탄화수소에 의존하고 있습니다. 이러한 원료는 석유화학제품 가격 변동의 영향을 받지만, 특수 등급 중간체의 생산량은 범용 단량체보다 적은 것이 현실입니다. 니트릴계 원료에 대한 수직 통합을 실시하지 않는 유럽의 수탁 제조업체나 아시아의 소규모 생산자는 범용 원료 가격이 급등할 때 더 큰 이익률 압박에 직면할 가능성이 있습니다. 또한, 공급업체가 안정적인 다년 단위 가격을 제시하지 못할 경우, 가격의 불확실성으로 인해 고객의 인증 절차가 지연될 가능성도 있습니다. 발포성 마이크로스피어 시장은 합성 폴리머 미세 입자에 관한 유럽연합 집행위원회 규정(EU) 2023/2055에 따라 유럽에서 추가적인 규정 준수 비용에 직면해 있습니다. 첫 번째 의무는 2025년 10월 17일에 발효되며, 습식 발포 마이크로스피어 공급업체에게 사용 및 폐기에 관한 정보 제공이 의무화되어 있고, 보고 요건은 2027년까지 단계적으로 도입될 예정입니다.
부문별 분석
2025년 기준, 건식 마이크로스피어는 팽창성 마이크로스피어 시장 점유율의 58.32%를 차지했습니다. 이러한 위상은 압출 성형, 사출 성형, 캘린더 성형과의 호환성을 반영한 것으로, 이러한 공정에서는 유동성이 높은 분말이 기존의 컴파운딩 공정에 적합합니다. 건조 등급은 재료 취급 및 가공 시 용매 관리의 필요성을 제거합니다. 또한, 입고 재료의 사양이 엄격한 용도에서 보다 정밀한 입자 크기 관리를 가능하게 합니다. 오염 관리가 중요한 자동차 및 항공우주 분야의 배합에서는 이러한 일관성이 중시됩니다. 드라이 유형 팽창성 마이크로스피어 시장 규모는 주류 폴리머 가공 설비가 널리 도입되어 있는 점에 힘입고 있습니다. 가공업체는 재료 취급에 따른 변경을 최소화하면서 이러한 등급을 익숙한 워크플로우에 통합할 수 있습니다. 이러한 요인들로 인해 건식 유형은 신뢰할 수 있는 가공 거동이 요구되는 용도에 적합합니다.
습식 마이크로스피어는 유형별 부문 중 가장 빠른 성장률을 기록하며, 2026년부터 2031년까지 연평균 성장률(CAGR) 9.41%를 달성했습니다. 배합 설계자들이 용제형 제품에서 수성 시스템으로 전환함에 따라 수성 코팅 및 접착제 시장이 확대되고 있습니다. 습식 슬러리는 박막에서 더 균일한 팽창을 유도하여 기판 표면에 더 매끄러운 셀 구조를 형성하는 데 도움이 됩니다. 장식용 도료, 섬유, 용지용 코팅은 이러한 표면의 일관성으로부터 이점을 얻고 있습니다. 이 형태는 광범위한 도장 면에 걸쳐 균일한 도포가 요구되는 경우에 특히 적합합니다. 2025년 3월, 누리온(Nurion)사는 인테리어용 장식 도료를 위한 초미세 드라이 등급 마이크로스피어 ‘Expancel XS200’을 출시했습니다. 이번 출시는 표면 마감과 도료의 경량화 모두 중요한 고려 사항인 프리미엄 도료 분야에서 더 미세한 입자 크기가 중요함을 보여줍니다. 미세 입자 제조 능력을 갖추지 못한 제조업체는 고부가가치 장식용 및 특수 도료 용도에서 제약을 겪을 가능성이 있습니다.
지역별 분석
아시아태평양은 2025년에 시장 점유율의 39.65%를 차지했으며, 2026년부터 2031년까지 연평균 성장률(CAGR) 9.66%로 성장할 것으로 전망됩니다. 중국은 대규모 자동차 생산 거점과 전기차의 적극적인 도입을 모두 갖추고 있습니다. 중국의 특수 화학제품 부문에는 표준 등급 용도에서 가격 경쟁을 펼치고 있는 국내 마이크로스피어 제조업체들이 포함되어 있습니다. 인도의 건설 활동은 경량 단열재에 대한 수요를 뒷받침하고 있습니다. 일본과 한국은 기술 개발 및 고등급 제품 생산 거점으로 자리 잡고 있습니다. 마츠모토 유시 제약, 세키스이 화학공업, 크레하 주식회사, 쿠미얀은 고온·고정밀 등급 분야에서 이 지역의 입지를 뒷받침하고 있습니다.
북미와 유럽은 발포성 마이크로스피어 시장 규모에서 각각 2위와 3위를 차지하는 지역입니다. 두 지역 모두 고급 자동차용 인증, 환경 기준, 그리고 건물 개보수 공사에 힘입어 단위당 수요 가치가 높아지고 있습니다. 북미 수요에는 미국 및 캐나다의 자동차용 실링 컴파운드와 건축용 단열 코팅이 포함됩니다. 누리온(Nourion)사는 위스콘신주 그린베이에 ‘엑스팬셀(Expancel)’ 생산 거점을 운영하며, 해당 지역공급을 뒷받침하고 있습니다. 독일, 프랑스, 영국은 자동차 및 건설 용도 분야에서 유럽의 주요 소비 거점입니다. 또한, 유럽공급업체는 REACH 규정에 따른 문서 제출 요건도 충족해야 하며, 이는 확립된 제품 관리 역량을 갖춘 기업에 유리하게 작용합니다.
남미, 중동 및 아프리카는 규모는 작지만 수요가 확대되고 있는 지역입니다. 브라질은 남동부 산업 지대의 자동차 조립 및 건설 활동을 통해 남미 수요를 뒷받침하고 있습니다. 누리온(Nurion)사는 제조 네트워크의 일환으로 브라질에 ‘엑스팬셀(Expancel)’ 생산 체제를 유지하고 있습니다. 중동 및 아프리카에서는 단기적인 수요가 사우디아라비아의 건설 활동과 남아프리카공화국의 자동차 제조 거점에 의해 주도되고 있습니다. 사우디아라비아의 인프라 정비 계획은 경량 건축자재용 첨가제의 조달을 뒷받침하고 있습니다. 남아프리카는 하우텡 주 및 동케이프 주에서의 제조 활동을 통해 자동차용 등급 수요에 기여하고 있습니다. 이 지역들은 모두 더 대규모 제조 시장에 비해 시장 침투도가 여전히 낮기 때문에 공급업체의 투자 여지가 남아 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the expandable microspheres market size was valued at USD 0.67 billion in 2025 and is estimated to grow from USD 0.72 billion in 2026 to reach USD 1.10 billion by 2031, at a CAGR of 8.85% during the forecast period (2026-2031).
This report is Segmented by Type (Dry and Wet), Polymer Type (Polyacrylic Ester (PAE), Polyvinyl Acetate (PVA), and Vinyl Acetate Ethylene (VAE)), End-User Industry (Automotive, Construction, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Expandable Microspheres Market Trends and Insights
Rising Demand for Lightweight Polymer-Modified Materials
The need to reduce product weight is driving demand for filler systems that preserve mechanical performance. Expandable microspheres can reduce part density by up to 40% at use levels of 1% to 2% by weight. This efficiency supports their use in polymer compounds where manufacturers seek lower weight without major process changes. Fuel economy requirements in the United States, China, and the European Union continue to reinforce the value of lighter vehicle components. Battery electric vehicles add further pressure to control mass, particularly in assemblies around battery systems. Nouryon states that Expancel HP 92 supports low density and pressure resistance in automotive underbody coatings, reflecting the performance requirements of these applications.
Growing Adoption in Thermal Insulation and Energy-Efficient Building Materials
Energy-efficient construction is increasing demand for insulation additives that can be incorporated into existing coatings, lightweight concrete, joint compounds, and wall panels. Expandable microspheres create closed-cell air structures that can lower thermal conductivity and reduce transport weight. This allows building material producers to improve thermal performance without redesigning the full construction system. The revised Energy Performance of Buildings Directive entered into force in May 2024 and sets requirements for new buildings and renovation activities across the European Union. These requirements support a longer procurement cycle for materials used in thermal insulation. The expandable microspheres market is also finding opportunities in intumescent coatings and thin thermal layers for prefabricated panels used in South and Southeast Asia.
Volatility in Raw Material Prices for Specialty Polymers and Blowing Agents
Expandable microsphere production depends on acrylonitrile, methacrylonitrile, and low-boiling hydrocarbons such as isobutane and isopentane. These inputs are exposed to petrochemical price movements, while specialty-grade intermediates have lower output than commodity monomers. European contract manufacturers and smaller Asian producers without nitrile feedstock integration can face greater margin pressure during commodity upswings. Price uncertainty can also delay customer qualification work when suppliers cannot provide stable multi-year pricing. The expandable microspheres market faces additional compliance costs in Europe under Commission Regulation (EU) 2023/2055 on synthetic polymer microparticles. The first obligations took effect on October 17, 2025, requiring wet-form microsphere suppliers to provide use and disposal information, with reporting requirements phased through 2027.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Use of Automotive Interior Components for Weight Reduction and NVH Improvement
- Growing Demand for High-Performance and Low-Density Materials in Consumer Goods and Sports Equipment
- Processing and Temperature Limitations During Manufacturing and End-Use Applications
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry-type microspheres held 58.32% of the expandable microspheres market share in 2025. Their position reflects compatibility with extrusion, injection molding, and calendering, where free-flowing powders fit established compounding processes. Dry grades eliminate the need for solvent management during material handling and processing. They also support tighter particle-size control in applications with demanding incoming-material specifications. Automotive and aerospace formulations value this consistency where contamination control is important. The expandable microspheres market size for dry formats is further supported by the wide installed base of mainstream polymer processing equipment. Processors can incorporate these grades into familiar workflows with limited changes to material handling. These factors make dry grades suitable for applications that require dependable processing behavior.
Wet-type microspheres recorded the fastest growth within the type segment, at a 9.41% CAGR from 2026 to 2031. Water-based coatings and adhesives are expanding as formulators shift toward aqueous systems rather than solvent-borne alternatives. Wet slurries can provide more uniform expansion in thin films and help create a smoother cell structure at the substrate surface. Decorative paints, textiles, and paper coatings benefit from this surface consistency. The format is particularly relevant where consistent application across a broad coated surface is required. In March 2025, Nouryon launched Expancel XS200, an extra-small dry-grade microsphere for interior decorative paints. The launch indicates that smaller particle sizes are important in premium coatings, where surface finish and paint weight reduction are both relevant considerations. Producers without small-particle capabilities may face constraints in high-value decorative and specialty coating applications.
Complete Report Scope:
- By Type
- Dry
- Wet
- By Polymer Type
- Polyacrylic Ester (PAE)
- Polyvinyl Acetate (PVA)
- Vinyl Acetate Ethylene (VAE)
- By End-User Industry
- Automotive
- Construction
- Consumer Goods
- Sports and Leisure
- Packaging
- Textile
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 39.65% of the market in 2025 and is forecast to grow at a 9.66% CAGR from 2026 to 2031. China combines a large automotive production base with an active rollout of electric vehicles. Its specialty chemical sector includes domestic microsphere producers that compete on price in standard-grade applications. India's construction activity supports demand for lightweight insulating materials. Japan and South Korea are centers of technology development and advanced-grade production. Matsumoto Yushi-Seiyaku, Sekisui Chemical, KUREHA Corporation, and Kumyang support the region's position in high-temperature and high-precision grades.
North America and Europe are the second- and third-largest geographic markets for expandable microspheres. Both regions have higher value-per-unit demand driven by premium automotive qualifications, environmental standards, and building renovation activity. North American demand includes automotive sealing compounds and construction insulation coatings in the United States and Canada. Nouryon operates an Expancel production facility in Green Bay, Wisconsin, which supports regional supply. Germany, France, and the United Kingdom are key European consumption centers for automotive and construction applications. European suppliers also face REACH documentation requirements, which favor firms with established product stewardship capabilities.
South America, the Middle-East, and Africa are smaller but developing demand areas. Brazil supports South American demand through automotive assembly and construction activity in its southeastern industrial belt. Nouryon maintains Expancel production capabilities in Brazil as part of its manufacturing network. In the Middle-East and Africa, near-term demand is driven by Saudi Arabia's construction activity and South Africa's automotive manufacturing base. Saudi Arabia's infrastructure programs are supporting the procurement of additives for lightweight building materials. South Africa contributes to automotive-grade demand through manufacturing activity in Gauteng and the Eastern Cape. Both regions remain less penetrated than larger manufacturing markets, leaving room for supplier investment.
- Chase Corp.
- Crerax Science and Technology Co. Ltd.
- DONGJIN SEMICHEM CO LTD.
- Hunan Farida Technology Co.,Ltd.
- Kumyang Co. Ltd.
- KUREHA CORPORATION
- Matsumoto Yushi-Seiyaku Co. Ltd.
- Nanjing Chemical Material Corp.
- Nouryon
- Qingdao Sinno Chemical Co.,Ltd
- SEKISUI CHEMICAL CO., LTD.
- Trelleborg
- Waytop Microspheres Co., Ltd
- Zhejiang Joysun Advanced Material Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Lightweight Polymer-Modified Materials
- 4.2.2 Growing Adoption in Thermal Insulation and Energy-Efficient Building Materials
- 4.2.3 Increasing Use in Automotive Interior Components for Weight Reduction and NVH Improvement
- 4.2.4 Growing Demand for High-Performance and Low-Density Materials in Consumer Goods and Sports Equipment
- 4.2.5 Increasing Adoption in Sustainable Manufacturing Through Material and Energy Savings
- 4.3 Market Restraints
- 4.3.1 Volatility in Raw Material Prices for Specialty Polymers and Blowing Agents
- 4.3.2 Processing and Temperature Limitations During Manufacturing and End-Use Applications
- 4.3.3 Competition from Alternative Lightweight Fillers and Chemical Foaming Agents
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Dry
- 5.1.2 Wet
- 5.2 By Polymer Type
- 5.2.1 Polyacrylic Ester (PAE)
- 5.2.2 Polyvinyl Acetate (PVA)
- 5.2.3 Vinyl Acetate Ethylene (VAE)
- 5.3 By End-User Industry
- 5.3.1 Automotive
- 5.3.2 Construction
- 5.3.3 Consumer Goods
- 5.3.4 Sports and Leisure
- 5.3.5 Packaging
- 5.3.6 Textile
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Chase Corp.
- 6.4.2 Crerax Science and Technology Co. Ltd.
- 6.4.3 DONGJIN SEMICHEM CO LTD.
- 6.4.4 Hunan Farida Technology Co.,Ltd.
- 6.4.5 Kumyang Co. Ltd.
- 6.4.6 KUREHA CORPORATION
- 6.4.7 Matsumoto Yushi-Seiyaku Co. Ltd.
- 6.4.8 Nanjing Chemical Material Corp.
- 6.4.9 Nouryon
- 6.4.10 Qingdao Sinno Chemical Co.,Ltd
- 6.4.11 SEKISUI CHEMICAL CO., LTD.
- 6.4.12 Trelleborg
- 6.4.13 Waytop Microspheres Co., Ltd
- 6.4.14 Zhejiang Joysun Advanced Material Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


