|
시장보고서
상품코드
2119250
나트륨 이온 배터리용 경질 탄소 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Sodium-Ion Battery-Grade Hard Carbon - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
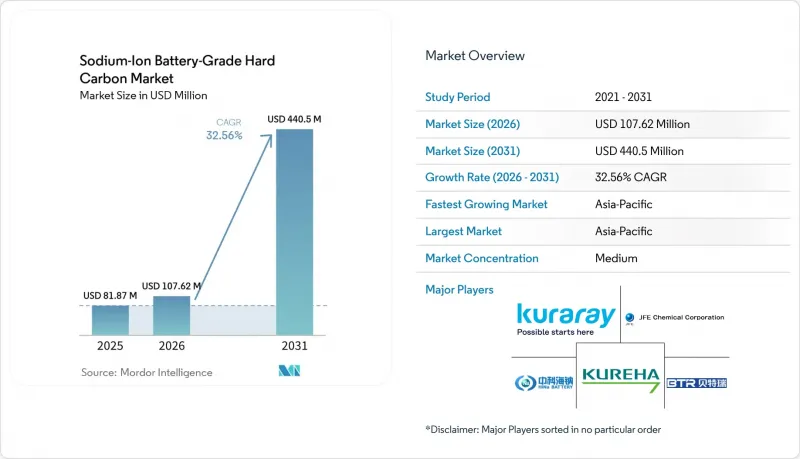
에 의하면, 나트륨 이온 배터리용 경질 탄소 시장 규모는 2025년에 8,187만 달러로 평가되었습니다. 2026년 1억 762만 달러에서 2031년까지 4억 4,050만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 32.56%를 나타낼 전망입니다.
본 보고서는 원료(바이오매스 유래, 기타), 공정 유형(탄화/열분해, 기타), 등급(에너지용 등급, 기타), 용도(에너지 저장 시스템, 기타), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계의 나트륨 이온 배터리용 경질 탄소 시장 동향 및 인사이트
나트륨 이온 배터리의 상용화
나트륨 이온 배터리의 상용화는 나트륨 이온 배터리용 경질 탄소 시장 수요를 직접 견인하는 요인입니다. 국제에너지기구(IEA)는 나트륨 이온 배터리의 성장세가 강해지고 있다고 지적하는 한편, 이 기술에는 여전히 제조 및 성능 측면에서 과제가 남아 있다고 밝혔습니다. CATL은 2025년 4월 2세대 ‘Naxtra’ 배터리를 발표하며, 로트 간 품질이 더욱 안정적이고 방전 특성(rate characteristic)이 향상된 소재에 대한 기대감을 높이고 있습니다. 셀 제조업체들은 소재가 인증된 생산 라인에 도입되기 전에 하드 카본 공급업체들에게 더욱 엄격한 사양을 충족할 것을 점점 더 요구하고 있습니다. 주요 셀 제조업체의 승인은 공급업체가 이미 엄격한 조건 하에서 성능을 입증한 것이기 때문에 다른 구매자와의 조달 협상 기간을 단축할 수 있습니다. 나트륨 이온 배터리가 시범 프로젝트 단계에서 더 대규모의 자동차용 및 고정형 에너지 저장 시스템으로 도입되는 단계로 넘어감에 따라, 시장에서는 하드 카본 생산량의 대폭적인 증가가 필요할 것으로 보입니다.
저비용 고정형 에너지 저장 수요
고정형 에너지 저장 시스템은 리튬 관련 가격 및 공급 리스크를 배경으로 대안을 모색하는 구매자가 존재하기 때문에 나트륨 이온 배터리용 경질 탄소 시장 수요를 뒷받침하고 있습니다. 나트륨 이온 기술은 장기간 가동되는 자산을 필요로 하고, 중요 광물에 대한 의존도를 낮추고자 하는 저장 개발 사업자에게 공급망의 대안이 될 수 있습니다. Peak Energy는 2025년 7월 미국에서 그리드 규모의 나트륨 이온 배터리 저장 시스템을 납품하고, 전력 회사 및 독립 발전 사업자(IPP) 파트너와의 상업적 활동을 발표했습니다. 에너지 저장 프로젝트에서는 예상 출력을 조절하는 방식이나 가동 수명에 따라 서로 다른 수준의 음극 성능이 요구됩니다. 용량을 우선시하는 용도에는 에너지용 등급이 적합하며, 빈번한 충방전이 요구되는 용도에는 롱 사이클 등급이 적합합니다. 이러한 구분에 따라 하드 카본 조달 시 용도에 맞는 사양의 중요성이 점점 더 커지고 있습니다.
낮은 초기 쿨롱 효율과 프리소다화 요건
초기 쿨롱 효율은 나트륨 이온 배터리용 경질 탄소 시장에 있어 여전히 중요한 제약 요인으로 남아 있습니다. 초기 상용 하드 카본 소재의 경우 초기 쿨롱 효율이 17%로 낮았던 반면, 계면 개질법을 통해 실험실에서의 성능은 82%까지 향상되었습니다. 아릴나트륨을 이용한 프리소다화 관련 연구에서는 60초 이내에 초기 쿨롱 효율을 100% 가까이 높이는 방법이 보고되었으나, 산업 규모의 처리 능력에서 정확한 프리소다화를 유지하는 것은 여전히 어렵습니다. 화학 기상 증착, 프리소다화, 헤테로원소 도핑은 성능을 향상시킬 수 있지만, 공정 제어에 대한 요구 사항도 높아집니다. 이러한 공정은 제조 비용을 상승시켜 나트륨 이온 화학이 제공하는 가격적 우위를 일부 상실시킬 가능성이 있습니다. 비용 효율을 중시하는 용도의 경우 효율이 다소 낮아도 용인될 수 있지만, 요구 사항이 까다로운 에너지 저장 및 자동차 용도에서는 초기 사이클 성능이 뛰어난 프리미엄 등급이 요구됩니다.
부문 분석
바이오매스 유래 하드 카본은 2025년 나트륨 이온 배터리용 경질 탄소 시장 점유율의 40.56%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 34.27%를 나타낼 것으로 예측됩니다. 대나무, 코코넛 껍질, 벼 껍질, 농작물 잔여물은 지리적으로 분산된 전구체 옵션을 제공하며, 농업 잔여물이 이미 대규모로 회수되고 있는 지역에서 현지 조달을 지원할 수 있습니다. 이러한 원료는 수명 주기 전반에 걸친 탄소 배출량 감축을 목표로 하는 조달 프로그램과 부합하지만, 그 구성상 신중한 공정 관리가 필요합니다. 2026년 『Green Chemistry』 저널에 발표된 연구에 따르면, 탄화 및 흑연화 과정을 거쳐 제조된 셀룰로오스계 하드 카본은 320.38mAh/g의 가역 용량을 보였으며, 높은 전류 밀도 하에서 1,000회의 충방전 후에도 용량의 88.15%를 유지했습니다. 이러한 결과는 전구체의 처리와 가공을 적절히 제어하면 바이오매스 유래 소재라도 까다로운 성능 요건을 충족할 수 있음을 보여줍니다.
피치계 소재는 미세 구조의 일관성이 더 높은 반면, 수지계 공정에서는 높은 탄화 수율과 전극 코팅 자동화에 적합한 입자 형태를 얻을 수 있습니다. 중국의 생산 업체들은 당초 수입된 코코넛 껍질에 의존했으나, 열대 지역의 바이오매스만으로는 필요한 규모를 충족할 수 없기 때문에 현재는 국내 대체 원료를 검토하고 있습니다. 2025년 『Science China Chemistry』 저널에 실린 연구에 따르면, 최적화된 페놀 수지계 하드 카본은 초기 쿨롱 효율 92.2%, 가역 용량 324.4mAh/g를 달성했습니다. 석유 코크스, 바이오숯,혼합 전구체 복합재료는 여전히 소규모 제조 경로이지만, 산업적 공급이 더욱 확실해질 경우 추가적인 선택지가 될 것입니다. 나트륨 이온 배터리용 경질 탄소 시장은 공급 안정성, 품질, 탄소 특성이 제조 경로에 따라 다르기 때문에 단일 범용 전구체로 수렴하는 경향은 보이지 않습니다.
탄화 및 열분해 공정은 2025년 나트륨 이온 배터리용 경질 탄소 시장 점유율의 56.41%를 차지했습니다. 이러한 위상은 확립된 산업 인프라와 유기 전구체를 터보스트라틱 카본으로 변환하는 공정이 비교적 단순하기 때문입니다. 처리는 일반적으로 1,000°C에서 1,500°C 사이에서 이루어지며, 가열 속도, 유지 시간, 주변 환경에 따라 기공 구조와 층간 거리가 달라집니다. 이러한 매개변수는 나트륨의 저장 거동을 결정하는 한편, 활성화 처리를 통해 용량보다 방전 속도를 우선시하는 용도를 위해 표면 활성 부위가 추가로 생성됩니다. 이 공정은 광범위한 전구체 재료에 대응할 수 있기 때문에 생산에서 여전히 중심적인 역할을 하고 있습니다.
표면 개질 시장은 2031년까지 연평균 성장률(CAGR) 33.51%를 나타낼 것으로 예측되며, 나트륨 이온 배터리용 경질 탄소 시장에서 가장 빠르게 성장하는 공정 부문이 될 전망입니다. 코팅, 도핑, 프리소다화 처리를 통해 초기 쿨롱 효율 향상과 비가역적 용량 손실 감소를 도모합니다. 2025년 『RSC Advances』 저널의 연구에 따르면, 암모니아 개질 탄화법으로 제조된 질소 도핑 하드 카본은 초기 쿨롱 효율 81.81%, 제1 사이클 방전 용량 373.3mAh/g을 달성했습니다. 이 연구에서는 흡착, 삽입, 기공 충진에 의한 나트륨 저장에 대해 설명하고 있습니다. 셀 제조업체가 특정 성능 프로파일을 필요로 하는 경우, 개질 소재는 표준 탄화 등급보다 높은 가격에 판매될 가능성이 있습니다.
지역별 분석
아시아태평양은 2025년 나트륨 이온 배터리용 경질 탄소 시장의 47.34% 점유율을 차지했으며, 2031년까지 연평균 성장률(CAGR) 34.11%를 나타낼 것으로 예측됩니다. 중국에서는 배터리 제조, 탄화 능력, 전구체 처리, 셀 조립이 단일 공급망 내에 통합되어 있습니다. 이러한 구조 덕분에 물류 비용 절감, 공급업체와의 신속한 협력, 고정형 에너지 저장 및 비용 효율을 중시하는 전동 모빌리티 용도에서의 견고한 수요가 뒷받침되고 있습니다. 일본은 일관된 미세 구조 품질에 대한 기술력과 셀 제조업체와의 확고한 인증 관계를 강점으로 삼고 있습니다. 한국 또한 나트륨 이온 배터리 사업 기회에 대응하기 위해 소재 기반 구축을 추진하고 있습니다.
아시아태평양의 우위는 바이오매스, 석탄 유래 소재, 합성 수지를 원료로 활용할 수 있다는 점에 기반을 두고 있습니다. 이 지역의 나트륨 이온 배터리용 경질 탄소 시장은 확립된 배터리 인프라와 지역 공급망에 대한 정책 지원의 혜택을 받고 있습니다. 인도는 벼 껍질, 수확 후 남은 그루터기, 대나무 등의 농업 잔여물을 보유하고 있으며, 이는 전구체의 국내 수요를 충족시키는 데 일조할 수 있습니다. 에너지 비용이 음극의 경제성에 영향을 미치는 경우, 흑연에 비해 처리 온도가 낮다는 점은 중요한 이점이 됩니다. 원료 수집, 재료의 일관성, 인증 능력이 이 지역의 신규 공급업체가 얼마나 신속하게 규모를 확대할 수 있을지를 결정할 것으로 보입니다.
북미와 유럽은 현재 생산량은 적지만, 추적성이 확보되어 저탄소 하드 카본을 요구하는 고부가가치 시장으로 발전할 가능성이 있습니다. Peak Energy가 2025년에 미국에서 그리드 규모의 시스템을 납품한 것은 나트륨 이온 에너지 저장에 대한 상업적 관심을 보여줍니다. 유럽의 구매자들은 탄소 발자국 공개 요건에 직면해 있어, 전구체의 원산지 및 수명 주기에 관한 문서화된 데이터가 중요시됩니다. 남미, 중동 및 아프리카에서는 수요가 아직 초기 단계이지만, 농업 잔여물, 재생에너지 도입, 에너지 전환 프로그램이 향후 고정형 에너지 저장 용도를 뒷받침할 가능성이 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the sodium-ion battery-grade hard carbon market size was valued at USD 81.87 million in 2025 and is estimated to grow from USD 107.62 million in 2026 to reach USD 440.50 million by 2031, at a CAGR of 32.56% during the forecast period (2026-2031).
This report is Segmented by Feedstock (Biomass-Based and More), Process Type (Carbonization/Pyrolysis and More), Grade (Energy-Oriented Grade and More), Application (Energy Storage Systems and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Sodium-Ion Battery-Grade Hard Carbon Market Trends and Insights
Commercialization of Sodium-Ion Batteries
The commercialization of sodium-ion batteries is a direct driver of demand for the sodium-ion battery-grade hard carbon market. The International Energy Agency has identified growing momentum in sodium-ion batteries, while noting that the technology still faces manufacturing and performance challenges. CATL introduced its second-generation Naxtra battery in April 2025, raising expectations for materials with more consistent batch quality and improved rate capability. Cell producers increasingly require hard carbon suppliers to meet tighter specifications before material can enter qualified production lines. Approval by a large cell manufacturer can shorten procurement discussions with other buyers, as the supplier has already demonstrated performance under demanding conditions. As sodium-ion batteries move from pilot projects to larger vehicle and stationary storage deployments, the market will require a substantial increase in hard carbon output.
Demand for Lower-Cost Stationary Energy Storage
Stationary energy storage supports demand in the sodium-ion battery-grade hard carbon market, as buyers seek alternatives amid lithium-related price and supply risks. Sodium-ion technology can provide a supply chain option for storage developers that need long-duration assets and want to reduce reliance on critical minerals. Peak Energy delivered a grid-scale sodium-ion battery storage system in the United States in July 2025 and announced commercial activity with utility and independent power producer partners. Storage projects require different anode performance levels depending on expected dispatch patterns and operating life. Energy-oriented grades suit applications that prioritize capacity, while long-cycle grades suit frequent cycling requirements. This distinction is expanding the role of application-specific specifications within hard carbon procurement.
Low Initial Coulombic Efficiency and Pre-Sodiation Requirements
Initial Coulombic efficiency remains a material constraint for the sodium-ion battery-grade hard carbon market. Early commercial hard carbon materials showed initial Coulombic efficiency as low as 17%, while interface modification methods have raised performance to 82% in laboratory work. Research on aryl-sodium pre-sodiation has reported pathways toward near-100% initial Coulombic efficiency within 60 seconds, but maintaining accurate pre-sodiation at industrial throughput remains difficult. Chemical vapor deposition, pre-sodiation, and heteroatom doping can improve performance but increase process control requirements. These steps can raise manufacturing costs and reduce part of the price advantage available from sodium-ion chemistry. Cost-focused applications may accept lower efficiency, while demanding storage and vehicle applications require premium grades with stronger first-cycle performance.
Other drivers and restraints analyzed in the detailed report include:
- Growth of Cost-Sensitive Electric Mobility
- Abundant and Diversified Sodium-Ion Battery Supply Chains
- Feedstock Variability in Biomass-Derived Hard Carbon
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biomass-based hard carbon held 40.56% of the sodium-ion battery-grade hard carbon market share in 2025 and is forecast to grow at a 34.27% CAGR through 2031. Bamboo, coconut shells, rice husks, and crop residues offer geographically distributed precursor options and can support localized sourcing where agricultural residues are already collected at scale. These feedstocks align with procurement programs aimed at reducing life-cycle carbon emissions, although their composition requires careful process management. A 2026 Green Chemistry study reported that cellulose-based hard carbon produced via carbonization and graphitization exhibited a reversible capacity of 320.38 mAh/g and retained 88.15% of its capacity after 1,000 cycles at high current density. These results indicate that biomass-derived materials can meet demanding performance requirements when precursor treatment and processing are controlled.
Pitch-based materials offer tighter microstructural consistency, while resin-based routes can provide high carbonization yields and particle shapes suited to automated electrode coating. Chinese producers initially relied on imported coconut shells but have since considered domestic alternatives, as tropical biomass alone cannot meet the required scale. A 2025 Science China Chemistry study found that optimized phenolic resin hard carbon achieved 92.2% initial coulombic efficiency and a reversible capacity of 324.4 mAh/g. Petroleum coke, biochar, and mixed-precursor composites remain smaller routes but offer additional options where industrial supply is more reliable. The sodium-ion battery-grade hard carbon market is not moving toward a single universal precursor, as supply security, quality, and carbon characteristics vary by route.
Carbonization and pyrolysis accounted for 56.41% of the sodium-ion battery-grade hard carbon market share in 2025. This position reflects established industrial infrastructure and the relative simplicity of converting organic precursors into turbostratic carbon. Processing generally occurs between 1,000°C and 1,500°C, with heating rate, dwell time, and atmosphere influencing pore structure and interlayer spacing. These parameters govern sodium storage behavior, while activation creates additional surface sites for applications that prioritize discharge rate over capacity. The process remains central to production because it accommodates a broad range of precursor materials.
Surface modification is forecast to grow at a 33.51% CAGR through 2031, making it the fastest-growing process segment in the sodium-ion battery-grade hard carbon market. Coating, doping, and pre-sodiation-compatible processing address higher initial coulombic efficiency and lower irreversible capacity loss. A 2025 RSC Advances study reported that nitrogen-doped hard carbon produced via ammonia-modified carbonization achieved an initial coulombic efficiency of 81.81% and a first-cycle discharge capacity of 373.3 mAh/g. The study described sodium storage through adsorption, intercalation, and pore filling. Modified material can command premiums over standard carbonized grades when cell makers require specific performance profiles.
Complete Report Scope:
- By Feedstock
- Biomass-Based
- Pitch-Based
- Resin-Based
- Others
- By Process Type
- Carbonization/Pyrolysis
- Activation
- Surface Modification (Coating, Doping, Pre-sodiation Compatible Processing)
- Others
- By Grade
- Energy-Oriented Grade
- Power-Oriented Grade
- Long-Cycle Grade
- Others (Low-Temperature and Specialty Grades)
- By Application
- Energy Storage Systems
- Electric Vehicles (Including Two-/Three-Wheelers and Low-Speed EVs)
- Consumer and Industrial Batteries
- UPS and Telecom
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 47.34% of the sodium-ion battery-grade hard carbon market share in 2025 and is forecast to grow at a 34.11% CAGR through 2031. China integrates battery manufacturing, carbonization capacity, precursor processing, and cell assembly within a single supply chain. This structure supports lower logistics costs, faster supplier collaboration, and strong demand from stationary storage and cost-sensitive electric mobility applications. Japan contributes technical capability in consistent microstructural quality and established qualification relationships with cell manufacturers. South Korea is also developing its materials base to address sodium-ion battery opportunities.
Asia-Pacific's position is supported by its ability to utilize biomass, coal-derived materials, and synthetic resins as feedstocks. The sodium-ion battery-grade hard carbon market in the region benefits from established battery infrastructure and policy support for local supply chains. India holds agricultural residues, including rice husks, crop stubble, and bamboo, that could help meet domestic demand for precursors. Lower processing temperatures compared to graphite are relevant where energy costs affect anode economics. Feedstock collection, material consistency, and qualification capacity will determine how quickly new regional suppliers can scale.
North America and Europe currently represent lower output but may develop into higher-value markets for traceable and lower-carbon hard carbon. Peak Energy's 2025 delivery of grid-scale systems in the United States demonstrated commercial interest in sodium-ion storage. European buyers face carbon-footprint disclosure requirements that favor documented data on precursor origins and lifecycles. South America, the Middle-East, and Africa represent early-stage demand, though agricultural residues, renewable energy deployment, and energy-transition programs could support future stationary-storage applications.
- Aekyung Chemical Co., Ltd.
- BTR New Material Group Co., Ltd.
- Fujian Yuanli Active Carbon Co., Ltd.
- HiNa Battery Technology Co., Ltd
- Hunan Zhongke Shinzoom Technology Co., Ltd.
- JFE Chemical Corporation
- Jiangxi Zeto New Energy Technology Co., Ltd.
- KURARAY CO., LTD.
- KUREHA CORPORATION
- Ningbo Ronbay New Energy Technology Co., Ltd.
- Putailai New Materials Technology Co., Ltd.
- Shanghai PTL New Energy Technology Co.,Ltd.
- SHENGQUAN GROUP
- Shenzhen XFH Technology Co., Ltd.
- Sumitomo Bakelite Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Commercialization of Sodium-Ion Batteries
- 4.2.2 Demand for Lower-Cost Stationary Energy Storage
- 4.2.3 Abundant and Diversified Sodium-Ion Battery Supply Chains
- 4.2.4 Growth of Cost-Sensitive Electric Mobility
- 4.2.5 Carbon-Footprint Reduction in Anode Material Supply Chains
- 4.2.6 Qualification Advantage of Consistent Hard Carbon Batch Quality
- 4.3 Market Restraints
- 4.3.1 Low Initial Coulombic Efficiency and Pre-Sodiation Requirements
- 4.3.2 Feedstock Variability in Biomass-Derived Hard Carbon
- 4.3.3 Limited Commercial-Scale Qualification Capacity
- 4.3.4 Competition from Improving Lithium-Ion Anode Materials
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Feedstock
- 5.1.1 Biomass-Based
- 5.1.2 Pitch-Based
- 5.1.3 Resin-Based
- 5.1.4 Others
- 5.2 By Process Type
- 5.2.1 Carbonization/Pyrolysis
- 5.2.2 Activation
- 5.2.3 Surface Modification (Coating, Doping, Pre-sodiation Compatible Processing)
- 5.2.4 Others
- 5.3 By Grade
- 5.3.1 Energy-Oriented Grade
- 5.3.2 Power-Oriented Grade
- 5.3.3 Long-Cycle Grade
- 5.3.4 Others (Low-Temperature and Specialty Grades)
- 5.4 By Application
- 5.4.1 Energy Storage Systems
- 5.4.2 Electric Vehicles (Including Two-/Three-Wheelers and Low-Speed EVs)
- 5.4.3 Consumer and Industrial Batteries
- 5.4.4 UPS and Telecom
- 5.4.5 Others
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 NORDIC Countries
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Aekyung Chemical Co., Ltd.
- 6.4.2 BTR New Material Group Co., Ltd.
- 6.4.3 Fujian Yuanli Active Carbon Co., Ltd.
- 6.4.4 HiNa Battery Technology Co., Ltd
- 6.4.5 Hunan Zhongke Shinzoom Technology Co., Ltd.
- 6.4.6 JFE Chemical Corporation
- 6.4.7 Jiangxi Zeto New Energy Technology Co., Ltd.
- 6.4.8 KURARAY CO., LTD.
- 6.4.9 KUREHA CORPORATION
- 6.4.10 Ningbo Ronbay New Energy Technology Co., Ltd.
- 6.4.11 Putailai New Materials Technology Co., Ltd.
- 6.4.12 Shanghai PTL New Energy Technology Co.,Ltd.
- 6.4.13 SHENGQUAN GROUP
- 6.4.14 Shenzhen XFH Technology Co., Ltd.
- 6.4.15 Sumitomo Bakelite Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment