

|
시장보고서
상품코드
2119647
기업 성과 관리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Corporate Performance Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
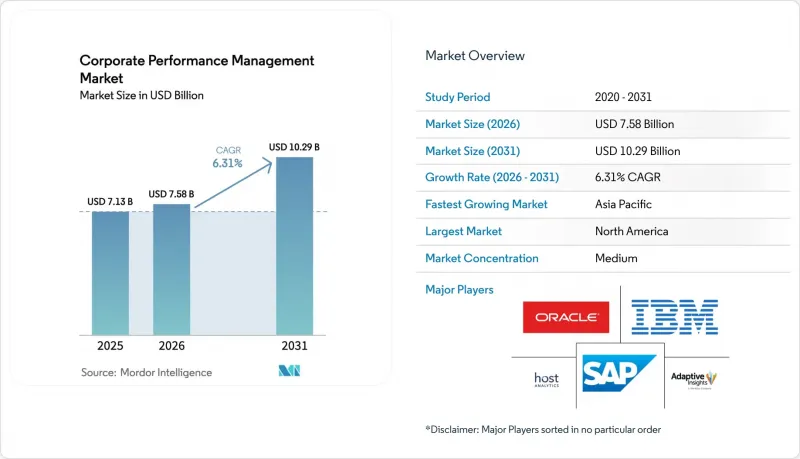
에 따르면 기업 성과 관리 시장 규모는 2025년 71억 3,000만 달러에서 2026년에는 75억 8,000만 달러로 확대되고, 2026년부터 2031년까지 CAGR 6.31%를 기록하며 2031년까지 102억 9,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 도입 형태(온프레미스, 클라우드 기반, 하이브리드), 조직 규모(중소기업, 대기업), 기능(재무, 인사, 공급망 등), 최종사용자 산업(BFSI, 소매·E-Commerce, 제조, 의료·생명과학, 에너지·공공사업 등), 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 기업 성과 관리(CPM) 시장의 동향 및 인사이트
클라우드 기반 CPM 플랫폼 도입 확대
클라우드로의 전환으로 인해 온프레미스 인프라가 불필요해지고, 재무 팀 간의 실시간 협업이 가능해짐에 따라 도입 비용 구조가 재편되고 있습니다. 2025년에는 신규 CPM 도입의 79%가 클라우드 네이티브가 될 것이며, 그 도입률은 북미가 가장 높고, 아시아태평양이 그 뒤를 잇는 반면, 유럽은 뒤처지고 있습니다. 현재 사용자의 68%가 셀프서비스형 계획을 활용하고 있어 IT에 대한 의존도가 낮아지고 의사결정 주기가 단축되고 있습니다. 각 벤더사는 ERP와 CPM 워크로드를 통합된 클라우드 상에 집약함으로써 지연 시간과 운영 비용을 모두 절감하며 그 가치를 입증하고 있습니다. 도입 격차가 확대되는 가운데, 데이터 주권 및 저지연 클라우드 영역을 전문으로 하는 공급업체들에게는 지리적으로 미개척 시장이 생겨나고 있습니다.
강화되는 규제 및 감사 요건
EU의 CSRD에서 SEC의 XBRL 태깅 강화에 이르기까지, 재무 및 비재무 정보의 공시 요건이 통합됨에 따라 자동화된 데이터 계보와 감사 가능한 보고서 작성이 요구되고 있습니다. 자산 운용사는 현재 지속가능성에 대한 주장을 뒷받침하는 동시에, 10-K 보고서를 상세한 원장 정보와 일치시켜야 합니다. 이중 중요성 평가 및 안전한 증거 저장소를 지원하는 통합형 CPM 제품군이 지지를 얻고 있는 한편, ISO 인증을 획득한 데이터센터는 필수 조건이 되었습니다. 대조 작업을 자동화할 수 없는 조직은 규정 준수 비용 증가 및 보고서 작성 주기 지연을 초래하여 플랫폼에 대한 수요를 더욱 높이고 있습니다.
높은 도입 및 통합 비용
복잡한 도입에는 소프트웨어, 통합 및 변경 관리에 대한 막대한 투자가 필요합니다. 여러 사업체를 대상으로 하는 프로젝트는 대개 12주에서 2년까지 진행되며, 부서 간 협업 팀이 수백 시간을 소요합니다. 150개 이상의 레거시 ERP 시스템을 연동하면 범위와 예산은 더욱 커집니다. 클라우드 구독 모델은 자본 지출을 부분적으로 상쇄하지만, 완전한 ROI를 실현하기 위해서는 엄격한 범위 설정, 견고한 데이터 마이그레이션 및 지속적인 사용자 지원이 필수적입니다.
부문 분석
2025년 매출 중 클라우드 플랫폼이 68.05%를 차지하며, 기업 성과 관리(CPM) 시장에서 주요 제공 모델로서의 입지를 공고히 하고 있습니다. 이 부문은 2031년까지 연평균 성장률(CAGR) 8.07%를 기록할 것으로 예측됩니다. 규제가 엄격한 산업에서는 기밀성이 높은 워크로드를 온프레미스에서 유지하면서 협업을 위해 클라우드 분석을 활용하는 하이브리드 모델이 여전히 자리 잡고 있습니다. 클라우드 기반 기업 성과 관리 시장의 규모는 아시아태평양에서 가장 빠르게 확대되고 있으며, 이 지역의 도입률은 유럽보다 25퍼센트 포인트 이상 높습니다. 지속적인 업데이트, 내장형 AI, 총 소유 비용(TCO) 절감이 전환을 촉진하는 한편, 데이터 주권 관련 기능은 유럽의 우려를 완화하고 있습니다. 각 공급업체는 위험 회피 성향의 고객을 확보하기 위해 다운타임 제로 릴리스와 싱글 테넌트 보안을 강조하고 있습니다. 온프레미스 배포는 여전히 에어갭 환경을 지원하지만, 예산 축소와 업그레이드 주기 장기화에 직면해 있습니다. 현재 경쟁사와의 차별화는 클라우드 서비스 수준, 확장성, 통합된 AI 파이프라인에 중점을 두고 있으며, 이에 따라 레거시 벤더들은 SaaS 로드맵을 가속화하고 있습니다.
유럽에서는 데이터 현지화 관련 지침과 보수적인 IT 거버넌스로 인해 클라우드 도입 속도가 둔화되고 있어, 리프트 앤 시프트(Lift-and-Shift) 전략이나 소버린 클라우드 제공업체와의 제휴에 여지가 남아 있습니다. 대조적으로, 북미 및 아시아태평양의 기업들은 통합, 예산 편성, 시나리오 계획 등의 워크로드를 통합된 클라우드 스택으로 신속하게 이전하고 있으며, 일관된 거버넌스와 신속한 혁신을 실현하고 있습니다. 이러한 지역 간 차이는 시장에 진출한 기업들의 제품 현지화, 가격 책정 및 파트너 지원 전략을 형성하고 있습니다.
대기업은 주로 다중 통화 기준의 연결 재무제표 및 엄격한 규정 준수 요건으로 인해 2025년 매출의 62.98%를 차지했습니다. 그러나 연평균 성장률(CAGR) 7.74%로 가장 빠르게 성장하고 있는 중소기업(SME)이 기업 성과 관리(CPM) 시장의 추가 성장을 주도하고 있습니다. 클라우드의 높은 비용 효율성, 구독형 가격 책정 및 기성 템플릿을 통해 진입 장벽이 낮아져 중소기업이 공식 보고 요건 및 대출 요건을 충족하는 데 도움이 되고 있습니다. 아시아태평양의 중소기업 및 초소기업(MSME)을 위한 디지털화 프로그램과 자본 시장 상장 절차의 간소화 또한 수요를 더욱 촉진하고 있습니다.
중소기업은 신속한 도입, Office 기반 인터페이스, IT 관련 간접비 최소화를 우선시하고 있으며, 확장성이나 거버넌스를 중시하는 대기업과는 대조적입니다. 벤더들은 계층화된 에디션, 도입 지원, 제품 내 튜토리얼 등을 통해 이에 대응하며, 가치 실현까지의 기간을 몇 주로 단축하고 있습니다. 한편, 상위 계층에서는 대기업들이 포인트 솔루션 대신 통합 플랫폼을 요구하며, 데이터의 일관성과 감사 대응 능력을 높이고 있습니다. 이러한 양극화로 인해 로드맵에도 차이가 나타나고 있습니다. 중소기업용으로는 직관적인 사용자 경험(UX)과 AI 기반 설정 지원이 제공되는 반면, 대기업용으로는 오픈 API, 샌드박스 환경, 세밀한 보안 대책이 제공되고 있습니다.
지역별 분석
2025년에는 북미가 38.10%의 점유율로 1위를 차지했습니다. 이는 성숙한 엔터프라이즈 소프트웨어 생태계, 풍부한 도입 인력, 그리고 재무 및 업무 분야에서의 AI 조기 도입에 힘입은 결과입니다. 기업들은 통합된 AI 시나리오와 규정 준수 자동화를 우선시하고 있으며, 이로 인해 벤더들의 지역 데이터센터 투자와 파트너 인증이 강화되고 있습니다. 유럽은 이에 이어, 신뢰할 수 있는 플랫폼 내에서 비재무 및 재무 정보의 통일된 공개를 요구하는 다층적인 ESG 규제가 성장의 견인차 역할을 하고 있습니다. 데이터 개인정보 보호 의무 및 주권에 대한 우려가 클라우드 전환을 지연시키고 있지만, 지역 내 호스팅 및 강력한 암호화를 제공하는 공급업체에게는 유리하게 작용하고 있습니다.
아시아태평양은 정부가 지원하는 중소기업(MSME)의 디지털화 보조금, 핀테크의 확대, 그리고 자본 시장 개혁에 힘입어 연평균 성장률(CAGR) 7.12%로 가장 빠르게 성장하고 있는 지역입니다. 아시아태평양의 중견 기업을 대상으로 한 기업 성과 관리(CPM) 시장 규모는 현지 시스템 통합업체들이 CPM을 ERP 도입과 함께 제공하게 됨에 따라 2030년까지 2배로 증가할 것으로 예측됩니다. 호주와 일본의 기업들은 ESG 보증을 중시하는 반면, 동남아시아 기업들은 환율 변동 속에서 현금 흐름 예측에 주력하고 있습니다. 남미에서는 상장 기업의 개혁과 해외 투자 유입으로 인해 최신 계획 도구에 대한 수요가 증가하며, 꾸준한 도입이 진행되고 있습니다. 중동 및 아프리카에서는 경제 다각화와 국가 비전 프로그램을 계기로 초기 도입이 진행되고 있으며, 대부분의 경우 예산 편성부터 시작하여 점차 분석 기능을 추가해 나가는 방식을 취하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the corporate performance management market size is expected to grow from USD 7.13 billion in 2025 to USD 7.58 billion in 2026 and is forecast to reach USD 10.29 billion by 2031 at 6.31% CAGR over 2026-2031.
This report is Segmented by Deployment Mode (On-Premises, Cloud-Based, and Hybrid), Organization Size (Small and Medium Enterprises, and Large Enterprises), Function (Finance, Human Resources, Supply Chain, and More), End-User Vertical (BFSI, Retail and E-Commerce, Manufacturing, Healthcare, Energy and Utilities, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Corporate Performance Management Market Trends and Insights
Rising adoption of cloud-based CPM platforms
Cloud migration reshapes deployment economics by eliminating on-premises infrastructure and enabling real-time collaboration across finance teams. In 2025, 79% of new CPM implementations are cloud-native, with adoption highest in North America, followed closely by Asia-Pacific, while Europe trails. Self-service planning now involves 68% of users, reducing IT dependence and compressing decision cycles. Vendors demonstrate value by consolidating ERP and CPM workloads on unified clouds, cutting both latency and operating costs. The widening adoption gap opens geographic whitespace for providers specializing in data-sovereignty and low-latency cloud zones.
Tightening regulatory and audit requirements
Converging financial and non-financial disclosure mandates, from EU CSRD to enhanced SEC XBRL tagging, require automated data lineage and auditable reporting. Asset managers must now substantiate sustainability claims and align 10-K filings with granular ledger detail. Integrated CPM suites that support double-materiality assessments and secure evidence repositories gain favor, while ISO-certified data centers become table stakes. Organizations unable to automate reconciliations incur higher compliance cost and slower report cycles, reinforcing platform demand.
High implementation and integration costs
Complex rollouts demand sizeable investments in software, integration, and change management. Multi-entity projects often span 12 weeks to 2 years, with cross-functional teams dedicating hundreds of hours. Connecting 150-plus legacy ERP systems magnifies scope and budget. Cloud subscription models partially offset capital outlay, yet full ROI depends on disciplined scope, robust data migration, and ongoing user enablement.
Other drivers and restraints analyzed in the detailed report include:
- AI/ML-driven predictive and prescriptive analytics
- Expansion of xPandA for cross-functional planning
- Data-security and privacy concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud platforms accounted for 68.05% of 2025 revenue, confirming their position as the primary delivery model for the Corporate Performance Management market. This segment is projected to post an 8.07% CAGR through 2031. Hybrid models persist in heavily regulated sectors that retain sensitive workloads on-premises yet tap cloud analytics for collaboration. The Corporate Performance Management market size attributed to cloud is widening fastest in Asia-Pacific, where adoption outpaces Europe by more than 25 percentage points. Continuous updates, embedded AI, and lower total cost propel conversions, while data-sovereignty features ease European concerns. Providers emphasize zero-downtime releases and single-tenant security to win risk-averse clients. On-premises deployments still serve air-gapped environments but face shrinking budgets and lengthier upgrade cycles. Competitive differentiation now pivots on cloud service level, scalability, and integrated AI pipelines, prompting legacy vendors to accelerate SaaS roadmaps.
In Europe, slower cloud uptake stems from data-localization directives and conservative IT governance, leaving room for lift-and-shift initiatives and vendor partnerships with sovereign-cloud providers. North American and Asia-Pacific enterprises, by contrast, expedite migration of consolidation, budgeting, and scenario planning workloads to unified cloud stacks, enabling cohesive governance and faster innovation. This regional divergence shapes product localization, pricing, and partner enablement strategies among market participants.
Large enterprises retained 62.98% of 2025 revenue, primarily due to multi-currency consolidation and stringent compliance needs. However, SMEs, the fastest-growing cohort at 7.74% CAGR, propel incremental gains in the Corporate Performance Management market. Cloud affordability, subscription pricing, and prebuilt templates decrease barriers, helping SMEs satisfy formal reporting and lending requirements. Asia-Pacific MSME digitalization programs and simplified capital-market listings further stimulate demand.
SMEs prioritize rapid deployment, Office-based interfaces, and minimal IT overhead, contrasting with enterprise preferences for extensibility and governance. Vendors respond with tiered editions, guided implementations, and in-product tutorials that compress time-to-value to weeks. At the upper end, conglomerates seek unified platforms to replace point solutions, enhancing data consistency and audit readiness. This bifurcation drives differentiated roadmaps: intuitive UX and AI-guided configuration for SMEs, versus open APIs, sandbox environments, and fine-grained security for large enterprises.
Complete Report Scope:
- By Deployment Mode
- On-Premises
- Cloud-Based
- Hybrid
- By Organization Size
- Small and Medium Enterprises (SMEs)
- Large Enterprises
- By Function
- Finance
- Human Resources
- Supply Chain
- Sales and Marketing
- By End-user Vertical
- Banking, Financial Services and Insurance (BFSI)
- Retail and E-commerce
- Manufacturing
- Healthcare and Life Sciences
- IT and Telecommunications
- Energy and Utilities
- Government and Public Sector
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
North America led with a 38.10% share in 2025, underpinned by mature enterprise-software ecosystems, deep implementation talent, and early AI adoption across finance and operations. Enterprises prioritize integrated AI scenarios and compliance automation, reinforcing vendor investment in regional data centers and partner certification. Europe follows, driven by multi-layered ESG mandates that demand unified non-financial and financial disclosures within trusted platforms. Data-privacy obligations and sovereignty concerns slow cloud conversion but favor providers offering in-region hosting and robust encryption.
Asia-Pacific is the fastest-growing geography at 7.12% CAGR, fueled by government-backed MSME digitization grants, fintech expansion, and capital-market reforms. The Corporate Performance Management market size across Asia-Pacific mid-market firms is projected to double by 2030 as local integrators bundle CPM with ERP rollouts. Australian and Japanese enterprises emphasize ESG assurance, while Southeast Asian companies focus on cash-flow forecasting amid currency volatility. South America exhibits a steady uptake as public company reforms and foreign investment inflows demand modern planning tools. In the Middle East and Africa, economic diversification and national vision programs trigger initial deployments, often starting with budgeting and gradually layering analytics.
- Oracle Corporation
- SAP SE
- IBM Corporation
- Microsoft Corporation
- Workday, Inc.
- Anaplan, Inc.
- Wolters Kluwer N.V. (CCH Tagetik)
- OneStream Software LLC
- Infor, Inc.
- Planful, Inc.
- Prophix Software Inc.
- insightsoftware, Inc.
- Jedox AG
- Board International S.A.
- Unit4 N.V.
- Epicor Software Corporation
- SAS Institute Inc.
- Adaptive Insights LLC (Workday Adaptive Planning)
- Host Analytics Inc.
- Longview Solutions Inc.
- Vena Solutions Inc.
- Solver USA, Inc.
- insightsoftware-CXO Software
- BlackLine, Inc.
- Deltek, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising adoption of cloud-based CPM platforms
- 4.2.2 Tightening regulatory and audit requirements
- 4.2.3 AI/ML-driven predictive and prescriptive analytics
- 4.2.4 Expansion of xPandA for cross-functional planning
- 4.2.5 Continuous scenario planning for supply-chain shocks
- 4.2.6 ESG data integration into CPM dashboards
- 4.3 Market Restraints
- 4.3.1 High implementation and integration costs
- 4.3.2 Data-security and privacy concerns
- 4.3.3 Shortage of CPM/FPandA analytics talent
- 4.3.4 Cultural resistance from non-finance functions
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Industry Stakeholder Analysis
- 4.9 Assessment of Macro-Economic Changes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Mode
- 5.1.1 On-Premises
- 5.1.2 Cloud-Based
- 5.1.3 Hybrid
- 5.2 By Organization Size
- 5.2.1 Small and Medium Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Function
- 5.3.1 Finance
- 5.3.2 Human Resources
- 5.3.3 Supply Chain
- 5.3.4 Sales and Marketing
- 5.4 By End-user Vertical
- 5.4.1 Banking, Financial Services and Insurance (BFSI)
- 5.4.2 Retail and E-commerce
- 5.4.3 Manufacturing
- 5.4.4 Healthcare and Life Sciences
- 5.4.5 IT and Telecommunications
- 5.4.6 Energy and Utilities
- 5.4.7 Government and Public Sector
- 5.4.8 Other End-user Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Vendor Positioning Analysis
- 6.5 Investment Analysis
- 6.6 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.6.1 Oracle Corporation
- 6.6.2 SAP SE
- 6.6.3 IBM Corporation
- 6.6.4 Microsoft Corporation
- 6.6.5 Workday, Inc.
- 6.6.6 Anaplan, Inc.
- 6.6.7 Wolters Kluwer N.V. (CCH Tagetik)
- 6.6.8 OneStream Software LLC
- 6.6.9 Infor, Inc.
- 6.6.10 Planful, Inc.
- 6.6.11 Prophix Software Inc.
- 6.6.12 insightsoftware, Inc.
- 6.6.13 Jedox AG
- 6.6.14 Board International S.A.
- 6.6.15 Unit4 N.V.
- 6.6.16 Epicor Software Corporation
- 6.6.17 SAS Institute Inc.
- 6.6.18 Adaptive Insights LLC (Workday Adaptive Planning)
- 6.6.19 Host Analytics Inc.
- 6.6.20 Longview Solutions Inc.
- 6.6.21 Vena Solutions Inc.
- 6.6.22 Solver USA, Inc.
- 6.6.23 insightsoftware-CXO Software
- 6.6.24 BlackLine, Inc.
- 6.6.25 Deltek, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


