

|
시장보고서
상품코드
2119774
인도의 과산화수소 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Hydrogen Peroxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
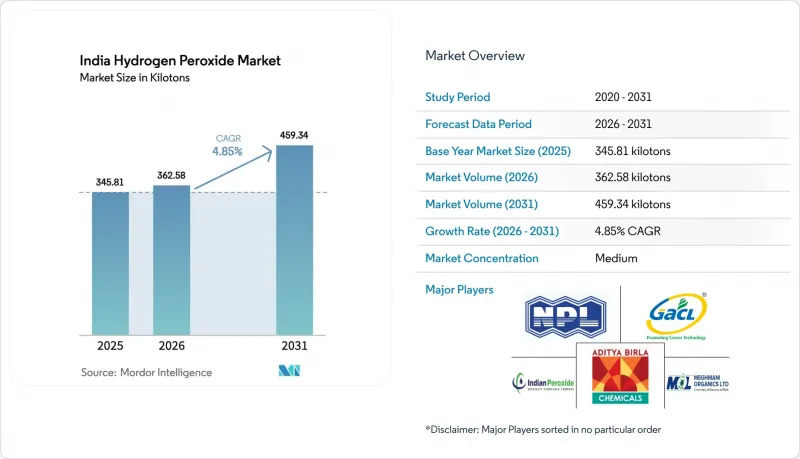
에 의하면, 2026년 인도의 과산화수소 시장 규모는 362.58 킬로톤에 달하고 2025년 345.81 킬로톤으로부터 확대해, 2031년에는 459.34 킬로톤에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 4.85%로 성장할 것으로 전망됩니다.
본 보고서는 제품 기능(소독제, 표백제, 산화제, 기타 기능) 및 최종 사용자 산업(펄프·제지, 화학 합성, 폐수 처리, 광업, 식품 및 음료, 화장품·헬스케어, 섬유, 기타 최종 사용자 산업(전자 및 포장))별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 제시되어 있습니다.
인도의 과산화수소 시장 동향 및 인사이트
국내 펄프·제지 업계의 표백 수요 증가
인도의 2,500만 톤 규모의 펄프 및 제지 부문은 52-75%의 재생 섬유에 의존하고 있으며, ISO 밝기 수준을 달성하기 위해서는 집중적인 과산화수소 표백이 필요합니다. 표백 공정은 이미 과산화수소 총량의 62.23%를 소비하고 있으며, 구자라트주, 타밀나두주, 안드라프라데시주, 오디샤주에 위치한 제지 공장의 입지와 연계되어 생산자에게 예측 가능한 베이스로드 수요를 창출하고 있습니다. 2014년 유엔 규정에 따라 농도 35%를 초과하는 용액의 장거리 운송이 제한되고 있으므로, 과산화수소 생산 설비를 제지 클러스터 근처에 설치함으로써 운송 비용을 절감할 수 있습니다. 종이 총생산량이 정체되어 있음에도 불구하고 재생 섬유의 생산 능력은 계속 증가하고 있어, 이로 인해 버진 펄프 수입량의 변동과 관계없이 표백 수요는 견조한 추세를 유지할 것으로 보장됩니다.
2·3급 도시에서의 폐수 AOP 설비 증가(AMRUT 2.0에 따라)
AMRUT 2.0에 따라 시설 개보수를 추진하는 지자체에서는 과산화수소에 자외선(UV)이나 오존을 병용하여 염료, 의약품, 미량 오염 물질을 분해하는 고도 산화 처리 시스템이 도입되고 있습니다. 틸푸르나 수라트 등 섬유 산업의 중심지는 ‘폐수 무방류’ 규제로 인해 염소를 포함한 배수가 처벌 대상이 되기 때문에 이 기술을 가장 먼저 도입하고 있습니다. 분산형 프로젝트 전개로 인해 수많은 중규모 수요 거점이 생겨나면서, 35% 농도의 제품을 안전하게 공급할 수 있는 지역 창고를 보유한 유통업체에 유리하게 작용하고 있습니다. AOP 플랜트에서 과산화수소 주입량 조정을 지원하는 서비스 지향적 공급업체는 고객의 신뢰를 얻어, 범용 표백제 가격을 상회하는 프리미엄 가격을 실현하고 있습니다.
화물 위험물 규제가 강화됨에 따라, 농도 35%를 초과하는 실린더 운송이 제한되고 있습니다.
2014년 유엔 규정에 따르면, 과산화수소는 부식성 부수적 위험을 수반하는 산화제로 분류되어 탱크로리 적재 농도는 35% 이상으로 제한되며, 항공기를 통한 40%를 초과하는 농도의 운송은 금지되어 있습니다. 생산자는 출하 전에 희석하여 유효 성분 1kg당 운송 비용을 증가시키거나, 지역 창고를 건설하여 운전 자금을 묶어두는 것 중 하나를 선택할 수밖에 없습니다. 현재 3급 섬유 산업 도시에 대한 물류 비용은 벌크 화학 물질에 비해 15-20% 더 높으며, 인증된 탱커 선단을 보유한 기존 기업이 유리한 입장에 있습니다.
부문별 분석
2025년에는 재생 섬유를 사용하는 제지 공장이 백도 목표를 달성하기 위해 고농도의 과산화수소를 첨가함에 따라, 표백 용도가 과산화수소 총량의 61.62%를 차지했습니다. 소독제 용도는 톤수 기준으로는 적지만, 병원이 기상 시스템을 도입하고 제약 공장이 저잔류형 소독제로 전환함에 따라 연평균 성장률(CAGR) 5.12%로 증가하고 있습니다. 산화제 등급은 광업 및 화학 합성에 이용되어 금과 구리의 회수율을 10-15% 향상시키고 있습니다. 틈새 시장인 가정용 제품, 채소 세척제, 식기세척기용 세제의 배합이 수요를 보완하고 있으나, 이러한 제품들은 식품화학코덱스(FCC) 준수가 필요하며 프리미엄 가격이 책정되어 있습니다.
인도의 과산화수소 시장에서 표백 용도 시장 규모는 재생지 생산 능력 확대에 발맞추어 꾸준히 성장할 것으로 예상되는 반면, 소독제 수요는 톤수 기준으로는 적지만 가치 점유율은 확대될 전망입니다. 산화제 용도는 금속 가격 변동에 연동되어 주기적인 움직임을 이어갈 것이며, 호황기에는 매력적인 이익률을 가져다줄 것입니다. 고순도 증기용 등급은 범용 표백 용도에서 전환을 모색하는 공급업체에게 발판이 될 것입니다. 대량 생산과 특수 정제를 결합하는 인도의 과산화수소 업계 참여 기업들은 고객사의 감사가 엄격해지는 가운데 EBITDA 마진 확대가 예상됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the India hydrogen peroxide market size in 2026 is estimated at 362.58 kilotons, growing from 2025 value of 345.81 kilotons with 2031 projections showing 459.34 kilotons, growing at 4.85% CAGR over 2026-2031.
This report is Segmented by Product Function (Disinfectant, Bleaching, Oxidant, and Other Functions) and End-User Industry (Pulp and Paper, Chemical Synthesis, Wastewater Treatment, Mining, Food and Beverage, Cosmetics and Healthcare, Textiles, Other End-User Industries (Electronics and Packaging)). Market Forecasts are Provided in Terms of Volume (tons).
India Hydrogen Peroxide Market Trends and Insights
Growing Domestic Pulp-and-Paper Bleaching Demand
India's 25 million-tonne pulp and paper sector relies on 52-75% recycled fiber, which requires intensive peroxide bleaching to achieve ISO brightness levels. Bleaching already absorbs 62.23% of the hydrogen-peroxide volume, providing producers with a predictable base-load offtake aligned with mill locations in Gujarat, Tamil Nadu, Andhra Pradesh, and Odisha. Freight savings accrue when peroxide units are located near paper clusters, as UN 2014 regulations limit long-haul movements of solutions with concentrations greater than 35%. Incremental recycled-fiber capacity continues to grow, even as total paper output plateaus, ensuring that bleaching demand remains resilient against fluctuations in virgin-pulp imports.
Rising Wastewater AOP Installations in Tier-2/3 Cities (Under AMRUT 2.0)
Municipalities upgrading under AMRUT 2.0 are adopting advanced-oxidation systems that dose hydrogen peroxide with UV or ozone to degrade dyes, pharmaceuticals, and micro-pollutants. Textile centers, such as Tiruppur and Surat, are early movers because zero-liquid-discharge mandates penalize chlorinated effluents. Decentralized project roll-outs create numerous mid-sized demand nodes, favoring distributors with regional depots that can supply 35% grades safely. Service-oriented suppliers that help calibrate peroxide feed rates in AOP plants are capturing loyalty and commanding a premium above commodity bleaching prices.
Freight-Hazard Regulations Tightening Cylinder Transport Above 35 % Strength
UN 2014 rules classify hydrogen peroxide as an oxidizer with a corrosive sub-risk, limiting tanker loads to above 35% and banning concentrations above 40% on aircraft. Producers must either dilute before shipment, which raises the freight cost per active kilogram, or build regional depots, locking up working capital. Logistics expenses to Tier-3 textile towns now run 15-20% above those for bulk chemicals, favoring incumbents that own certified tanker fleets.
Other drivers and restraints analyzed in the detailed report include:
- Capacity Expansion by New Entrants Using Green-Hydrogen Feedstock
- Textile Mills' Switch from Chlorine to Peroxide for Zero-Liquid-Discharge Compliance
- Volatility in Anthraquinone Import Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bleaching captured 61.62% of the hydrogen-peroxide volume in 2025 because recycled-fiber paper mills dose higher loadings to meet brightness targets. Disinfectant usage, although smaller in tonnage, is rising at a 5.12% CAGR as hospitals deploy vapor-phase systems and pharmaceutical plants convert to low-residue sanitizers. Oxidant grades serve mining and chemical syntheses, enhancing gold and copper recovery by 10-15 %. Niche household, vegetable-wash, and dishwasher formulations round out demand, but require Food Chemical Codex compliance and attract premium pricing.
The India hydrogen peroxide market size for bleaching is projected to rise steadily in lockstep with the addition of recycled-paper capacity, while disinfectant demand is set to carve out a larger value share, despite its lower tonnage base. Oxidant applications will stay cyclical, mirroring metal prices, yet deliver attractive margins in up-cycles. High-purity vapor grades provide a bridgehead for suppliers pivoting from commodity bleaching. The India hydrogen peroxide industry participants that combine bulk output with specialty purification stand to widen EBITDA spreads as customer audits tighten.
Complete Report Scope:
- By Product Function
- Disinfectant
- Bleaching
- Oxidant
- Other Functions (Antiseptic, Dishwasher, and Vegetable Wash)
- By End-user Industry
- Pulp and Paper
- Chemical Synthesis
- Wastewater Treatment
- Mining
- Food and Beverage
- Cosmetics and Healthcare
- Textiles
- Other End-User Industries (Electronics and Packaging)
List of Companies Covered in this Report:
- Aditya Birla Chemicals
- AkzoNobel N.V.
- Arkema
- Chemplast Sanmar Limited
- Evonik Industries AG
- Gujarat Alkalies and Chemicals Limited
- HANSOLCHEMICAL
- Hindustan Organic Chemicals Ltd.
- Indian Peroxide Limited
- Meghmani Finechem Limited
- National Peroxide Ltd.
- Nilkanth Organics
- OCI Ltd.
- Prakash Chemicals International Private Ltd.
- RXCHEMICALS
- Solvay
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing domestic pulp-and-paper bleaching demand
- 4.2.2 Rising wastewater AOP installations in Tier-2/3 cities (under AMRUT 2.0)
- 4.2.3 Capacity expansion by new entrants using green-hydrogen feedstock
- 4.2.4 Textile mills' switch from chlorine to peroxide for zero-liquid-discharge compliance
- 4.2.5 Semiconductor-grade peroxide demand from upcoming Indian fabs
- 4.3 Market Restraints
- 4.3.1 Freight-hazard regulations tightening cylinder transport above 35 % strength
- 4.3.2 Volatility in anthraquinone import prices
- 4.3.3 Persistent sub-scale plants (<20 ktpa) struggling with power tariffs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Product Function
- 5.1.1 Disinfectant
- 5.1.2 Bleaching
- 5.1.3 Oxidant
- 5.1.4 Other Functions (Antiseptic, Dishwasher, and Vegetable Wash)
- 5.2 By End-user Industry
- 5.2.1 Pulp and Paper
- 5.2.2 Chemical Synthesis
- 5.2.3 Wastewater Treatment
- 5.2.4 Mining
- 5.2.5 Food and Beverage
- 5.2.6 Cosmetics and Healthcare
- 5.2.7 Textiles
- 5.2.8 Other End-User Industries (Electronics and Packaging)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 Aditya Birla Chemicals
- 6.4.2 AkzoNobel N.V.
- 6.4.3 Arkema
- 6.4.4 Chemplast Sanmar Limited
- 6.4.5 Evonik Industries AG
- 6.4.6 Gujarat Alkalies and Chemicals Limited
- 6.4.7 HANSOLCHEMICAL
- 6.4.8 Hindustan Organic Chemicals Ltd.
- 6.4.9 Indian Peroxide Limited
- 6.4.10 Meghmani Finechem Limited
- 6.4.11 National Peroxide Ltd.
- 6.4.12 Nilkanth Organics
- 6.4.13 OCI Ltd.
- 6.4.14 Prakash Chemicals International Private Ltd.
- 6.4.15 RXCHEMICALS
- 6.4.16 Solvay
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


