

|
시장보고서
상품코드
2119820
인도의 파운드리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Foundry - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인도의 파운드리 시장 규모는 2025년에 262억 8,000만 달러로 평가되었습니다. 2026년에 287억 2,000만 달러에 달하고, 2031년까지 467억 2,000만 달러에 이를 것으로 예측되며, 2026-2031년에 걸쳐 CAGR 10.22%로 성장할 전망입니다.
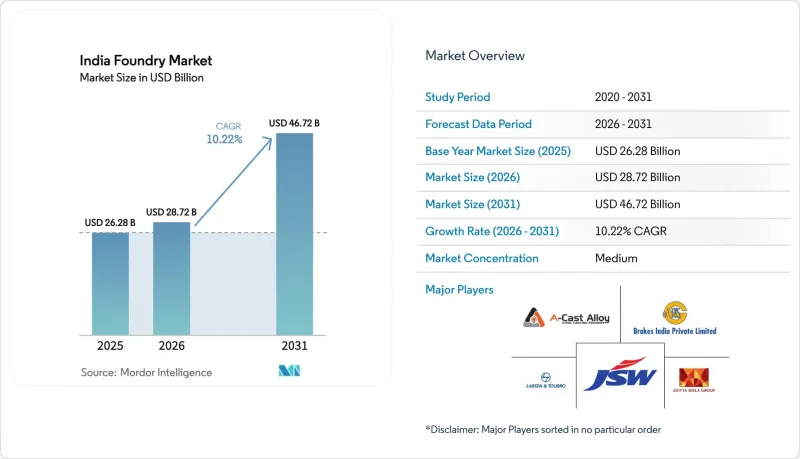
본 보고서는 주조 유형(모래 주조, 다이캐스팅, 기타), 재료(철, 비철), 최종 사용자(자동차, 항공우주, 건설, 기계, 기타), 지역(북인도, 서인도, 남인도, 동·북동인도, 중부 인도)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도의 파운드리 시장 동향 및 인사이트
2026 회계연도에 국내 전기차(EV) 생산 대수가 100만 대를 돌파하며 알루미늄 HPDC 수요를 끌어올릴 전망
EV 파워트레인의 현지화에 따라 HPDC 생산 라인은 엔진 부속 부품에서 더 엄격한 공차와 높은 열전도율이 요구되는 배터리 인클로저, 모터 하우징, 구조용 프레임으로 전환되고 있습니다. 힌달코(Hindalco)가 5,900만 달러를 투자한 차칸 공장은 2024년 12월까지 마힌드라 일렉트릭(Mahindra Electric)에 1만 개의 배터리 인클로저를 출하했으며, 2027 회계연도까지 연간 16만 개로 생산 규모를 확대할 예정입니다. 우노 민다(Uno Mind)사는 타타의 ‘넥슨 EV’와 마힌드라의 ‘XUV400’ 플랫폼용으로, 마하라슈트라 주에 연간 생산 능력 3,629톤 규모의 2,500만 달러 HPDC 시설을 가동하고 있습니다. 인도의 첨단 화학계 배터리 셀에 대한 생산 연계형 인센티브 제도에 따라 2027년까지 국내 부가가치율 60%가 의무화되어 있으며, 이로 인해 푸네, 차칸, 호수르의 각 클러스터에서 HPDC 수주가 더욱 공고해지고 있습니다. 난연 코팅은 가공 비용을 8-12% 증가시키지만, 이를 통해 Ola Electric 및 Ather Energy와의 고부가가치 계약이 가능해져, 차체 주조품의 평균 판매 가격이 상승하고 있습니다.
중국 주철 제품에 대한 40% 관세가 수입 대체를 가속화
2025년 1월부터 시행된 40%의 기본 관세로 인해 발주 주기가 90-120일에서 30-45일로 단축되었습니다. 마힌드라 앤 마힌드라와 타타 모터스는 1만 2,000톤 규모의 하우징 생산을 중국에서 킬로스카 페라스와 일렉트로스틸로 이전했습니다. 바랏 포지의 바라마티에 위치한 EV 부품 공장에서는 AI를 활용한 금형 충전 도구를 도입해 불량률을 1% 이하로 억제함으로써, 같은 주 내 납품을 실현하고 있습니다. 건설기계 OEM 각사는 향후 생산 인센티브에 힘입어 유압 실린더 배럴 및 붐 주조품의 현지 생산을 추진하고 있습니다. 2028년으로 예정된 관세 만료 시점까지 공장이 중국의 생산성 수준에 도달하지 못하면 수입 리스크가 다시 대두될 것, ‘SAMARTH Udyog Bharat 4.0’ 프로그램에 따른 디지털 트윈 도입으로 그 격차는 점차 좁혀지고 있습니다.
EU의 CBAM으로 인해 탄소 배출량이 높은 주조품의 수입 비용이 상승
CBAM에 따르면, 2026년 1월부터 1톤당 1.5톤 이상의 CO2를 배출하는 주조품에 대해 38.8%의 과징금이 부과됩니다. 톤당 1.8-2.2톤의 CO2를 배출하는 콜하푸르의 수출업체들은 즉시 이익률 압박에 직면하게 될 것입니다. 대기업은 규정 준수 비용을 흡수할 수 있지만, 공장의 70%는 자본력이 제한된 중소·영세 기업(MSME)입니다. 2025년 중반 이후 분기마다 최소 8-12개의 초소형 파운드리이 폐쇄되고 있으며, 구매자들이 CBAM 준수 공급업체로 전환함에 따라 산업 재편이 가속화되고 있습니다.
부문 분석
2025년에는 인베스트먼트 주조가 항공우주 등급 생산 능력 600톤을 확보하여 연평균 성장률(CAGR) 12.05%를 나타낼 것으로 예측되며, 인도의 파운드리 시장에서 다른 모든 주조 공법을 능가하는 성장을 이루고 있습니다. 한편, 모래 주조는 2025년 생산량의 58.82%를 차지하며 가장 큰 점유율을 유지했습니다. HAL이 수주한 201대의 테자스 Mk 2 제트기(총 수주액 214억 달러)가 PTC 인더스트리즈, 다이나매틱 테크놀로지스, 에이큐스에 대한 터빈 블레이드 수주를 견인하고 있습니다. 인코넬 718 등의 인베스트먼트 주조용 초합금은 950-1,200MPa의 인장 강도를 발휘하며, 1,050℃의 가스 유로 온도를 견딜 수 있습니다. 이는 모래 주조로는 실현할 수 없는 특성입니다. 금형 제작 및 왁스 모델 성형 공정을 거치면 부품 비용은 1kg당 10달러로 치솟지만, OEM 각사는 엄격한 공차와 피로 수명을 확보할 수 있다는 점을 이유로 이 높은 가격을 수용하고 있습니다.
자동차용 실린더 블록, 철도용 연결기, 펌프 하우징 부문에서는 여전히 모래 주조가 인도의 파운드리 시장 규모의 기반을 이루고 있습니다. 콜하푸르와 푸네에서만 연간 약 60만 톤의 모래 주철 부품이 출하되고 있습니다. 다이캐스팅은 우노 민다(Uno Minda)사가 마하라슈트라 주에 신설 예정인 공장을 필두로, 사이클 타임 45초로 전기차용 모터 하우징 및 배터리 프레임 생산으로 무게중심을 옮겨가고 있습니다. 영구 주형, 증발 주형, 원심 주조는 피스톤, 크랭크샤프트, 연성 주철 파이프용으로 공급되고 있으며, 시장 점유율은 적습니다. 인베스트먼트 주조가 급속히 성장하고 있음에도 불구하고, 대형 디젤 엔진이나 철도 대차에는 여전히 주철이 많이 사용되기 때문에 2031년까지 인도의 파운드리 시장 점유율의 절반 이상을 모래주조가 계속 차지할 것으로 전망됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the India foundry market size is projected to be USD 26.28 billion in 2025, USD 28.72 billion in 2026, and reach USD 46.72 billion by 2031, growing at a CAGR of 10.22% from 2026 to 2031.

This report is Segmented by Casting Type (Sand Casting, Die Casting, and More), by Material (Ferrous, Non-Ferrous), by End-User (Automotive, Aerospace, Construction, Machinery, and More), and by Geography (North India, West India, South India, East & North-East India, Central India). Market Forecasts are Provided in Terms of Value (USD).
India Foundry Market Trends and Insights
Domestic EV Output Passing 1 Million Units in FY-26 Boosts Aluminum HPDC Demand
EV power-train localization is diverting HPDC lines from engine ancillaries to battery enclosures, motor housings, and structural frames that demand tighter tolerances and higher thermal conductivity. Hindalco's USD 59 million Chakan plant shipped 10,000 battery enclosures to Mahindra Electric by December 2024 and is scaling to 160,000 units a year by FY-2027. Uno Minda is commissioning a USD 25 million HPDC facility in Maharashtra with 3,629 t annual capacity aimed at Tata's Nexon EV and Mahindra's XUV400 platforms. India's production-linked incentive for advanced-chemistry cells compels 60% domestic value-addition by 2027, further anchoring HPDC orders in Pune, Chakan, and Hosur clusters. Although flame-retardant coatings add 8-12% processing cost, they unlock premium contracts with Ola Electric and Ather Energy, lifting average selling prices on enclosure castings.
40% Duty on Chinese Iron Castings Accelerates Import Substitution
A 40% basic customs duty, effective January 2025, has slashed ordering cycles from 90-120 days to 30-45 days. Mahindra & Mahindra and Tata Motors have shifted 12,000 t of housing from China to Kirloskar Ferrous and Electrosteel. Bharat Forge's Baramati EV-component plant uses AI mold-fill tools to keep rejections below 1%, enabling same-week deliveries. Construction-equipment OEMs, buoyed by a future production incentive, are localizing hydraulic-cylinder barrels and boom castings. Unless plants reach Chinese productivity by the duty's scheduled 2028 expiry, import risk will resurface, but digital-twin roll-outs under the SAMARTH Udyog Bharat 4.0 program are closing the gap.
EU CBAM Raises Landed Cost of High-Carbon Castings
The CBAM applies a 38.8% levy on castings above 1.5 t CO2 per t from January 2026. Kolhapur's exporters, emitting 1.8-2.2 t CO2 per t, face immediate margin compression. Larger players absorb compliance costs, yet 70% of shops are MSMEs with limited capital. At least 8-12 micro-foundries have shut each quarter since mid-2025, accelerating consolidation as buyers shift to CBAM-compliant suppliers.
Other drivers and restraints analyzed in the detailed report include:
- Vehicle Scrappage Policy Delivers Cheaper Ferrous and Non-Ferrous Scrap
- Green-Hydrogen Subsidies Support Furnace Conversion in Select Clusters
- Import Curbs on Petcoke and High-Sulfur Coal Inflate Melt-Fuel Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Investment casting captured 600 t of aerospace-grade capacity in 2025 and is set for a 12.05% CAGR, outperforming every other route in the India foundry market. Sand casting, however, remained the largest at 58.82% of 2025 volume. HAL's USD 21.4 billion order book for 201 Tejas Mk 2 jets is driving turbine-blade contracts for PTC Industries, Dynamatic Technologies, and Aequs. Investment-cast superalloys such as Inconel 718 deliver 950-1,200 MPa tensile strength and can tolerate 1,050 °C gas-path temperatures, attributes that are impossible via sand molds. Although tools and waxing stages inflate part costs to USD 10 per kg, OEMs accept premiums for tight tolerance and fatigue life.
Sand casting still underpins the India foundry market size for automotive cylinder blocks, railway couplers, and pump housings. Kolhapur and Pune alone ship about 600,000 t of sand-cast iron parts annually. Die casting, led by Uno Minda's upcoming Maharashtra unit, is pivoting to EV motor housings and battery frames at cycle times of 45 seconds. Permanent-mold, evaporative-pattern, and centrifugal casting form a small share, serving pistons, crankshafts, and ductile-iron pipes. Even with investment casting's fast growth, sand casting will likely keep more than half of India's foundry market share through 2031 because large diesel engines and rail bogies will stay iron-intensive.
Complete Report Scope:
- By Casting Type
- Sand Casting
- Die Casting
- Investment Casting
- Other Types - Permanent-Mold Casting, Evaporative casting, High-Pressure Die Casting, and Centrifugal
- By Material
- Ferrous
- Non-Ferrous
- By End-User
- Automotive
- Aerospace
- Construction
- Machinery
- Railways
- Power Generation
- Pumps & Valves
- Electrical Components
- Others - General Engineering, etc.
- By Geography
- North India
- West India
- South India
- East & North-East India
- Central India
List of Companies Covered in this Report:
- A-Cast Foundry
- Aditya Birla Management Corp.
- Brakes India
- Larsen & Toubro
- JSW Steel
- CALMET
- Ashok Iron Works
- Gujarat Metal Cast Industries
- Electrosteel Castings
- Menon & Menon
- Kirloskar Ferrous Industries
- Tata Steel (Foundry Division)
- Mahindra CIE Automotive
- Sundaram Clayton
- Endurance Technologies
- Nelcast
- DCM Engineering
- Bharat Forge (Casting Ops)
- Hinduja Foundries
- Tata AutoComp Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Domestic EV four-wheeler output crossing 1 million units in FY-26, triggering a surge in aluminium HPDC demand
- 4.2.2 Mandatory Vehicle Scrappage Policy (April 2025) unlocking low-cost ferrous & non-ferrous scrap supply
- 4.2.3 40% basic customs duty on Chinese iron castings (2025 safeguard) boosting import substitution orders
- 4.2.4 National Green-Hydrogen Mission subsidies enabling cupola-to-hydrogen furnace conversions in select clusters
- 4.2.5 ONDC B2B metals marketplace lowering raw-material procurement costs for SME foundries
- 4.2.6 Global OEM Scope-3 mandates for "low-carbon castings" pushing investments in EAF/induction routes
- 4.3 Market Restraints
- 4.3.1 EU Carbon Border Adjustment Mechanism (phase-in from Oct 2025) raising effective landed cost of Indian castings
- 4.3.2 Import curbs on petcoke & high-sulphur coal inflating melting-fuel costs for coke-fired cupolas
- 4.3.3 Semiconductor-fab talent pull creating acute metallurgical-engineer shortages in foundry hubs
- 4.3.4 Rapid switch to glass-reinforced plastics in micro-mobility drivetrains eroding small-cast-part volumes
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Insights into Indian Manufacturing Market
- 4.9 Impact of Geopolitical Events on Supply Chains
5 Market Size & Growth Forecasts(Value, In USD Billion)
- 5.1 By Casting Type
- 5.1.1 Sand Casting
- 5.1.2 Die Casting
- 5.1.3 Investment Casting
- 5.1.4 Other Types - Permanent-Mold Casting, Evaporative casting, High-Pressure Die Casting, and Centrifugal
- 5.2 By Material
- 5.2.1 Ferrous
- 5.2.2 Non-Ferrous
- 5.3 By End-User
- 5.3.1 Automotive
- 5.3.2 Aerospace
- 5.3.3 Construction
- 5.3.4 Machinery
- 5.3.5 Railways
- 5.3.6 Power Generation
- 5.3.7 Pumps & Valves
- 5.3.8 Electrical Components
- 5.3.9 Others - General Engineering, etc.
- 5.4 By Geography
- 5.4.1 North India
- 5.4.2 West India
- 5.4.3 South India
- 5.4.4 East & North-East India
- 5.4.5 Central India
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Initiatives
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 A-Cast Foundry
- 6.4.2 Aditya Birla Management Corp.
- 6.4.3 Brakes India
- 6.4.4 Larsen & Toubro
- 6.4.5 JSW Steel
- 6.4.6 CALMET
- 6.4.7 Ashok Iron Works
- 6.4.8 Gujarat Metal Cast Industries
- 6.4.9 Electrosteel Castings
- 6.4.10 Menon & Menon
- 6.4.11 Kirloskar Ferrous Industries
- 6.4.12 Tata Steel (Foundry Division)
- 6.4.13 Mahindra CIE Automotive
- 6.4.14 Sundaram Clayton
- 6.4.15 Endurance Technologies
- 6.4.16 Nelcast
- 6.4.17 DCM Engineering
- 6.4.18 Bharat Forge (Casting Ops)
- 6.4.19 Hinduja Foundries
- 6.4.20 Tata AutoComp Systems
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


