|
시장보고서
상품코드
2119855
유럽의 분체 도료 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Powder Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
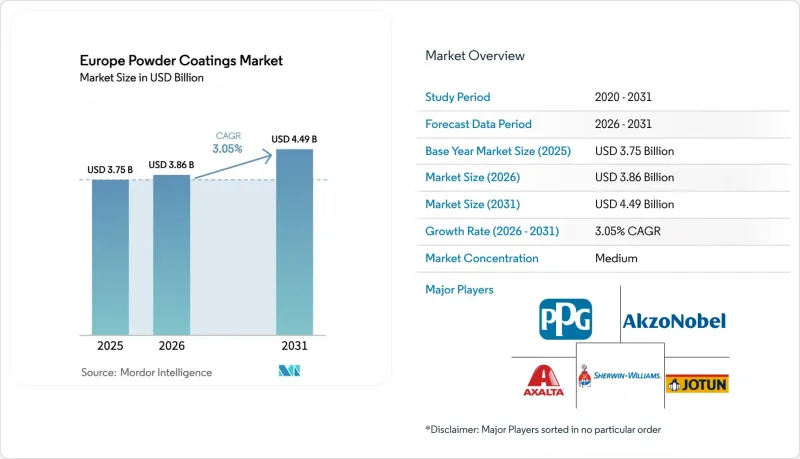
에 의하면, 유럽의 분체 도료 시장 규모는 2025년에 37억 5,000만 달러로 평가되었습니다. 2026년 38억 6,000만 달러에서 2031년까지 44억 9,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 3.05%를 나타낼 전망입니다.
본 보고서는 수지 유형(에폭시, 폴리에스테르, 에폭시·폴리에스테르(하이브리드), 폴리우레탄,아크릴, 기타), 최종 사용자 산업(건축·장식, 자동차, 산업, 기타 최종 사용자 산업), 지역(독일, 영국, 프랑스, 이탈리아, 스페인, 베네룩스, 북유럽 국가, 기타 유럽)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 분체 도료 시장 동향 및 인사이트
EU의 엄격한 VOC 규제 및 탄소 중립 규제
‘산업 배출 지침’과 ‘EU 그린 딜’이 결합되어 일부 표면 처리 부문에서 VOC 배기 가스 배출량을 20mg/m³로 제한하고 있으며, 사실상 무용제 분체 도장 공정이 우선시되고 있습니다. 연간 200톤 이상의 용제를 배출하는 시설은 4년 이내에 규정을 준수해야 하며, 이에 따라 밀폐형 분체 도장 부스 및 에너지 효율이 높은 경화로에 대한 설비 투자가 가속화되고 있습니다. 식품 접촉용 코팅에 대한 새로운 PFAS 기준치와 REACH 부속서 XVII의 규제 개정에 따라, 많은 액체 시스템에서 일반적으로 사용되는 불소계 화학 물질에 벌칙이 부과됨에 따라 이러한 전환이 더욱 가속화되고 있습니다. 자동차 재도장 시장에서는 현재 VOC 표시가 의무화되어 있으며, 덴마크에서는 세정제의 VOC 함량을 200g/L, 특수 도장재의 VOC 함량을 840g/L로 제한하는 방침을 채택하고 있어, 이러한 정책 방향은 다른 북유럽 국가들에서도 빠르게 따르고 있습니다. ISO 14001 감사에서는 분체 도장을 ‘이용 가능한 최선의 기술’로 채택하는 것이 점점 더 의무화되고 있으며, 이에 따라 전환 목표가 기업의 환경 로드맵에 반영되고 있습니다.
자동차 OEM 및 애프터마켓에서의 분체 도료 사용 증가
전동화에 따라 도장 요건이 변화하고 있습니다. 배터리 인클로저, 냉각판, 고전압 케이스에는 전기 절연성을 가지면서도 열전도성이 있는 코팅이 요구됩니다. 이에 따라 자동차 제조업체들은 기존의 140°C 사이클에서 80°C로 경화 온도를 낮춘 저온 경화 분체 도료를 채택하고 있으며, 이를 통해 도장 공장의 에너지 소비량을 11-13% 절감하고, 서로 다른 기판을 혼합 처리하는 데 있어 유연성을 높이고 있습니다. 공급업체의 인증은 내후성에 관한 AAMA 규격과 OEM의 클래스 A 마감 기준을 충족하는지에 달려 있으며, 이로 인해 기존 액상 도료 공급업체의 경쟁력이 약화되고 있습니다. 휠 재생 업체, 상용차 개조 업체, 농기계 재제조 업체 역시 내마모성과 긴 수명을 이유로 분체 도료로의 전환을 추진하고 있습니다.
30 마이크로미터 미만의 매끄러운 도막 형성의 어려움
고급 자동차 내장재나 가전제품의 외장에는 30 마이크로미터 미만의 도막 두께에서 거의 완벽한 표면 형태가 요구됩니다. 현재 분체 도료의 배합은 좁은 입자 크기 분포와 특수한 유동성 조절제에 의존하고 있지만, 복잡한 형태에서 균일성을 유지하는 것은 여전히 과제입니다. Allnex의 초저온 하이브리드 제품은 125°C에서 경화되어 레벨링성을 향상시키지만, 보다 엄격한 습도 관리와 첨단 도포 장비가 필요합니다. Evonik의 구형 안료 ‘SPHERILEX AC 45’는 분산성을 높여주지만, 밸류체인 전반에 걸친 배합 재검토가 필요합니다. 턴키 솔루션이 시장에서 성숙기에 도달할 때까지는 특정 고광택 부문에서 액상 시스템이 기술적 우위를 유지하게 될 것입니다.
부문 분석
2025년, 폴리에스테르는 유럽의 분체 도료 시장에서 42.01%의 점유율을 유지하며 유럽의 분체 도료 시장 규모에서 가장 큰 비중을 차지했습니다. 이러한 인기는 경제성, 폭넓은 색상 범위, 파사드 패널과 일반 산업기계 모두에 서비스를 제공하는 확립된 공급망에 기인합니다. 배합 제조업체들은 AAMA 2604 및 Qualicoat Class 2 사양을 충족하는 초내구성 등급을 도입함으로써 성능의 한계를 넓혀 왔습니다. 한편, 자동차 제조업체들이 경량 구조와 부식 보증 기간 연장을 추구하고 있는 만큼, 폴리우레탄 등급은 연평균 성장률(CAGR) 3.62%를 나타낼 것으로 예측됩니다. 또한, 저온 우레탄 화학 기술 덕분에 중밀도 섬유판(MDF) 가구에도 도장이 가능해지면서, 유럽의 가구 산업 거점에서 새로운 비즈니스 기회가 창출되고 있습니다.
기술 혁신의 초점은 현재 경화 효율에 맞추어져 있습니다. 악소노벨(AkzoNobel)사의 ‘Interpon D2525 Low-E’ 폴리에스터는 불과 150°C에서 경화가 가능하여 도장 부스 내 체류 시간을 20% 단축하는 동시에, 열에 민감한 합금에 대한 적용 범위를 확대되고 있습니다. 올넥스(Allnex)사의 ‘CRYLCOAT 4488-0’은 플로리다주에서 10년에 걸친 내후성을 갖추고 있으며, 한편 독성학적 재분류가 임박함에 따라 TGIC를 포함하지 않는 시스템이 신규 생산 능력의 주류를 차지하고 있습니다. 에폭시 수지는 계속해서 파이프라인용 밸브와 화학 반응기의 기반이 되고 있습니다. 하이브리드 수지는 장식성과 기능성 모두의 요구를 충족시키며, 아크릴 수지는 내후성이 매우 뛰어난 간판을 대상으로 합니다. 또한, 틈새 시장용 열가소성 수지는 가전제품 및 낙서 방지 부문에서 활용되고 있습니다. 이러한 화학 소재 전반에 걸쳐 분체 도료 공급업체들은 환경 제품 선언(EPD)을 점점 더 적극적으로 발표하며, 배합을 고객의 탄소 감사에 부합하도록 조정하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the Europe powder coatings market size was valued at USD 3.75 billion in 2025 and estimated to grow from USD 3.86 billion in 2026 to reach USD 4.49 billion by 2031, at a CAGR of 3.05% during the forecast period (2026-2031).

This report is Segmented by Resin Type (Epoxy, Polyester, Epoxy-Polyester Hybrid, Polyurethane, Acrylic, and More), End-User Industry (Architecture and Decorative, Automotive, Industrial, and Other End-User Industries), and Geography (Germany, United Kingdom, France, Italy, Spain, Benelux, NORDIC Countries, and Rest of Europe). The Market Forecasts are Provided in Terms of Value (USD).
Europe Powder Coatings Market Trends and Insights
Stringent EU VOC and carbon-neutrality regulations
The Industrial Emissions Directive and the EU Green Deal combine to cap VOC stack emissions at 20 mg/m3 for several surface-treatment categories, effectively prioritizing solvent-free powder processes. Facilities emitting more than 200 tonnes of solvent annually must achieve compliance within four years, accelerating capital deployment toward closed-loop powder booths and energy-efficient curing ovens. New PFAS thresholds for food-contact coatings and revised REACH Annex XVII restrictions reinforce the transition by penalizing fluorinated chemistries typical in many liquid systems. Automotive refinish markets now require VOC labeling, with Denmark limiting cleaners to 200 g/L and specialty finishes to 840 g/L, a policy stance that has been quickly mirrored in other Nordic states. ISO 14001 audits are increasingly mandating the use of powder as the "best available technique," thereby embedding conversion objectives into corporate environmental roadmaps.
Rising automotive OEM and aftermarket powder usage
Electrification reshapes finishing requirements: battery enclosures, cooling plates, and high-voltage casings demand electrically insulative yet thermally conductive coatings. Automakers are therefore adopting low-bake powders that cure at 80 °C-down from legacy 140 °C cycles-cutting paint-shop energy consumption by 11-13% and improving mixed-substrate processing flexibility. Supplier qualification hinges on meeting AAMA standards for weatherability and OEM Class A finish criteria, eroding the competitive position of incumbent liquid suppliers. Wheel refurbishers, commercial-vehicle upfitters, and agricultural equipment remanufacturers likewise migrate toward powders for their abrasion resistance and long service life.
Difficulty in achieving less than 30 µm smooth films
Premium automotive interiors and consumer electronics housings require near-perfect surface topography at film builds of less than 30 µm. Current powder formulations rely on narrow particle-size distributions and specialty flow modifiers, yet maintaining uniformity on complex geometries remains challenging. Allnex's ultra-low-temperature hybrids cure at 125 °C and improve leveling, but they necessitate tighter humidity control and advanced application hardware. Evonik's spherical SPHERILEX AC 45 pigments enhance dispersion but require reformulation work across the value chain. Until turnkey solutions reach market maturity, liquid systems retain a technical edge in select high-gloss sectors.
Other drivers and restraints analyzed in the detailed report include:
- Growth of architectural aluminum extrusion demand
- Superior recyclability and first-pass transfer efficiency
- High retrofit CAPEX for liquid-to-powder conversion
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyester maintained 42.01% of the Europe Powder Coatings market share in 2025, translating to the largest slice of the Europe Powder Coatings market size. Its popularity stems from favorable economics, broad color latitude, and established supply chains that serve both facade panels and general industrial machinery. Formulators have extended performance envelopes by introducing super-durable grades that meet AAMA 2604 and Qualicoat Class 2 specifications. Conversely, polyurethane grades are projected to grow at a 3.62% CAGR, as automotive manufacturers pursue lighter structures and extended corrosion warranties. Low-temperature urethane chemistries also enable coating of medium-density fiberboard (MDF) fixtures, opening incremental opportunities in European furniture hubs.
Technological advancements now center on curing efficiency. AkzoNobel's Interpon D2525 Low-E polyester requires just 150°C, cutting booth dwell times by 20% and widening applicability to heat-sensitive alloys. Allnex's CRYLCOAT 4488-0 offers decade-long Florida exposure resistance, while TGIC-free systems dominate new capacity due to impending toxicological re-classifications. Epoxy resins continue to underpin pipeline valves and chemical reactors; hybrids bridge decorative and functional needs; acrylics target ultra-weatherable signage; and niche thermoplastics serve household-appliance and anti-graffiti segments. Across these chemistries, powder suppliers increasingly tout Environmental Product Declarations (EPDs), aligning formulations with customer carbon audits.
Complete Report Scope:
- By Resin Type
- Epoxy
- Polyester
- Epoxy-Polyester (Hybrid)
- Polyurethane
- Acrylic
- Other Resin Type (Thermoplastic (Polyvinyl Chloride, Polyolefins,etc.))
- By End-user Industry
- Architecture and Decorative
- Automotive
- Industrial
- Other End-user Industries (Furniture, Appliances, etc.)
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Benelux
- NORDIC Countries
- Rest of Europe
List of Companies Covered in this Report:
- Akzo Nobel N.V.
- Allnex GMBH
- Axalta Coating Systems, LLC
- BASF SE
- Beckers Group
- CWS Powder Coatings GmbH
- DSM
- IFS Coatings
- IGP Pulvertechnik AG
- Jotun
- Kansai Paint Co., Ltd.
- Nippon Paint Holdings Co., Ltd.
- PPG Industries Inc.
- Protech Group
- Pulverit S.p.A.
- Sika AG
- Teknos Group
- The Sherwin-Williams Company
- Tiger Coatings GmbH & Co KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent EU VOC and carbon-neutrality regulations
- 4.2.2 Rising automotive OEM and aftermarket powder usage
- 4.2.3 Growth of architectural aluminium extrusion demand
- 4.2.4 Superior recyclability and first-pass transfer efficiency
- 4.2.5 Low-temperature cure powders enable MDF and plastics
- 4.3 Market Restraints
- 4.3.1 Difficulty in achieving <30 µm smooth films
- 4.3.2 High retrofit CAPEX for liquid-to-powder conversion
- 4.3.3 EU anti-dumping duties inflating epoxy resin prices
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Epoxy
- 5.1.2 Polyester
- 5.1.3 Epoxy-Polyester (Hybrid)
- 5.1.4 Polyurethane
- 5.1.5 Acrylic
- 5.1.6 Other Resin Type (Thermoplastic (Polyvinyl Chloride, Polyolefins,etc.))
- 5.2 By End-user Industry
- 5.2.1 Architecture and Decorative
- 5.2.2 Automotive
- 5.2.3 Industrial
- 5.2.4 Other End-user Industries (Furniture, Appliances, etc.)
- 5.3 By Geography
- 5.3.1 Germany
- 5.3.2 United Kingdom
- 5.3.3 France
- 5.3.4 Italy
- 5.3.5 Spain
- 5.3.6 Benelux
- 5.3.7 NORDIC Countries
- 5.3.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Allnex GMBH
- 6.4.3 Axalta Coating Systems, LLC
- 6.4.4 BASF SE
- 6.4.5 Beckers Group
- 6.4.6 CWS Powder Coatings GmbH
- 6.4.7 DSM
- 6.4.8 IFS Coatings
- 6.4.9 IGP Pulvertechnik AG
- 6.4.10 Jotun
- 6.4.11 Kansai Paint Co., Ltd.
- 6.4.12 Nippon Paint Holdings Co., Ltd.
- 6.4.13 PPG Industries Inc.
- 6.4.14 Protech Group
- 6.4.15 Pulverit S.p.A.
- 6.4.16 Sika AG
- 6.4.17 Teknos Group
- 6.4.18 The Sherwin-Williams Company
- 6.4.19 Tiger Coatings GmbH & Co KG
7 Market Opportunities & Future Outlook
- 7.1 White-Space and Unmet-Need Assessment