|
시장보고서
상품코드
2120353
자동차용 마이크로모터 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Automotive Micro Motor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
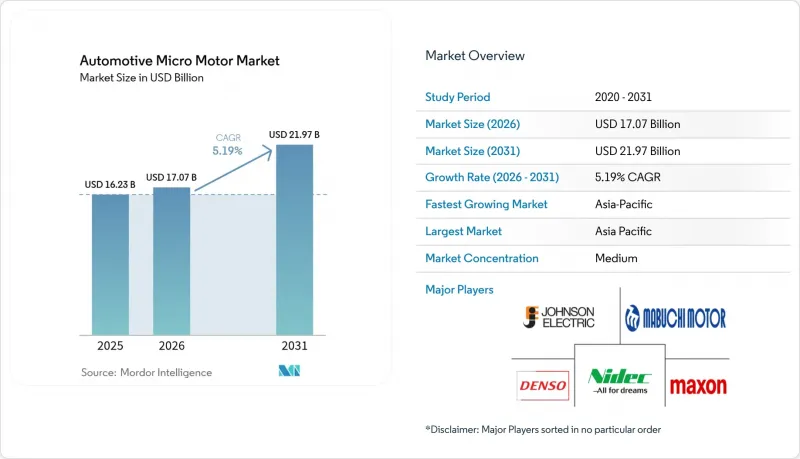
에 의하면, 2026년 자동차용 마이크로모터 시장 규모는 170억 7,000만 달러로 추정되고 2025년 162억 3,000만 달러에서 확대해, 2031년에는 219억 7,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 5.19%로 성장할 것으로 전망됩니다.
본 보고서는 소비 전력(11V 미만, 12-24V, 기타), 모터 유형(DC 모터 및 AC 모터), 기술(브러시형 마이크로모터 및 브러쉬리스 마이크로모터), 용도(차체 전자기기, 기타),차종(승용차 및 상용차), 판매 채널(OEM 및 애프터마켓), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대)으로 제시되어 있습니다.
세계의 자동차용 마이크로모터 시장 동향 및 인사이트
EV 생산 대수의 급증
세계 전기차 출하 대수는 경차 전체의 성장률을 지속적으로 상회하고 있으며, 각 순수 전기차 모델은 열 관리, 공기역학적 성능, 조향, 제동, 배터리 팩 냉각을 위해 수십 개의 보조용 마이크로모터에 의존하고 있습니다. 『Assembly Magazine』은 2034년까지 구동 모터 생산 대수가 4배로 급증하여 1억 2,000만 대를 넘어설 것으로 예측하고 있으며, 이러한 추세는 전체 하위 시스템에 걸쳐 소형 모터에 대한 수요 증가로 파급되고 있습니다. 2023년 중국의 자동차 수출 대수가 491만 대에 달하고, 일본을 추월한 것은 이러한 변화를 반영한 것이며, 자동차용 마이크로모터 시장의 상당 부분이 해당 지역에 집중되어 있습니다. 프리미엄 전기차(EV)에서 800V 아키텍처의 보급은 실리콘 카바이드(SiC) 소자를 기반으로 하는 마이크로모터 제어 전자 장치의 성능 기준을 한층 더 높였으며, 공급업체들에게 견고하고 고주파를 지원하는 드라이버 모듈 개발을 촉구하고 있습니다.
48V 마일드 하이브리드 아키텍처의 부상
기존의 12V 전기 시스템에서 48V 시스템으로의 전환을 통해 자동차 제조업체는 연료 소비를 최대 15%까지 절감할 수 있을 뿐만 아니라, 액티브 서스펜션, 스타트-스톱 시스템, 전동 슈퍼차저와 같은 분야에서 마이크로모터의 새로운 용도를 개척할 수 있게 됩니다. CLEPA는 2025년까지 신차 10대 중 1대가 48V 시스템을 탑재할 것으로 예측했습니다. 이에 따라 48V 배터리 시장도 확대될 것으로 예상되며, 자동차용 마이크로모터 시장에는 설계 채택의 큰 기회가 찾아올 것입니다. 테슬라가 ‘사이버트럭’에 48V 배선을 채택함에 따라 업계의 전환이 가속화되고 있지만, 기존 자동차 제조업체들은 고전압에 대응하기 위해 하네스, 커넥터, 검증 도구를 전면적으로 재검토해야 하는 상황에 직면해 있습니다.
희토류 자석 가격 상승 추세
영구 자석의 가격 변동은 자동차용 마이크로모터 공급업체에게 가장 심각한 비용상의 과제입니다. 네오디뮴의 현물 가격은 지난 1년간 42% 하락했으나, 중국이 수출 규제를 강화하고 있어 장기적인 공급 리스크가 우려되고 있습니다. 이미 자석 출하가 지연되었을 때, 일본의 스즈키 ‘스위프트’ 생산 라인 등 차량 프로그램에서 생산 일시 중단 사례가 보고된 바 있습니다. 업계 각사는 조달처 다각화를 추진하고 있습니다. 니덱은 환율 및 지정학적 충격에 대한 완충책으로, 미국에서 생산되는 노베온사의 ‘에코플럭스’ 자석을 채택하는 2025년까지의 계약을 체결했습니다.
부문 분석
2025년 자동차용 마이크로모터 시장에서 12-24V 등급은 42.14%의 점유율을 차지했으며, 이는 경차 전체 차종에서 볼 수 있는 기존의 전기 아키텍처를 반영한 것입니다. 그러나 OEM 각사가 효율 향상을 위해 마일드 하이브리드나 800V EV 구동계를 채택하고 있기 때문에 고전압(48V 초과) 부문은 5.61%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 이러한 변화로 인해 저게이지 와이어 하네스와 결합된 고토크 브러쉬리스 유닛용 자동차용 마이크로모터 시장 규모가 확대되고 있으며, 저항 손실 감소와 열 부하 경감이 도모되고 있습니다. 테슬라의 48V 하네스 도입은 차기 전기 규격에 대한 업계 전반의 폭넓은 합의를 뒷받침하고 있습니다.
CLEPA는 48V 기술을 통해 연료 소비를 최대 15%까지 절감할 수 있음을 확인했으며, 유럽의 CO2 배출 규제 대응 전략에 대한 도입이 가속화되고 있습니다. 이에 따라 각 공급업체들은 24V 송풍기 모터부터 400V 트랙션 보조 모터에 이르기까지를 아우르는 모듈식 고정자 제품군을 확충하여 플랫폼 재사용을 극대화하고 있습니다. 신흥 저전력(11V 미만) 틈새 시장은 센서 노드에서 여전히 중요하지만, 매출에서 차지하는 비중은 제한적입니다.
DC 모터는 윈도우 리프터, 시트 조절기, HVAC 플랩을 위한 비용 효율적인 설계 덕분에 2025년 매출의 59.10%를 차지했습니다. 그럼에도 불구하고, AC 모터는 가변 속도 운전을 통해 스티어링, 브레이크, 냉각수 펌프의 에너지 소비를 줄일 수 있어 6.29%라는 견실한 연평균 성장률(CAGR)을 기록하고 있습니다. 따라서 자동차용 마이크로모터 시장에서는 온-오프 구동에 DC 플랫폼이 여전히 유효한 반면, 인버터 구동 AC 옵션이 전동 파워 스티어링의 효율 목표를 충족시키는 등 균형 잡힌 제품 구성을 볼 수 있습니다.
닛덴산(Nidec)의 ‘SynRA’ 시리즈는 희토류 자석을 배제하고 공급 탄력성을 높이는 동기 릴랙턴스 토크 방식으로의 전환을 보여주는 좋은 예입니다. 존슨 일렉트릭의 2023/24 회계연도 매출은 두 모터 유형 모두에서 OEM의 채택이 지속되고 있음을 보여주며, 다중 기술 전략의 유효성을 뒷받침하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 48.10%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.03%를 기록하며 이 지역은 자동차용 마이크로모터 시장의 선두 자리를 계속 유지할 것입니다. 중국의 수출업체들은 2023년에 491만 대의 차량을 수출하여 일본을 제치고, 마이크로모터, 반도체, 자석에 대한 광범위한 공급 기반을 확립했습니다. 닛폰덴산은 다롄 복합 시설의 직원 수를 최대 50% 증원할 계획이며, 이 시설을 연간 100만 대의 생산 능력을 갖춘 세계 최대의 EV 모터 생산 거점으로 탈바꿈시킬 예정입니다. 태국과 인도네시아는 통합된 전기차 공급망을 구축하기 위해 새로운 투자를 유치하고 있으며, 지역 내 조달 옵션을 확대되고 있습니다.
유럽에서는 엄격한 배기 가스 규제 목표를 배경으로 48V 시스템 도입이 진행되고 있으며, 고급차 제조업체들이 능동형 공기역학 기술을 채택하는 등 꾸준한 진전이 나타나고 있습니다. CLEPA의 마일드 하이브리드 파워트레인 추진과 셰플러와 비테스코의 2024년 합병은 현지 모터 기술력을 강화하고 있습니다. 독일의 스타트업 기업 DeepDrive는 자석 사용량을 50% 줄인 듀얼 로터 설계의 상용화를 위해 3,350만 달러의 자금 조달에 성공하며, 유럽 내 경량화 혁신을 위한 노력이 두드러지고 있습니다.
북미에서는 생산의 국내 회귀(리쇼어링) 정책과 테슬라가 주도하는 전압 표준화가 원동력이 되고 있습니다. KPS 캐피탈 파트너스가 지멘스의 이노모틱스(Inomotics) 사업부를 35억 유로에 인수한 것은 고부가가치 모터 브랜드에 대한 사모펀드의 활발한 수요를 보여줍니다.
남미는 브라질과 아르헨티나의 생산 현장에서 전자 부품 채택이 확대됨에 힘입어, 낮은 기저에서 높은 성장률을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, automotive micromotor market size in 2026 is estimated at USD 17.07 billion, growing from 2025 value of USD 16.23 billion with 2031 projections showing USD 21.97 billion, growing at 5.19% CAGR over 2026-2031.
This report is Segmented by Power Consumption (Below 11V, 12 To 24V, and More), Motor Type (DC Motor and AC Motor), Technology (Brushed Micromotor and Brushless Micromotor), Application (Body Electronics and More), Vehicle Type (Passenger Cars and Commercial Vehicles), Sales Channel (OEM and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Micro Motor Market Trends and Insights
Surge in EV Production Volumes
Global EV shipments continue to outpace overall light-vehicle growth, and each pure battery model relies on dozens of auxiliary micromotors for thermal management, aerodynamics, steering, braking and battery-pack cooling. Assembly Magazine forecasts a fourfold jump in traction-motor output to more than 120 million units by 2034, a trend that cascades into parallel demand for smaller motors across sub-systems. China's rise to 4.91 million vehicle exports in 2023, surpassing Japan, reflects this shift and concentrates much of the automotive micromotor market in the region. Higher 800 V architectures in premium EVs further raise the performance bar for micromotor control electronics built around silicon-carbide devices, pushing suppliers toward robust, high-frequency driver modules.
Rise in 48V Mild-Hybrid Architectures
Moving from traditional 12 V electrics to 48 V boards allows automakers to cut fuel use by up to 15% while unlocking new micromotor applications in active suspension, start-stop and electric superchargers. CLEPA projects 48 V systems in one out of every ten new cars by 2025. The accompanying 48 V battery segment is anticipated to climb, giving the automotive micromotor market a sizeable design-in opportunity. Tesla's adoption of 48 V wiring in the Cybertruck accelerates industry conversion, although legacy manufacturers must overhaul harnesses, connectors and validation tools to cope with higher voltages.
Up-trend in Rare-Earth Magnet Prices
Permanent-magnet pricing volatility is the most acute cost challenge for automotive micromotor suppliers. Neodymium spot values slid 42% over the past year, yet long-term supply risk looms as China tightens export controls. Vehicle programmes already report production pauses, such as Suzuki's Swift line in Japan, when magnet shipments stalled. Industry players are diversifying sourcing: Nidec signed a 2025 deal to adopt Noveon Ecoflux magnets produced in the United States, buffering currency and geopolitical shocks.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Luxury & Premium Interiors
- Vehicle Lightweighting & Component Miniaturisation Push
- Constant Tech Upgrades Inflating Unit Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 12 to 24 V class held 42.14% of the 2025 automotive micromotor market share, reflecting legacy electrical architectures across the light-vehicle parc. Higher-voltage (More than 48 V) segments, however, register the fastest 5.61% CAGR as OEMs adopt mild-hybrid and 800 V EV drivetrains for efficiency gains. This shift enlarges the automotive micromotor market size for high-torque brushless units paired with low-gauge wiring harnesses, cutting resistive losses and easing thermal loads. Tesla's 48 V harness rollout underscores broad industry alignment on the next electrical standard.
CLEPA confirms that 48 V technology can trim fuel use by up to 15%, accelerating its inclusion in European CO2-compliance strategies. Suppliers therefore scale modular stator families that cover 24 V blower motors through 400 V traction auxiliaries, maximising platform reuse. Emerging low-power (Less than 11 V) niches remain relevant for sensor nodes yet represent a limited portion of revenue.
DC motors commanded 59.10% of 2025 revenue thanks to cost-effective designs for window lifts, seat adjusters and HVAC flaps. Nevertheless, AC machines record a robust 6.29% CAGR because variable-speed operation reduces energy draw in steering, braking and coolant pumps. The automotive micromotor market therefore witnesses a balanced portfolio where DC platforms remain viable for on-off actuation, while inverter-driven AC options satisfy efficiency targets in electric power steering.
Nidec's SynRA line illustrates the push toward synchronous-reluctance architectures that remove rare-earth magnets, boosting supply resilience. Johnson Electric's FY23/24 sales indicate sustained OEM uptake across both motor types, validating a multi-technology roadmap.
Complete Report Scope:
- By Power Consumption
- Below 11 V
- 12 to 24 V
- 25 to 48 V
- Above 48 V
- By Motor Type
- DC Motor
- AC Motor
- By Technology
- Brushed Micromotor
- Brushless Micromotor
- By Application
- Body Electronics (window, seat, mirror)
- Powertrain & Drivetrain Systems
- Chassis & Steering
- Safety & ADAS Modules
- Infotainment & Connectivity
- By Vehicle Type
- Passenger Cars
- Commercial Vehicles
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia & New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 48.10% of global revenue in 2025, and its 6.03% CAGR to 2031 keeps the region at the forefront of the automotive micromotor market. Chinese exporters shipped 4.91 million vehicles in 2023, surpassing Japan and consolidating a broad supply base for micromotors, semiconductors and magnets. Nidec plans to raise headcount at its Dalian complex by up to 50%, turning it into the world's largest EV-motor site capable of one-million-unit output a year. Thailand and Indonesia court fresh investment to create integrated EV supply chains, broadening regional sourcing options.
Europe advances at a steady rate as strict emissions targets spur 48 V roll-outs and premium OEMs adopt active aerodynamics. CLEPA's promotion of mild-hybrid powertrains and Schaeffler's 2024 merger with Vitesco bolster local motor expertise. German start-up DeepDrive secured USD 33.5 million to commercialise dual-rotor designs using 50% fewer magnets, highlighting Europe's push for material-light innovations.
North America is powered by reshoring policies and Tesla-led voltage standardisation. KPS Capital Partners' EUR 3.5 billion takeover of Siemens' Innomotics division signals private equity appetite for high-value motor brands.
South America exhibits the highr growth off a smaller base, aided by rising electronics content in Brazilian and Argentine production.
- Nidec Corporation
- Johnson Electric Holdings Ltd.
- Mabuchi Motor Co., Ltd.
- Maxon Motor AG
- Mitsuba Corporation
- Buhler Motor GmbH
- Denso Corporation
- Robert Bosch GmbH
- Continental AG
- Valeo SA
- Brose Fahrzeugteile SE
- Ametek Inc.
- MinebeaMitsumi Inc.
- Mitsumi Electric Co., Ltd.
- Shenzhen Kinmore Motor Co.
- Constar MicroMotor
- Wellings Holdings Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in EV production volumes
- 4.2.2 Growing demand for luxury & premium interiors
- 4.2.3 Vehicle lightweighting & component miniaturisation push
- 4.2.4 Rise in 48 V mild-hybrid architectures
- 4.2.5 Integration in active aerodynamics systems
- 4.2.6 Proliferation of cabin wellness features (ionizers, scent dispensers)
- 4.3 Market Restraints
- 4.3.1 Up-trend in rare-earth magnet prices
- 4.3.2 Constant tech upgrades inflating unit costs
- 4.3.3 Tight tolerance specs raising qualification costs
- 4.3.4 Emerging piezo-actuator substitutes
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Power Consumption
- 5.1.1 Below 11 V
- 5.1.2 12 to 24 V
- 5.1.3 25 to 48 V
- 5.1.4 Above 48 V
- 5.2 By Motor Type
- 5.2.1 DC Motor
- 5.2.2 AC Motor
- 5.3 By Technology
- 5.3.1 Brushed Micromotor
- 5.3.2 Brushless Micromotor
- 5.4 By Application
- 5.4.1 Body Electronics (window, seat, mirror)
- 5.4.2 Powertrain & Drivetrain Systems
- 5.4.3 Chassis & Steering
- 5.4.4 Safety & ADAS Modules
- 5.4.5 Infotainment & Connectivity
- 5.5 By Vehicle Type
- 5.5.1 Passenger Cars
- 5.5.2 Commercial Vehicles
- 5.6 By Sales Channel
- 5.6.1 OEM
- 5.6.2 Aftermarket
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Russia
- 5.7.3.7 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Australia & New Zealand
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 South Africa
- 5.7.5.5 Rest of Middle East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Nidec Corporation
- 6.4.2 Johnson Electric Holdings Ltd.
- 6.4.3 Mabuchi Motor Co., Ltd.
- 6.4.4 Maxon Motor AG
- 6.4.5 Mitsuba Corporation
- 6.4.6 Buhler Motor GmbH
- 6.4.7 Denso Corporation
- 6.4.8 Robert Bosch GmbH
- 6.4.9 Continental AG
- 6.4.10 Valeo SA
- 6.4.11 Brose Fahrzeugteile SE
- 6.4.12 Ametek Inc.
- 6.4.13 MinebeaMitsumi Inc.
- 6.4.14 Mitsumi Electric Co., Ltd.
- 6.4.15 Shenzhen Kinmore Motor Co.
- 6.4.16 Constar MicroMotor
- 6.4.17 Wellings Holdings Ltd.