

|
시장보고서
상품코드
2120378
로봇 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Robotics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
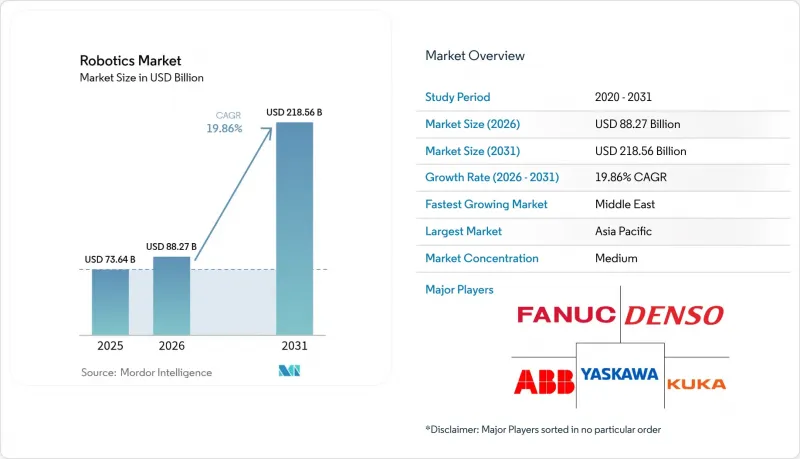
에 따르면 2026년 로봇 시장 규모는 882억 7,000만 달러로 추정되고 있으며, 2025년 736억 4,000만 달러에서 성장하며, 2031년에는 2,185억 6,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지의 연평균 성장률(CAGR)은 19.86%에 달할 것으로 전망됩니다.
이 보고서는 로봇 유형(산업용 로봇, 서비스 로봇 등), 구성 요소(하드웨어, 소프트웨어, 서비스), 용도(제조·조립, 물류·창고, 의료·외과 등), 최종사용자 산업(자동차, 전자·반도체, 식품 및 음료 등) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 로봇 시장의 동향 및 인사이트
심화되는 노동력 부족이 자동화 수요를 견인
일본, 미국 및 서유럽 대부분 지역의 인구 통계학적 역풍으로 인해 자동화의 목적이 비용 절감에서 생산 능력 확보로 전환되었습니다. 2024년에는 G7 국가들의 제조업 전체에서 공장 미충족 구인 건수가 200만 건을 넘어섰으며, 한편 일본의 로봇 밀도(직원 1만 명당)는 399대에 달해 사상 최고치를 기록했습니다. 스텔란티스(Stellantis)와 같은 자동차 제조업체들은 반복성 스트레스 장애를 완화하면서 인력을 확보하는 ‘인간 중심형’ 로봇 셀을 도입하고 있으며, 이는 협동형 도입을 향한 미묘한 변화를 시사합니다. 이러한 구조적 격차는 경기 순환을 초월하여 지속되므로 전 세계 로봇 시장이 그 혜택을 누리고 있으며, 공급업체에게는 GDP 변동과 무관한 예측 가능한 수요 기반이 마련되고 있습니다.
가동 시간당 로봇 평균 가격 하락
부품의 상품화와 양산화로 인해 2024년 이후 협업 로봇의 가격은 연간 약 15% 하락하는 반면, 소프트웨어 업그레이드를 통해 가격 대비 성능 비율은 2배로 높아졌습니다. 중국의 공급업체들은 엔트리급 휴머노이드 로봇을 19만 9,000위안(2만 7,512달러)에 판매하여, 소규모 공장도 자본 예산 범위 내에서 로봇을 도입할 수 있게 했습니다. 하드웨어 비용의 하락에 따라 중소 제조업체 및 신흥 시장 제조업체의 도입 곡선이 가팔라지면서, 그 결과 전 세계 로봇 시장의 잠재 고객층이 확대되고 있습니다.
중소기업의 로봇 도입에 있으며, 기술 격차가 여전히 존재
여전히 68%의 중소기업이 로봇 도입에 필요한 엔지니어링 인력을 확보하지 못해 투자 회수 기간이 길어지고 가동률이 떨어지고 있습니다. 시스템 통합사업자는 도시 지역의 거점에 집중되어 있으며, 지방 기업에 대한 서비스 제공이 미흡합니다. 기술 개발 가속화나 턴키 서비스 모델이 도입되지 않는 한, 세계 로봇 시장에는 여전히 많은 미개발 잠재 수요가 남아 있습니다.
부문 분석
2025년, 산업용 로봇은 높은 처리량을 자랑하는 자동차 및 전자기기 조립 라인의 지속적인 수요에 힘입어 전 세계 로봇 시장 전체의 71.04%를 차지했습니다. 반면, 협업 로봇은 안전 인증을 받은 힘 센서와 중소기업의 예산 범위 내에서 구입 가능한 3만 달러 미만의 가격 정책에 힘입어 2031년까지 연평균 성장률(CAGR) 25.64%로 성장하고 있습니다. 이러한 변화는 울타리로 둘러싸인 생산 라인이 아닌, 유연하고 인간의 감독 하에 운영되는 셀이 세계 로봇 시장의 다음 도입 물결을 주도할 것임을 시사합니다.
중국 협업 로봇 제조사의 급증으로 2017-2024년 사이 국내 점유율은 35%에서 73%로 상승했으며, 경쟁이 심화됨에 따라 전 세계 판매 대수의 증가세도 가속화되었습니다. 서비스 로봇의 틈새 시장도 호황을 누리고 있으며, 2025년에는 수술용 시스템 시장 규모가 41억 8,000만 달러를 돌파하여 의료 분야가 가장 빠르게 성장하는 최종 용도임을 재확인했습니다. 이러한 다양화로 인해 세계 로봇 시장의 경기 변동이 완화되었으며, 하드웨어 공급업체들은 특정 부문의 경기 침체 영향을 덜 받게 되었습니다.
2025년 지출에서 하드웨어가 차지하는 비중은 여전히 63.12%였으나, 인공지능이 주요 가치 창출 요인으로 부상함에 따라 소프트웨어 매출은 연평균 22.91% 성장할 것으로 전망됩니다. 현재, 고급 제어 스택에는 클라우드 분석 및 강화 학습이 통합되어 있으며, ABB의 OmniCore 플랫폼은 사이클 타임을 25% 단축하고 전력 소비를 20% 절감하고 있습니다. 고객이 자본 지출(CAPEX)에서 운영 비용(OPEX) 모델로 전환함에 따라 구독형 ‘Robot-as-a-Service(RaaS)’ 세계 시장 규모는 2031년까지 3배로 증가할 것으로 예측됩니다.
통합, 원격 모니터링, 예측 유지보수 등을 포괄하는 서비스 수익은 벤더 종속성을 더욱 공고히 할 것입니다. 그 결과, 소프트웨어와 서비스의 경계가 모호해지며, 업데이트 권한 및 사이버 보안 패치가 다년 계약에 포함되게 됩니다. 이러한 추세는 수익 구조를 혁신적으로 변화시키고, 글로벌 로봇 시장에서 순수 하드웨어 중심의 신규 진입 기업에 대한 진입 장벽을 높이고 있습니다.
지역별 분석
아시아태평양은 2025년 전 세계 로봇 시장 점유율의 37.72%를 차지했습니다. 이는 중국의 연간 43만 대에 달하는 산업용 로봇 도입 대수와 전 세계 로봇 관련 특허 부여 건수의 3분의 2가 지원하고 있습니다. 중국의 공장에서는 리튬이온 배터리 및 가전제품 생산 라인에 로봇이 도입되고 있는 반면, 국내 브랜드들은 수출을 확대함으로써 지역의 비용 경쟁력을 세계 로봇 시장에 반영하고 있습니다. 일본에서는 중국의 수요 회복과 국내 인구 구조적 압박으로 인해 2024년에 파낙(FANUC)이 1,802억 엔(16억 4,000만 달러)의 이익을 기록했습니다. 한국에서는 26억 달러 규모의 민관 협력 프로그램을 통해 휴머노이드 로봇 기술의 노하우를 배터리 공장 자동화에 활용하고 있으며, 전략적인 우선순위 설정이 강조되고 있습니다.
중동에서는 정부계 펀드가 탄화수소 잉여 자금을 산업 디지털화, 물류, 의료용 로봇에 투입함에 따라 2031년까지 연평균 성장률(CAGR)이 21.31%로 가장 높게 나타나고 있습니다. 아랍에미리트(UAE)의 자유무역지역에서는 지역 E-Commerce 흐름에 대응하기 위해 창고용 AMR의 시범 운영이 이루어지고 있으며, 계절별 이주 노동자에 대한 과도한 의존도를 줄이고 있습니다. 또한 국가 프로그램을 통해 첨단 제조 허브에 자금을 지원하고, 전 세계 시스템 통합사업자를 유치함으로써 세계 로봇 시장의 잠재 고객 기반을 확대하고 있습니다.
북미의 수요는 CHIPS법에 힘입은 반도체 제조 공장과, 앤드릴(Anduril)사에 대한 6억 4,220만 달러 규모의 해군 대 드론 계약 등 방위 계약에 힘입어 견고한 모습을 유지하고 있습니다. 유럽에서는 안전한 인간-로봇 협업에 관한 기준과 지속가능성 목표에 주력하고 있으며, 독일이 인공지능(AI) 통합을 위해 연간 6,900만 유로(7,500만 달러)의 자금을 지원하고 있는 점이 이를 지원하고 있습니다. 두 지역 모두 범용 하위 어셈블리 제조를 아시아로 아웃소싱하는 한편, 고부가가치 소프트웨어 및 시스템 통합에 대한 투자를 확대하고 있으며, 이는 세계 로봇 시장에서 ‘바벨 전략’을 반영하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.02According to Mordor Intelligence, robotics market size in 2026 is estimated at USD 88.27 billion, growing from 2025 value of USD 73.64 billion with 2031 projections showing USD 218.56 billion, growing at 19.86% CAGR over 2026-2031.
This report is Segmented by Robot Type (Industrial Robots, Service Robots, and More), Component (Hardware, Software, and Services), Application (Manufacturing and Assembly, Logistics and Warehousing, Medical and Surgical, and More), End-User Industry (Automotive, Electronics and Semiconductor, Food and Beverage, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Robotics Market Trends and Insights
Rising Labour-Shortage Led Automation Demand
Demographic headwinds in Japan, the United States, and much of Western Europe have shifted automation from cost-saving to capacity-assurance mode. Unfilled factory vacancies topped 2 million roles across G-7 manufacturing in 2024, while Japan's robot density reached 399 units per 10,000 employees, the highest on record. Automakers such as Stellantis adopted human-centric robotic cells that trim repetitive strain injuries yet safeguard headcount, signalling a nuanced push toward collaborative deployment. The global robotics market benefits because these structural gaps persist through economic cycles, giving vendors a predictable demand base that decouples from GDP volatility.
Declining Average Robot Price Per Functional Hour
Component commoditisation and scale production cut collaborative robot prices by roughly 15% a year post-2024, while software upgrades doubled performance relative to price. Chinese suppliers even marketed entry-level humanoids at CNY 199,000 (USD 27,512), placing robots within small-factory capital budgets. As hardware costs slide, adoption curves steepen among small and emerging-market manufacturers, thereby widening the addressable pool for the global robotics market.
Persistent SME Integration Skill-Gap
Sixty-eight percent of SMEs still lack engineering talent for robotics deployment, prolonging payback periods and dampening utilisation rates. Integrators cluster in urban hubs, leaving regional firms underserved. Without accelerated skills development or turnkey service models, the global robotics market leaves considerable latent demand untapped.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Low-Code Robot-Programming Platforms
- Fiscal Incentives for Reshoring Manufacturing in G-7
- Geopolitical Export-Control on Advanced Servos
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Industrial robots accounted for 71.04% of the global robotics market in 2025, riding sustained demand from high-throughput automotive and electronics assembly lines. Yet collaborative robots expand at a 25.64% CAGR to 2031, underpinned by safety-certified force-sensing and sub-USD 30,000 price tags that place them within SME budgets. This pivot signals that flexible, human-supervised cells, rather than fenced-off lines, will drive the next deployment wave of the global robotics market.
A surge in Chinese cobot makers lifted their domestic share from 35% to 73% between 2017 and 2024, heightening price competition and accelerating worldwide unit growth. Service-robot niches also flourish: surgical systems surpassed USD 4.18 billion in 2025, reaffirming healthcare as the fastest-rising end-use. This diversification reduces cyclicality for the global robotics market and cushions hardware vendors against single-sector downturns.
Hardware still represented 63.12% of 2025 spending, but software revenue is set to grow 22.91% annually as artificial intelligence becomes the primary value driver. Higher-level control stacks now incorporate cloud analytics and reinforcement learning that deliver 25% faster cycle times with 20% lower electricity use on ABB's OmniCore platform. The global robotics market size for subscription-based Robot-as-a-Service is projected to treble by 2031 as customers migrate from capital expenditure toward operating expenditure models.
Service revenues, covering integration, remote monitoring, and predictive maintenance, further solidify vendor lock-in. As a result, software and services blur, embedding update rights and cyber-security patches into multi-year contracts. This trend rewires profit pools and raises entry barriers for purely hardware-centric challengers within the global robotics market.
Complete Report Scope:
- By Robot Type
- Industrial Robots
- Service Robots
- Collaborative (Cobots)
- Mobile/AMR
- By Component
- Hardware
- Software
- Services (Integration, RaaS)
- By Application
- Manufacturing and Assembly
- Logistics and Warehousing
- Medical and Surgical
- Defense and Security
- Inspection and Maintenance
- Cleaning and Sanitation
- By End-User Industry
- Automotive
- Electronics and Semiconductor
- Food and Beverage
- Healthcare Providers
- Military and Defense
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific secured 37.72% of global robotics market share in 2025, anchored by China's 430,000 annual industrial-robot installations and two-thirds of worldwide robotics patent grants. Chinese factories integrate robots into lithium-ion battery and consumer-electronics lines, while domestic brands escalate exports, embedding regional cost competitiveness into the global robotics market. Japan posted JPY 180.2 billion (USD 1.64 billion) profit at Fanuc in 2024 on revived Chinese demand and domestic demographic pressure. South Korea's USD 2.6 billion public-private programme channels humanoid expertise toward battery-plant automation, underscoring strategic prioritisation.
The Middle East registers the highest 21.31% CAGR to 2031 as sovereign wealth vehicles divert hydrocarbons surplus into industrial digitalisation, logistics, and healthcare robotics. Free-trade zones in the United Arab Emirates trial warehouse AMRs to service regional e-commerce flows, reducing over-reliance on seasonal migrant labour. National programmes additionally fund advanced manufacturing hubs that attract global integrators, amplifying the addressable base for the global robotics market.
North American demand remains resilient, propelled by CHIPS-Act-backed fabs and defence contracts such as the USD 642.2 million Navy counter-drone award to Anduril. Europe focuses on safe human-robot collaboration standards and sustainability targets, helped by EUR 69 million (USD 75 million) in annual German funding for artificial-intelligence integration. Both regions increasingly outsource commodity sub-assemblies to Asia while investing in high-value software and integration, reflecting a barbell strategy within the global robotics market.
- ABB Ltd.
- Fanuc Corporation
- Yaskawa Electric Corporation
- KUKA AG
- Kawasaki Heavy Industries Ltd
- Universal Robots A/S (Teradyne)
- Denso Corporation
- Mitsubishi Electric Corporation
- Omron Corporation
- Staubli International AG
- Epson Robots (Seiko Epson)
- Comau SpA
- Nachi-Fujikoshi Corp.
- Toshiba Corporation
- Intuitive Surgical Inc.
- Stryker Corporation
- iRobot Corporation
- Boston Dynamics Inc.
- Locus Robotics Corp.
- DJI Technology Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising labour-shortage led automation demand
- 4.2.2 Declining average robot price per functional hour
- 4.2.3 Proliferation of low-code robot-programming platforms
- 4.2.4 Fiscal incentives for reshoring manufacturing in G-7
- 4.2.5 Warehouse AMR roll-outs by e-commerce 3PLs
- 4.2.6 Nation-level humanoid RandD missions (e.g., China 2025)
- 4.3 Market Restraints
- 4.3.1 Persistent SME integration skill-gap
- 4.3.2 Geopolitical export-control on advanced servos
- 4.3.3 Rare-earth magnet price volatility
- 4.3.4 Cyber-security vulnerabilities in ROS deployments
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro Economic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Robot Type
- 5.1.1 Industrial Robots
- 5.1.2 Service Robots
- 5.1.3 Collaborative (Cobots)
- 5.1.4 Mobile/AMR
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services (Integration, RaaS)
- 5.3 By Application
- 5.3.1 Manufacturing and Assembly
- 5.3.2 Logistics and Warehousing
- 5.3.3 Medical and Surgical
- 5.3.4 Defense and Security
- 5.3.5 Inspection and Maintenance
- 5.3.6 Cleaning and Sanitation
- 5.4 By End-User Industry
- 5.4.1 Automotive
- 5.4.2 Electronics and Semiconductor
- 5.4.3 Food and Beverage
- 5.4.4 Healthcare Providers
- 5.4.5 Military and Defense
- 5.4.6 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABB Ltd.
- 6.4.2 Fanuc Corporation
- 6.4.3 Yaskawa Electric Corporation
- 6.4.4 KUKA AG
- 6.4.5 Kawasaki Heavy Industries Ltd
- 6.4.6 Universal Robots A/S (Teradyne)
- 6.4.7 Denso Corporation
- 6.4.8 Mitsubishi Electric Corporation
- 6.4.9 Omron Corporation
- 6.4.10 Staubli International AG
- 6.4.11 Epson Robots (Seiko Epson)
- 6.4.12 Comau SpA
- 6.4.13 Nachi-Fujikoshi Corp.
- 6.4.14 Toshiba Corporation
- 6.4.15 Intuitive Surgical Inc.
- 6.4.16 Stryker Corporation
- 6.4.17 iRobot Corporation
- 6.4.18 Boston Dynamics Inc.
- 6.4.19 Locus Robotics Corp.
- 6.4.20 DJI Technology Co. Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


