|
시장보고서
상품코드
2120419
탈크 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Talc - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
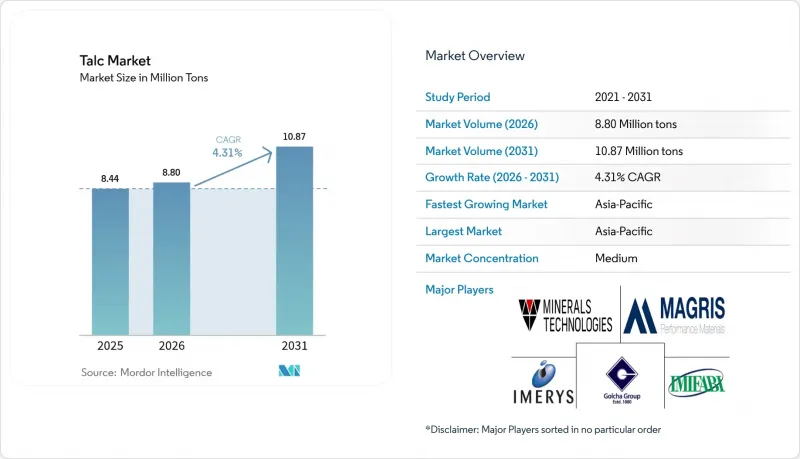
에 따르면 탈크 시장 규모는 2025년 844만 톤에서 2026년에는 880만 톤으로 확대되어, 2026년부터 2031년까지 CAGR 4.31%를 기록하며 2031년에는 1,087만 톤에 달할 것으로 예측됩니다.
본 보고서는 광상 유형(탈크·탄산염형, 탈크·클로라이드형), 최종사용자 산업(플라스틱·고무, 페인트·코팅, 세라믹, 펄프·종이, 퍼스널케어·화장품, 식품·음료, 기타 산업) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 톤 기준으로 제시되어 있습니다.
세계 탈크 시장의 동향 및 인사이트
자동차 경량화를 위한 PP 및 TPO의 꾸준한 채택
자동차 제조사들은 사출 성형 라인의 설비를 변경하지 않고도 연비 및 전기자동차(EV) 주행 거리에 관한 규제 요건을 충족하는 강성 대 중량 비율을 달성하기 위해 PP 및 TPO 컴파운드에 15%-25%의 탈크를 배합하고 있습니다. 이메리스는 2025년 우후에 4,300만 유로를 투자한 시설을 개설하여 배터리 하우징 및 내장 패널용 초미세 등급을 연간 3만 톤 공급하고 있습니다. OECD의 예측에 따르면, 동남아시아 및 동아시아의 플라스틱 사용량은 2019년 6,000만 톤에서 2060년까지 1억 5,000만 톤으로 증가할 것으로 예상되며, 자동차 및 전자 분야가 가장 급격한 증가를 주도할 것으로 보입니다. 말레이시아의 순환 경제 이니셔티브에 따라 2024년에는 폐차에서 1만 2,000톤의 PP 및 ABS가 회수될 것이며, 이 수치는 2030년까지 3배로 증가할 것으로 예상됩니다. 탈크의 핵형성 효과로 인해 성형 사이클이 8%-12% 단축되어, 가동률이 85%-90%인 Tier 1 공급업체의 생산량이 향상되고 있습니다.
아시아에서 건축용 도료의 수성화로의 전환이 진행되고 있습니다
중국의 GB30981.1-2025 규격에서는 실내용 도료의 VOC(휘발성 유기 화합물) 함량을 80 g/L로 제한하고 있어, 이에 따라 배합 제조업체는 더 많은 탈크를 배합해야 하는 수성 바인더를 채택할 수밖에 없습니다. 인도의 인도표준국(BIS)은 2026년 하반기 공표를 목표로 유사한 제한치를 마련 중입니다. 수성 도료에는 일반적으로 12%-18%의 탈크가 포함되어 있는데, 이는 용제형 도료의 8%-12%에서 증가한 수치입니다. 이는 탈크의 층상 판상 결정이 은폐력 저하를 보완하기 때문입니다. 태국 산업경제국에 따르면, 2024년 국내 탈크 생산량은 17.27% 증가했으며, 베트남, 인도네시아, 필리핀에서의 수요로 인해 수출도 14.73% 증가했습니다. 이산화티타늄과 비교하여, 탈크의 가격은 톤당 150-250달러이므로, 다른 첨가제의 인플레이션에도 불구하고 도료 제조업체는 소매 가격을 안정적으로 유지할 수 있습니다.
석면 관련 소송으로 인한 지속적인 비용
존슨앤드존슨은 2024년 5월, 화장품용 탈크와 관련된 6만 2,000건의 난소암 소송을 합의하기 위해 100억 달러를 제시했습니다. LTL 관리사의 잇따른 연방 파산법 제11장 신청이 기각됨에 따라, 이 제안은 여전히 불확실한 상태에 머물러 있어 업스트림 광산 업체들에게 불확실성이 장기화되고 있습니다. 미네랄스 테크놀러지스(Minerals Technologies)는 발레츠 미네랄스(Barrets Minerals)를 3,200만 달러에 매각한 후, 2025년 1분기에 계류 중인 684건의 소송에 대응하기 위한 신탁 기금으로 충당하기 위해 2억 1,500만 달러의 충당금을 계상했습니다. 이메리스(Imerys)사는 2025년 1월, 북미 사업 재편에 대해 채권자의 90% 승인을 얻었으나, 이로 인해 과거 부채를 분리할 수 있었던 반면, 대차대조표의 유연성은 제한되게 되었습니다. 2025년, 탈크 생산 업체의 1차 보험층 보험료는 40%-60% 상승한 반면, 총 보상 한도는 5,000만-1억 달러로 인하되어 중견 기업들은 자체 보험으로의 전환이나 화장품용 등급 사업에서 철수할 수밖에 없었습니다.
부문별 분석
2025년 생산량의 61.90%를 차지한 것은 탄산 탈크였습니다. 이는 중국, 인도, 브라질에 풍부한 변성암대가 존재하여 플라스틱, 도료, 세라믹용 비용 효율적인 광석이 생산되고 있기 때문입니다. 나머지 비중을 차지하는 클로라이트 탈크는 자동차 및 전자 산업 분야의 고객들이 많은 탄산 탈크 광석으로는 달성할 수 없는 50ppm 미만의 철분 제한을 부과하고 있기 때문에 연평균 성장률(CAGR) 4.76%로 확대될 전망입니다. 클로라이트 탈크는 철분 함유율이 0.05% 미만인 반면, 탄산염은 0.15%-0.30%이므로, 흰색 자동차 내장 부품의 색상 편차를 해소하고 화장품 배합 시 표백 비용을 절감합니다. 클로라이트 등급은 50-100달러의 프리미엄 가격이 책정되지만, 가마에서 배출되는 CO₂를 8%-12% 줄여 EU의 탄소 가격 제도 준수를 지원합니다. 2024년 핀란드의 노동 분쟁으로 인해 연간 4만-5만 톤의 생산이 중단되었으며, 구매자들은 연간 수요의 60%-70%를 고정 가격 계약으로 사전 예약할 수밖에 없게 되었습니다. 이는 부가가치가 높은 분야의 탈크 시장 점유율을 재편하는 구조적인 움직임으로 나타나고 있습니다.
일본 및 한국의 전자기기 제조업체들의 비축은 공급 부족 상황을 여실히 보여주고 있습니다. 수입업자들은 파업 전인 22일분에서 2025년에는 안전 재고를 45일분으로 두 배로 늘려 공급망을 보호하는 한편, 운전자금을 고정화하게 되었습니다. 인도의 가공업체들은 조달처 다각화와 환율 리스크 헤지를 위해 서호주주의 클로라이트 광맥에 주목하고 있습니다. 탄산염 광석은 순도보다 가격이 중시되는 건설용 충진재 및 고무 산업에서 여전히 필수적인 존재입니다.
지역별 분석
2025년 아시아태평양의 시장 점유율 53.22% 및 연평균 성장률(CAGR) 5.18%라는 전망은 여러 요인이 복합적으로 작용하여 뒷받침되고 있습니다. 인도의 세라믹 부문은 2025 회계연도에 51,000-53,000 크롤(61억-64억 달러)의 매출을 기록했습니다. 이는 6%-7%의 국내 타일 수요와 2,540만 m²의 발표된 생산능력에 힘입은 결과입니다. 베트남에서는 중국 제품에 대한 반덤핑 조치가 내려짐에 따라 2024년 타일 수출이 22% 급증했습니다. 이로 인해 뒤틀림을 방지하기 위해 더 미세한 활석(탈크)이 필요한 롤러 킬른 개보수 투자가 촉진되었습니다. 중국의 GB30981.1-2025 VOC 규제로 인해 배합 제조업체들은 수성 도료 내 활석 함량을 30%-40%로 높일 수밖에 없게 되었습니다. 2024년 태국의 생산량이 17.27% 증가한 것은 태국이 아세안(ASEAN)의 가공 거점으로서 역할을 수행하고 있음을 반영합니다. OECD의 장기 예측 모델에 따르면, 2060년까지 이 지역의 플라스틱 수요는 3배인 1억 5,000만 톤에 달할 것으로 예상되며, 탈크는 경량화 추세에 깊이 통합될 것입니다. 일본과 한국은 전자기기 및 의약품용 클로라이트 등급의 수입을 전문으로 하고 있지만, 이러한 분야에서는 ppm 미만의 중금속 함유량 제한이 설정되어 있어 진입 장벽이 높습니다.
북미에서는 소송과 생산자의 철수로 인해 성장이 제약을 받고 있습니다. 미네랄스 테크놀러지스(Minerals Technologies)가 2024년 4월 바레츠 미네랄스(Barrets Minerals)를 3,200만 달러에 매각한 것은 배상 책임 위험과 영업 수익 사이에서 겪는 딜레마를 여실히 드러내고 있습니다. 존슨앤드존슨(Johnson & Johnson)사의 미해결된 100억 달러 규모의 제안은 보험 비용을 부풀려 보험료를 40%-60% 인상시키고 있습니다. 몬태나주와 버몬트주에 위치한 미국 광산들은 여전히 자동차 및 도료 고객들에게 공급을 이어가고 있지만, 세간의 엄격한 감시 속에서 신규 허가 취득은 더디게 진행되고 있습니다. 캐나다와 멕시코에서는 주로 자동차용 플라스틱 분야에서 현지 조달을 우선시하는 USMCA(미국·멕시코·캐나다 협정) 규정이 적용되고 있습니다. FDA(미국 식품의약국)의 2024년 현미경 검사 의무화로 인해 로트별 검사 비용이 상승하면서, 틈새 시장 화장품 브랜드들은 전분 유래 대체 소재로의 전환을 강요받고 있습니다.
유럽에서는 고급 용지의 바이오 기반 소재로의 대체와 2025년 3월 이메리스 탈크 이탈리아(Imeris Talc Italia)사의 파산으로 인해 공급이 위축되고 있습니다. 북유럽의 클로라이트 사업은 의약품 및 식품 접촉 시장에 공급하고 있으나, 파업으로 인해 현물 시장의 공급이 부족해지면서 구매자들은 연간 수요의 60%-70%를 테이크 오어 페이(Take-or-Pay) 계약으로 확보할 수밖에 없는 상황입니다. 독일, 프랑스, 영국, 이탈리아에서의 소비는 자동차, 건축용 도료, 세라믹 분야에 이르고 있습니다. 2028년부터 ‘머티리얼 패스포트’ 제출을 의무화하는 EU의 새로운 에코디자인 규제는 원산지가 명확하고 수명주기 동안 탄소 배출량이 적은 충전재를 우선시하는 것으로, 에너지 집약적인 탈크 생산자들에게 비용 면에서 압박을 가하고 있습니다. 남미, 중동 및 아프리카의 합계 점유율은 비교적 작으며, 브라질의 자동차용 플라스틱과 사우디아라비아의 신흥 세라믹 산업 클러스터가 주도하고 있지만, 환율 변동과 물류 병목 현상으로 인해 수요 증가가 제한되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.02According to Mordor Intelligence, the talc market size is expected to grow from 8.44 Million tons in 2025 to 8.80 Million tons in 2026 and is forecast to reach 10.87 Million tons by 2031 at 4.31% CAGR over 2026-2031.
This report is Segmented by Deposit Type (Talc Carbonate and Talc Chlorite), End-User Industry (Plastics and Rubber, Paints and Coatings, Ceramics, Pulp and Paper, Personal Care and Cosmetics, Food and Beverage, and Other Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Talc Market Trends and Insights
Robust PP and TPO Adoption in Automotive Lightweighting
Automakers embed 15%-25% talc in PP and TPO compounds to achieve stiffness-to-weight ratios that meet fuel-economy and EV-range mandates without retooling injection lines. Imerys opened a EUR 43 million facility in Wuhu in 2025 to supply 30,000 tons of ultra-fine grades targeted at battery housings and interior panels. The OECD projects plastics use in Southeast and East Asia to rise from 60 million tons in 2019 to 150 million tons by 2060, with automotive and electronics driving the steepest slopes. Malaysia's circular-economy initiative recovered 12,000 tons of PP and ABS from end-of-life vehicles in 2024, a figure expected to triple by 2030. Talc's nucleating effect shortens molding cycles by 8%-12%, raising throughput for tier-one suppliers operating at 85%-90% capacity utilization.
Growing Shift to Water-Based Architectural Paints in Asia
China's GB30981.1-2025 caps VOCs at 80 g/L for interior coatings, forcing formulators to adopt aqueous binders that require higher talc loadings. India's Bureau of Indian Standards is drafting similar limits for notification in late 2026. Water-based systems typically contain 12%-18% talc, up from 8%-12% in solvent-borne paints, because the mineral's lamellar platelets compensate for lower hiding power. Thailand's Office of Industrial Economics recorded a 17.27% rise in domestic talc output in 2024, with exports up 14.73% on demand from Vietnam, Indonesia, and the Philippines. Compared with titanium dioxide, talc is priced at USD 150-250 per ton, enabling paint makers to hold shelf prices steady despite inflation in other additives.
Persistent Asbestos-Related Litigation Costs
Johnson & Johnson offered USD 10 billion in May 2024 to settle 62,000 ovarian-cancer claims tied to cosmetic talc. The proposal remains in limbo after successive Chapter 11 filings by LTL Management were dismissed, prolonging uncertainty for upstream miners. Minerals Technologies booked a USD 215 million provision in Q1 2025 to fund a trust for 684 open cases, after divesting Barretts Minerals for USD 32 million. Imerys obtained 90% creditor approval in January 2025 for its North American restructuring, ring-fencing legacy liabilities but constraining balance-sheet flexibility. Insurance premiums on talc producers' primary layers rose 40%-60% in 2025, while aggregate limits tightened to USD 50-100 million, compelling mid-tier players to self-insure or exit cosmetic grades.
Other drivers and restraints analyzed in the detailed report include:
- Strong Demand for Talc-Filled Polymer Masterbatch in Packaging
- Expansion of Ceramics Production in South and Southeast Asia
- Bio-Based Fillers Replacing Talc in Premium Papers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Talc carbonate accounted for 61.90% of 2025 tonnage, thanks to abundant metamorphic belts in China, India, and Brazil that yield cost-effective ore for plastics, paints, and ceramics. Talc Chlorite, holding the balance, will expand at a 4.76% CAGR as automotive and electronics customers impose sub-50 ppm iron limits impossible for many carbonate ores. Chlorite talc delivers less than 0.05% iron versus 0.15%-0.30% for carbonate, eliminating color shift in white automotive trim and cutting bleaching costs in cosmetic formulations. Chlorite grades fetch a USD 50-100 premium but reduce kiln CO2 evolution by 8%-12%, aiding EU carbon-pricing compliance. Finnish labor strikes in 2024 sidelined 40,000-50,000 t/y, forcing buyers to pre-book 60%-70% of annual needs under fixed-price contracts, a structural move that reshapes the talc market share at the value-added end of the spectrum.
Stockpiling by Japanese and South Korean electronics firms illustrates tightness: importers doubled safety inventories to 45 days in 2025, up from 22 days pre-strike, insulating supply chains yet locking in working capital. Indian processors eye Western Australia's chlorite veins to diversify sourcing and hedge currency exposure. Carbonate ore remains indispensable for construction fillers and rubber, where price outweighs purity.
Complete Report Scope:
- By Deposit Type
- Talc Carbonate
- Talc Chlorite
- By End-user Industry
- Plastics and Rubber
- Paints and Coatings
- Ceramics
- Pulp and Paper
- Personal Care and Cosmetics
- Food and Beverage
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 53.22% slice in 2025 and a 5.18% forecast CAGR rely on synchronized forces. India's ceramic sector generated INR 51,000-53,000 crore (USD 6.1-6.4 billion) in FY 2025, underpinned by 6%-7% domestic tile demand and 25.4 million m2 of announced capacity. Vietnam's tile exports jumped 22% in 2024 after anti-dumping rulings against Chinese products, spurring investment in roller-kiln retrofits that demand finer talc to avert warping. China's GB30981.1-2025 VOC cap forces formulators to raise talc in water-based paints by 30%-40%. Thailand's 17.27% rise in 2024 output reflects its role as an ASEAN processing hub. OECD long-range models see regional plastics demand tripling to 150 million tons by 2060, locking talc into the lightweighting narrative. Japan and South Korea specialize in chlorite-grade imports for electronics and pharma, where sub-ppm heavy-metal limits create high barriers to entry.
North America's growth is restricted owing to litigation and producer exits. Minerals Technologies' April 2024 sale of Barretts Minerals for USD 32 million underscores the squeeze between liability risk and operating returns. Johnson & Johnson's unresolved USD 10 billion proposal magnifies insurance costs, adding 40%-60% to premiums. U.S. mines in Montana and Vermont still supply automotive and paints customers, but new permits evolve slowly amid public scrutiny. In Canada and Mexico, primarily in auto plastics, covered by USMCA rules favouring local content. The FDA's 2024 microscopy mandate raises batch-testing costs, nudging niche cosmetics brands toward starch alternatives.
Europe is curbed by bio-based substitution in premium paper and the March 2025 bankruptcy of Imerys Talc Italy. Nordic chlorite operations feed pharmaceutical and food-contact markets, strike, tighten spot supply, and drive buyers to commit 60%-70% of annual needs under take-or-pay terms. Germany, France, the UK, and Italy's consumption spans automotive, architectural paints, and ceramics. The EU's forthcoming Ecodesign Regulation, which will require material passports from 2028, favors fillers with transparent provenance and lower life-cycle carbon, putting cost pressure on energy-intensive talc producers. South America and the Middle-East and Africa together take a smaller share, led by Brazil's auto plastics and Saudi Arabia's nascent ceramics clusters, though currency swings and logistics bottlenecks limit velocity.
- AKJ MinChem
- ANAND TALC
- Chanda Minerals
- CIMBAR PERFORMANCE MINERALS
- euroMinerals GmbH
- Golcha Group
- Hayashi-Kasei
- Imerys
- IMI Fabi SpA
- LITHOS Industrial Minerals GmbH
- Magris Performance Materials
- Minerals Technologies Inc.
- Nippon Talc Co., Ltd.
- Sibelco
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Robust PP and TPO Adoption in Automotive Lightweighting
- 4.2.2 Growing Shift to Water-Based Architectural Paints in Asia
- 4.2.3 Strong Demand for Talc-Filled Polymer Masterbatch in Packaging
- 4.2.4 Expansion of Ceramics Production in South and Southeast Asia
- 4.2.5 AI-Enabled Ore-Sorting Boosting Ore Recovery and Unit Economics
- 4.3 Market Restraints
- 4.3.1 Persistent Asbestos-Related Litigation Costs
- 4.3.2 Bio-Based Fillers Replacing Talc in Premium Papers
- 4.3.3 High-Purity Ore Shortages in Europe After Finnish Labor Strike
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Deposit Type
- 5.1.1 Talc Carbonate
- 5.1.2 Talc Chlorite
- 5.2 By End-user Industry
- 5.2.1 Plastics and Rubber
- 5.2.2 Paints and Coatings
- 5.2.3 Ceramics
- 5.2.4 Pulp and Paper
- 5.2.5 Personal Care and Cosmetics
- 5.2.6 Food and Beverage
- 5.2.7 Other End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 AKJ MinChem
- 6.4.2 ANAND TALC
- 6.4.3 Chanda Minerals
- 6.4.4 CIMBAR PERFORMANCE MINERALS
- 6.4.5 euroMinerals GmbH
- 6.4.6 Golcha Group
- 6.4.7 Hayashi-Kasei
- 6.4.8 Imerys
- 6.4.9 IMI Fabi SpA
- 6.4.10 LITHOS Industrial Minerals GmbH
- 6.4.11 Magris Performance Materials
- 6.4.12 Minerals Technologies Inc.
- 6.4.13 Nippon Talc Co., Ltd.
- 6.4.14 Sibelco
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment