|
시장보고서
상품코드
2120444
디지털 포렌식 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Digital Forensics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 디지털 포렌식 시장 규모는 2025년 75억 1,000만 달러로 평가되었습니다. 2026년 84억 6,000만 달러에서 2031년까지 153억 7,000만 달러로 확대되고 2026-2031년까지 연평균 복합 성장률(CAGR)은 12.68%를 나타낼 전망입니다.

본 보고서는 구성 요소별(하드웨어, 소프트웨어, 서비스), 유형별(네트워크 포렌식, 클라우드 포렌식, 데이터베이스 포렌식, 기타), 도구별(포렌식 데이터 분석, 검토·보고서 작성, 기타),조직 규모별(대기업, 중소기업), 최종 사용자 산업별(헬스케어, 교육, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 디지털 포렌식 시장 동향 및 인사이트
클라우드 네이티브 SaaS의 급속한 확산에 따른 클라우드 포렌식 수요 창출
CISA(미국 사이버보안 및 인프라 보안국) 등의 기관은 현재 모든 연방 정부의 클라우드 워크로드에 대해 지속적인 포렌식 데이터 수집을 의무화하고 있으며, 전 세계 기업들이 유사한 방침을 채택하도록 장려하고 있습니다. 휘발성 컨테이너나 서버리스 함수의 경우 로그가 몇 분 이내에 소멸되기 때문에 조직들은 메모리 스냅샷을 확보하고, Kubernetes 포드의 상태를 재구성하며, 아티팩트를 불변 상태로 저장하는 플랫폼을 채택하고 있습니다. Okta 및 Snowflake에서 발생한 SaaS 침해 사건은 계약상의 미비점을 부각시켰으며, 증거 보관을 보장하는 새로운 서비스 수준 계약(SLA)의 수립을 촉진했습니다. 클라우드 전자 정보 공개에 관한 ISO 27050 부록은 2026년에 감사의 초점이 될 것이며, 이를 준수하지 않는 기업은 강화된 제재에 직면하게 됩니다. 그 결과, 디지털 포렌식 시장은 AWS, Azure, Google Cloud와 원활하게 통합되는 턴키 방식의 클라우드 에이전트로 전환되고 있습니다.
딥페이크를 이용한 사기의 급증으로 인한 고도화된 멀티미디어 분석 수요 증가
연방거래위원회(FTC)에 따르면, 2025년 딥페이크 음성 및 동영상을 이용한 부정 송금으로 인해 금융 기관은 123억 달러의 손실을 입었습니다. 은행과 보험사는 현재 부자연스러운 음소 전환이나 호흡의 끊김을 감지하여 합성 미디어를 식별하기 위한 AI 기반 포렌식 필터를 도입하고 있습니다. 유럽연합(EU)의 ‘AI법’은 딥페이크 생성 소프트웨어를 고위험으로 분류하고 추적 가능성을 의무화하고 있으며, 이로 인해 실시간 감지 API에 대한 수요가 증가하고 있습니다. 포렌식 연구소는 4K 프레임을 고속으로 처리하는 GPU 클러스터에 대한 투자를 추진하고 있으며, 미국 국립표준기술연구소(NIST)는 공급업체의 주장을 검증하기 위한 정확도 벤치마킹을 시작했습니다. 이러한 노력으로 인해 디지털 포렌식 시장에서 멀티미디어 포렌식의 중요성이 높아지고 있습니다.
iOS 및 Android의 기본 암호화로 인한 데이터 확보의 복잡성 및 비용 증가
애플의 iOS 18과 구글의 안드로이드 15에서는 보안 엔클레이브 키가 자동으로 활성화되어 논리적 데이터 추출이 작동하지 않게 되었으며, 수사 기관은 법정에서 증거 오염의 위험을 수반하는 익스플로잇 기반 기법을 채택할 수밖에 없게 되었습니다. 고성능 모바일 데이터 추출 스테이션의 비용은 2025년에 8만 5,000달러로 거의 두 배로 증가하여 지자체 예산에 부담을 주고 있습니다. 캘리포니아주와 뉴욕주 법원에서는 제로데이 익스플로잇이 공개되지 않은 상태일 경우, 증거 채택 여부에 대한 의문이 제기되고 있습니다. 디지털 포렌식 시장에서는 양자 내성 브루트포스 처리 장치에 대한 투자나, 복잡한 데이터 추출 작업을 관리형 서비스 제공업체에 위탁함으로써 이러한 과제에 대응하고 있습니다.
부문별 분석
서비스 부문은 2031년까지 연평균 성장률(CAGR) 13.27%로 확대되고 있으며, 2025년 디지털 포렌식 시장에서 소프트웨어 부문이 차지한 47.23%의 점유율과의 격차를 꾸준히 좁혀가고 있습니다. 관리형 리테이너 계약에서는 데이터 수집 도구, 침해 분석, 전문가 증인의 증언이 단일 구독으로 통합되어 있어, 기업은 자본 지출을 운영 예산으로 전환할 수 있게 되었습니다. 2025년 매출의 대부분은 전문 서비스(컨설팅, 교육, 현장 지원)가 차지했으나, 현재는 클라우드를 통해 제공되는 사고 대응 계약이 금액 기준으로 가장 빠른 성장을 보이고 있습니다. 하드웨어는 여전히 가장 작은 점유율을 차지하고 있지만, 전용으로 설계된 이미징 워크스테이션, 라이트 블로커, 견고한 현장 키트는 법 집행 기관의 워크플로우를 지속적으로 뒷받침하고 있습니다.
소프트웨어의 성장은 기능 통합으로 인해 제한되고 있으며, 각 벤더가 오픈 API를 공개함에 따라 감지 플랫폼이 온디맨드로 포렌식 기능을 호출할 수 있게 되었습니다. 기업들은 핵심 분석 엔진에 대해서만 라이선스를 취득하고, 일상적인 증거 처리를 24시간 이내에 보고서를 제출한다고 약속하는 서비스 제공업체에 아웃소싱하는 경향이 강해지고 있습니다. 이러한 동향으로 인해 하드웨어 교체 주기는 완만해지는 반면, 서비스의 이익률은 향상되고 있으며, 이는 디지털 포렌식 시장이 영구 라이선스에서 성과 기반 모델로 전환되고 있음을 뒷받침합니다. 소프트웨어, 하드웨어, 전문 지식을 하나의 청구서로 통합하는 제공업체는 다음 지출 주기를 주도할 위치에 있습니다.
클라우드 포렌식은 2031년까지 연평균 성장률(CAGR) 13.84%를 나타낼 것으로 예측되며, 이는 2025년 시점에서 여전히 디지털 포렌식 시장의 32.44%를 차지했던 컴퓨터 포렌식을 능가하는 속도입니다. 현재 조직들은 수명이 짧은 컨테이너 로그, 서버리스 트레이스, SaaS 메타데이터를 불변의 오브젝트 스토어에 저장하는 에이전트를 도입하여, 데이터 변동으로 인해 발생하는 증거 손실을 줄이고 있습니다. 컴퓨터 포렌식은 Windows 및 Linux 엔드포인트와 관련된 침해 조사에서 여전히 기초적인 역할을 수행하고 있지만, 엔드포인트 감지 도구가 기존 디스크 이미징 작업의 상당 부분을 담당하게 되면서 그 성장세는 둔화되고 있습니다.
모바일 기기 포렌식은 공공 부문 예산의 약 3분의 1을 차지하고 있지만, 암호화의 보급에 따라 각 기관은 보안이 강화된 클라우드에서 호스팅되는 ‘EaaS(Extraction-as-a-Service)’형 서비스로 전환하고 있습니다. 네트워크 포렌식은 패킷 캡처를 통해 공급망 공격 시 발생하는 횡방향 이동을 식별할 수 있게 되면서 회복세를 보이고 있는 반면, IoT 및 데이터베이스 포렌식은 중요 인프라나 재무 장부에서 트랜잭션 수준의 검증이 요구되는 모든 상황에서 두각을 나타내고 있습니다. 전반적으로 클라우드 워크로드의 확대와 엔드포인트의 다양화로 인해 디지털 포렌식 시장은 앞으로도 두 자릿수 성장을 유지할 것으로 예측됩니다.
지역별 분석
북미는 2025년 디지털 포렌식 시장 점유율의 41.37%를 차지했습니다. 이는 연구소가 데이터 추출 및 클라우드 포렌식 도구를 업그레이드할 수 있도록 지원한 12억 달러 규모의 연방 사이버 수사 자금에 힘입은 결과입니다. 미국 기업들은 캘리포니아주, 뉴욕주, 텍사스주의 엄격한 정보 유출 통지 규정에 직면해 있어, 보안 스택에 증거 수집 커넥터를 일상적으로 통합하고 있습니다. 캐나다에서는 개정된 개인정보보호법에 따라 공개 기한이 엄격해짐에 따라 은행과 통신 사업자들이 포렌식 대응 체계를 강화해야 하는 상황에 처해 있습니다. 멕시코 수요는 소규모이지만, 국경을 넘는 범죄 수사에서 모바일 단말기의 이미징 기능이 필요하기 때문에 증가 추세를 보이고 있습니다. 이 지역 전체에서 구매자들은 인력 부족에 대비하기 위해 영구 라이선스보다 관리형 리테이너 계약을 명확히 선호하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 13.66%로 가장 높은 성장이 예상되며, 이 지역의 디지털 포렌식 시장 규모는 다른 지역을 앞지르는 속도로 확대될 전망입니다. 인도에서는 수천 명의 새로운 감정사가 인증되었으며, 일본에서는 고도화된 모바일 데이터 추출에 특화된 도도부현립 연구소의 설비 갱신에 85억 엔의 예산이 편성되었습니다. 중국의 데이터 거주지 규제로 인해 다국적 기업들은 국내에 포렌식 인프라를 구축할 수밖에 없게 되었으며, 그 결과 전 세계의 사고 대응 워크플로가 사실상 분절되고 있습니다. 호주의 중요 인프라에 관한 규제는 네트워크 및 클라우드 포렌식에 대한 새로운 지출을 촉진하고 있는 반면, 한국의 BFSI(은행 및 금융 및 보험) 부문에서는 결제 사기에 대응하기 위해 증거 데이터의 보존 기간을 연장하고 있습니다. 이러한 각국의 노력이 합쳐져 지역 전체의 장기적인 성장을 뒷받침하고 있습니다.
유럽은 GDPR(EU 개인정보보호규정) 및 ‘네트워크 정보 보안 지침’이 포렌식에 기반한 공식적인 침해 평가를 의무화하고 있어 계속해서 견실한 기여를 하고 있지만, 이 지역의 성장 속도는 아시아태평양에 비해 완만합니다. 중동 및 아프리카에서는 아랍에미리트와 사우디아라비아에 지출이 집중되고 있으며, 이들 국가에서는 스마트 시티 및 정부 클라우드 프로그램에서 증거 보관 관리(체인 오브 커스터디)가 요구되고 있습니다. 남미에서는 브라질과 아르헨티나가 중심을 이루고 있으며, 조직적인 사이버 범죄와 부패에 대처하기 위해 경찰 과학수사 실험실의 설비 현대화가 진행되고 있습니다. 일부 신흥 시장에서는 예산이 제한적이지만, 랜섬웨어 증가와 규제 압력의 고조로 인해 디지털 포렌식 시장의 잠재 규모는 계속해서 확대되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the digital forensics market size is projected to expand from USD 7.51 billion in 2025 and USD 8.46 billion in 2026 to USD 15.37 billion by 2031, registering a 12.68% CAGR between 2026 and 2031.
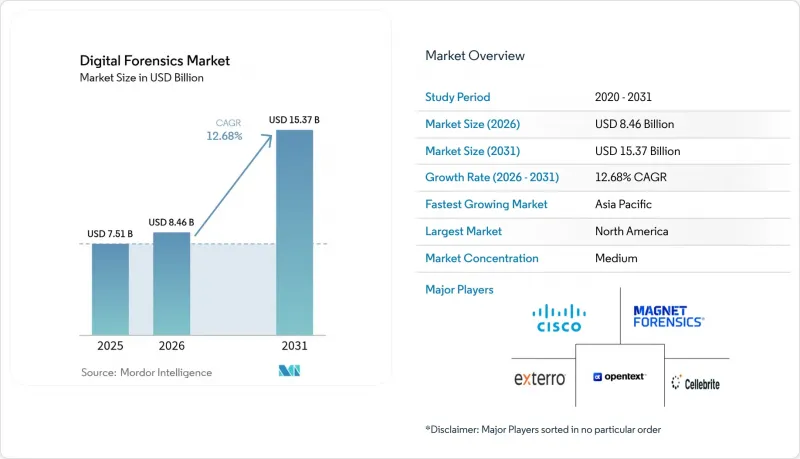
This report is Segmented by Component (Hardware, Software, Services), Type (Network Forensics, Cloud Forensics, Database Forensics, and More), Tool (Forensic Data Analysis, Review and Reporting, and More), Organization Size (Large Enterprises, and Small and Medium Enterprises), End-User Vertical (Healthcare, Education, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Forensics Market Trends and Insights
Rapid Proliferation of Cloud-Native SaaS Creating Demand for Cloud Forensics
Agencies such as CISA now require continuous forensic data collection for every federal cloud workload, pushing enterprises worldwide to adopt a similar posture. Volatile containers and serverless functions expire logs within minutes, so organizations have adopted platforms that snapshot memory, reconstruct Kubernetes pod states, and store artifacts immutably. SaaS breaches at Okta and Snowflake underscored contractual gaps, prompting new service-level agreements that guarantee evidence preservation. ISO 27050 annexes on cloud e-discovery became an audit focal point in 2026, and non-compliant firms face escalating penalties. The digital forensics market is consequently pivoting toward turnkey cloud agents that integrate seamlessly with AWS, Azure, and Google Cloud.
Surge in Deepfake-Enabled Fraud Driving Advanced Multimedia Analysis Needs
Deepfake audio and video cost financial institutions USD 12.3 billion in fraudulent transfers during 2025, according to the Federal Trade Commission. Banks and insurers now embed AI-powered forensic filters that look for unnatural phoneme transitions and skipped breaths to flag synthetic media. The European Union's AI Act classifies deepfake generation software as high-risk and mandates traceability, spurring demand for real-time detection APIs. Forensic labs are investing in GPU clusters that process 4K frames quickly, and the U.S. National Institute of Standards and Technology launched accuracy benchmarks to validate vendor claims. These initiatives elevate the importance of multimedia forensics in the digital forensics market.
Encryption-by-Default on iOS/Android Elevating Acquisition Complexity and Cost
Apple iOS 18 and Google Android 15 automatically activate secure-enclave keys, making logical extractions ineffective and forcing agencies toward exploit-based techniques that risk evidence contamination in court. The cost of a high-end mobile-extraction station nearly doubled to USD 85,000 in 2025, straining municipal budgets. Courts in California and New York questioned the admissibility of evidence when zero-day exploits remain undisclosed. The digital forensics market compensates by investing in quantum-resistant brute-force rigs and outsourcing complex extractions to managed service providers.
Other drivers and restraints analyzed in the detailed report include:
- Extended Detection and Response Adoption Necessitating Integrated DFIR Platforms
- Legislated Mobile Device Extraction Mandates in U.S. and EU Law-Enforcement
- Shortage of Court-Certified Examiners Outside Tier-1 Cities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services are advancing at a 13.27% CAGR through 2031, steadily closing the gap with software's 47.23% share of the digital forensics market in 2025. Managed retainers bundle acquisition tools, breach analysis, and expert witness testimony under a single subscription, allowing enterprises to shift capital expenses to operating budgets. Professional services consulting, training, and on-site support formed the bulk of 2025 revenue, but cloud-delivered incident-response contracts now account for the fastest dollar growth. Hardware remained the smallest slice, yet purpose-built imaging workstations, write blockers, and rugged field kits continue to anchor law-enforcement workflows.
Software growth is tempered by feature convergence, as vendors expose open APIs that let detection platforms call forensic functions on demand. Enterprises increasingly license only core parsing engines, then outsource routine evidence processing to service providers that promise 24-hour report delivery. This dynamic sustains hardware refreshes at a slower cadence while lifting service margins, confirming that the digital forensics market is pivoting toward outcomes rather than perpetual licenses. Providers that merge software, hardware, and expertise into a single invoice are positioned to lead the next spending cycle.
Cloud forensics is projected to grow at a 13.84% CAGR through 2031, outpacing computer forensics, which still accounted for 32.44% of the digital forensics market in 2025. Organizations now deploy agents that preserve short-lived container logs, serverless traces, and SaaS metadata in immutable object stores, reducing evidence gaps caused by volatility. Computer forensics remains foundational in breach investigations involving Windows and Linux endpoints, yet its growth slows as endpoint detection tools ingest many classic disk-imaging tasks.
Mobile-device forensics accounts for roughly one-third of public-sector budgets, but the rise of encryption is steering agencies toward extraction-as-a-service offerings hosted in secure clouds. Network forensics rebounds as packet capture pinpoints lateral movement in supply-chain attacks, while IoT and database forensics emerge wherever critical infrastructure and financial ledgers demand transaction-level validation. Collectively, expanding cloud workloads and diversified endpoints will ensure continued double-digit growth in the digital forensics market.
Complete Report Scope:
- By Component
- Hardware
- Forensic Systems, Devices and Write Blockers
- Imaging and Duplication Devices
- Other Hardwares
- Software
- Forensic Data Analysis and Visualization
- Review and Reporting
- Forensic Decryption
- Other Softwares
- Services
- Professional Services
- Incident Response and Breach Analysis
- Consulting and Training
- Managed Forensic Services
- Professional Services
- Hardware
- By Type
- Computer Forensics
- Mobile Device Forensics
- Network Forensics
- Cloud Forensics
- Database Forensics
- IoT and Embedded Device Forensics
- By Tool
- Data Acquisition and Preservation
- Data Recovery and Reconstruction
- Forensic Data Analysis
- Review and Reporting
- Forensic Decryption and Password Cracking
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By End-user Vertical
- Government and Law Enforcement Agencies
- BFSI
- IT and Telecom
- Healthcare
- Retail and E-commerce
- Energy and Utilities
- Manufacturing
- Transportation and Logistics
- Defense and Aerospace
- Education
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America commanded 41.37% of the 2025 digital forensics market share, supported by USD 1.2 billion in federal cyber-investigation funding that helped laboratories upgrade extraction and cloud-forensic tools. Enterprises in the United States face strict breach notification rules in California, New York, and Texas, so they routinely embed evidence-capture connectors into their security stacks. Canada tightened disclosure timelines under its revised privacy law, prompting banks and telecom operators to enhance forensic readiness. Mexico's demand is smaller but rising as cross-border crime investigations require mobile-device imaging capabilities. Across the region, buyers show a clear preference for managed retainers over perpetual licenses as a hedge against talent shortages.
Asia-Pacific is projected to post the fastest 13.66% CAGR through 2031, lifting the regional digital forensics market size at a pace unmatched elsewhere. India is certifying thousands of new examiners, and Japan has budgeted JPY 8.5 billion for upgrades to prefectural labs focused on advanced mobile extractions. China's data-residency rules force multinationals to build in-country forensic infrastructure, effectively segmenting global incident-response workflows. Australia's critical infrastructure mandates are driving fresh spending on network and cloud forensics, while South Korea's BFSI sector is expanding artifact retention to counter payment fraud. These national initiatives collectively underpin long-run growth across the region.
Europe remains a robust contributor as GDPR and the Network and Information Security Directive require formal breach assessments that rely on forensics, yet the region's expansion is steadier than that of Asia-Pacific. The Middle East and Africa concentrate spending in the United Arab Emirates and Saudi Arabia, where smart-city and government cloud programs demand chain-of-custody controls. South America centers on Brazil and Argentina, which are upgrading police laboratories to address organized cybercrime and corruption. Although budgets in several emerging markets are limited, rising ransomware and regulatory pressure continue to broaden the addressable digital forensics market.
- OpenText Corporation
- Cellebrite DI Ltd.
- Exterro Inc.
- Magnet Forensics Inc.
- Cisco Systems Inc.
- Mandiant Inc.
- LogRhythm Inc.
- KLDiscovery Inc.
- Paraben Corporation
- MSAB AB
- Oxygen Forensics Inc.
- Kroll LLC
- Hexagon AB
- ADF Solutions Inc.
- BAE Systems plc
- Broadcom Inc.
- Micro Systemation AB
- Digital Detective Group
- Nuix Pty Ltd
- Passware Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Proliferation of Cloud-Native SaaS Creating Demand for Cloud Forensics
- 4.2.2 Surge in Deepfake-Enabled Fraud Driving Advanced Multimedia Analysis Needs
- 4.2.3 Extended Detection and Response (XDR) Adoption Necessitating Integrated DFIR Platforms
- 4.2.4 Legislated Mobile Device Extraction Mandates in U.S. and EU Law-Enforcement
- 4.2.5 Blockchain-Based Evidence Chain-of-Custody Pilots Boosting Forensic Software Upgrades
- 4.2.6 Federal Cybersecurity Investments and Regulatory Compliance Requirements Expanding Forensic Deployments
- 4.3 Market Restraints
- 4.3.1 Encryption-by-Default on iOS/Android Elevating Acquisition Complexity and Cost
- 4.3.2 Shortage of Court-Certified Examiners Outside Tier-1 Cities
- 4.3.3 Fragmented Tool Inter-Operability Increasing Total Cost of Ownership for SMEs
- 4.3.4 Data-Residency Rules Limiting Cross-Border Evidence Transfers (e.g., China CSL)
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Outlook
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Buyers
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.1.1 Forensic Systems, Devices and Write Blockers
- 5.1.1.2 Imaging and Duplication Devices
- 5.1.1.3 Other Hardwares
- 5.1.2 Software
- 5.1.2.1 Forensic Data Analysis and Visualization
- 5.1.2.2 Review and Reporting
- 5.1.2.3 Forensic Decryption
- 5.1.2.4 Other Softwares
- 5.1.3 Services
- 5.1.3.1 Professional Services
- 5.1.3.1.1 Incident Response and Breach Analysis
- 5.1.3.1.2 Consulting and Training
- 5.1.3.2 Managed Forensic Services
- 5.1.3.1 Professional Services
- 5.1.1 Hardware
- 5.2 By Type
- 5.2.1 Computer Forensics
- 5.2.2 Mobile Device Forensics
- 5.2.3 Network Forensics
- 5.2.4 Cloud Forensics
- 5.2.5 Database Forensics
- 5.2.6 IoT and Embedded Device Forensics
- 5.3 By Tool
- 5.3.1 Data Acquisition and Preservation
- 5.3.2 Data Recovery and Reconstruction
- 5.3.3 Forensic Data Analysis
- 5.3.4 Review and Reporting
- 5.3.5 Forensic Decryption and Password Cracking
- 5.4 By Organization Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Medium Enterprises
- 5.5 By End-user Vertical
- 5.5.1 Government and Law Enforcement Agencies
- 5.5.2 BFSI
- 5.5.3 IT and Telecom
- 5.5.4 Healthcare
- 5.5.5 Retail and E-commerce
- 5.5.6 Energy and Utilities
- 5.5.7 Manufacturing
- 5.5.8 Transportation and Logistics
- 5.5.9 Defense and Aerospace
- 5.5.10 Education
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 OpenText Corporation
- 6.4.2 Cellebrite DI Ltd.
- 6.4.3 Exterro Inc.
- 6.4.4 Magnet Forensics Inc.
- 6.4.5 Cisco Systems Inc.
- 6.4.6 Mandiant Inc.
- 6.4.7 LogRhythm Inc.
- 6.4.8 KLDiscovery Inc.
- 6.4.9 Paraben Corporation
- 6.4.10 MSAB AB
- 6.4.11 Oxygen Forensics Inc.
- 6.4.12 Kroll LLC
- 6.4.13 Hexagon AB
- 6.4.14 ADF Solutions Inc.
- 6.4.15 BAE Systems plc
- 6.4.16 Broadcom Inc.
- 6.4.17 Micro Systemation AB
- 6.4.18 Digital Detective Group
- 6.4.19 Nuix Pty Ltd
- 6.4.20 Passware Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment