|
시장보고서
상품코드
2120448
전임상 이미징 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Preclinical Imaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
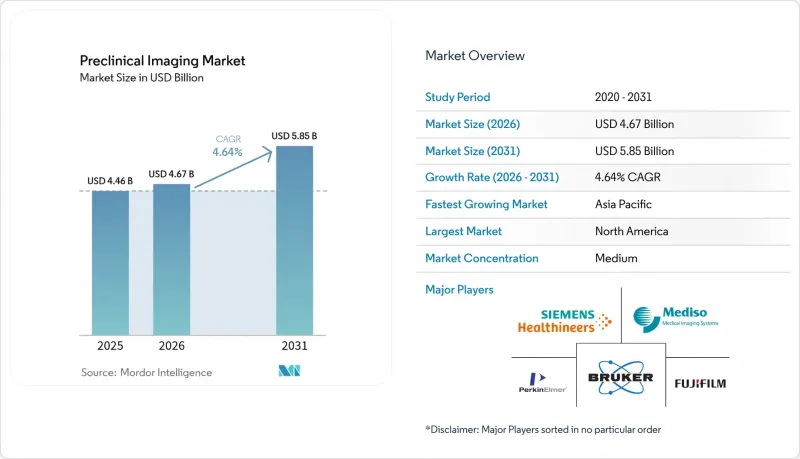
에 의하면, 2026년 전임상 이미징 시장 규모는 46억 7,000만 달러로 추정되고 2025년 44억 6,000만 달러에서 확대해, 2031년에는 58억 5,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 4.64%로 성장할 것으로 전망됩니다.
본 보고서는 모달리티별(광학 영상 시스템, 핵의학 영상 시스템, 마이크로 MRI, 마이크로 CT 등),용도별(종양학, 신경학, 심혈관 질환 등), 최종 사용자별(제약·바이오기술 기업 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다. 시장 전망은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 전임상 이미징 시장 동향 및 인사이트
AI를 활용한 멀티모달 이미징 : 조사 능력의 재정의
인공지능을 활용한 자동 영상 획득 및 모달리티 간 분석을 통해 처리 시간이 최대 70% 단축되어, 연구자들은 데이터 정리에 시간을 할애하지 않고 결과 해석에 집중할 수 있게 되었습니다. 이 기술을 통해 동일한 동물에서 해부학적, 기능적, 분자 수준의 측정값을 동기화하여 획득할 수 있게 되어, 통계적 검출력을 높이는 동시에 코호트 규모를 축소할 수 있습니다. 형광 현미경과 3T-7T MRI를 결합함으로써 심장 및 신경 조직의 이온 변동에 대한 이해가 더욱 깊어졌으며, 전임상 이미징 시장이 질환의 진행을 비침습적이고 시간 경과에 따라 관찰하는 방향으로 나아가고 있음을 보여줍니다. AI 파이프라인을 통합한 상용 플랫폼은 경험이 부족한 연구소에서도 도입이 용이하여 사용자 기반을 확대하는 동시에, 전임상 이미징 시장에 새로운 수요를 창출하고 있습니다.
세포 및 유전자 치료 파이프라인의 확대가 생체 내 추적 수요를 견인
2024년까지 미국에서 승인된 16건의 세포 및 유전자 치료는 신약 개발 및 독성학 워크플로우 전반에 파급 효과를 가져왔습니다. 스탠포드 대학교의 세포 및 유전자 치료 센터와 같은 학술 거점에서는 리포터 유전자 영상 기술을 통해 이식된 세포를 수개월에 걸쳐 추적하여, 규제 당국이 요구하는 안전성 및 지속성 데이터를 제공할 수 있음이 입증되었습니다. 이러한 수요는 고감도로 전신을 추적할 수 있는 다중 모드 스캐너에 대한 지속적인 주문으로 이어져, 전임상 이미징 시장의 장기적인 성장을 뒷받침하고 있습니다.
신흥 시장에서 멀티모달 시스템 숙련된 운영자 부족
하이브리드 스캐너 운영에는 MRI, PET, 광학, 데이터 사이언스 등 다양한 분야에 걸친 교차 교육이 필요하지만, 이 모든 기술을 겸비한 인력은 드뭅니다. 자격을 갖춘 직원이 더 높은 급여를 제공하는 거점으로 이직하면 실험실 가동이 중단되어 설비 용량 확대에 제약이 따릅니다. 벤더 측은 클라우드 기반 원격 제어 대시보드를 도입하여 전문가의 지원을 시설 간에 공유할 수 있도록 대응하고 있지만, 인력 부족은 여전히 지속되고 있어 아시아, 라틴아메리카, 아프리카 일부 지역에서 신규 도입 속도가 둔화되고 있습니다.
부문 분석
광학 시스템은 합리적인 가격, 직관적인 조작, 그리고 일상적인 종양학 및 감염병 연구에 적합한 실시간 판독 기능이라는 장점 덕분에 2025년 전임상 이미징 시장에서 34.78%의 점유율을 유지했습니다. 이 부문의 도입 대수는 고처리량 스크리닝에서 여전히 매우 중요하지만, 그 CAGR은 부상하고 있는 대체 기술에 뒤처지고 있습니다. PET/SPECT/CT 및 PET/MR과 같은 하이브리드 시스템은 연구자들이 반복적인 마취 없이 다중 매개변수 정보를 얻으려는 추세에 힘입어 2031년까지 연평균 9.43%의 성장률을 보일 것으로 예측됩니다. MILABS VECTor와 같은 첨단 장비는 4µm까지의 해상도로 기능적 영상과 해부학적 영상을 통합하여 실험 설계의 자유도를 확대되고 있습니다. Revvity사의 IVIS SpectrumCT 2는 광학 데이터에 CT 감쇠 보정을 추가하여 정량화 정확도를 높이고, 하이브리드 플랫폼용 비임상 영상 시장 규모를 확대함으로써 이러한 융합 추세를 구현하고 있습니다.
부품 비용의 하락과 워크플로우 자동화의 진전에 따라 하이브리드 기술의 도입은 더욱 가속화되고 있습니다. 아시아와 유럽의 연구 컨소시엄에서는 공유 장비 조달 시 멀티모달 기능을 필수 조건으로 하는 사례가 늘어나고 있어, 단일 모달리티에 대한 의존에서 벗어나는 전략적 전환이 두드러지고 있습니다. 이러한 경향은 서비스 계약 및 소프트웨어 업그레이드에 대한 지속적인 수요를 창출하여, 전임상 이미징 시장 전체에서 공급업체의 수익원을 더욱 공고히 하고 있습니다.
지역별 분석
2025년, 북미는 전임상 이미징 시장의 47.62%를 차지했습니다. SBIR 등 연방 정부 보조금과 지속적인 벤처 캐피탈 유입으로 인해 산학 협력의 긴밀한 네트워크가 뒷받침되고 있습니다. MD 앤더슨 암 센터와 같은 시설에서는 7테슬라 MRI 및 PET/SPECT/CT 3모달리티 시스템을 도입하고 있으며, 이는 이 지역이 기술적 우위 유지에 주력하고 있음을 뒷받침합니다. 미국의 연구소에서는 광음향 단층 촬영과 MRI를 통합한 워크플로우 등 획기적인 기술이 개발되어, 혈관 영상과 대사 영상을 동시에 수행할 수 있게 되었으며, 종양의 특성 평가가 더욱 정교해지고 있습니다.
아시아는 2031년까지 연평균 성장률(CAGR)이 9.16%로 가장 빠르게 성장하는 지역입니다. 중국과 일본은 첨단 시설에 대한 투자를 주도하고 있으며, 각국의 자금 지원 제도를 통해 조달 승인 절차가 효율화되고 있습니다. 홍콩이공대학교의 7T MRI 및 최첨단 광음향 초음파 장비 도입은 해당 지역의 역량이 급속히 강화되고 있음을 반영합니다. 또한 각국 정부는 국내 CRO를 육성하고, 영상 진단용 부품에 부과되는 고액의 수입 관세를 상쇄하는 보조금을 지급함으로써 전임상 이미징 진단 시장에 대한 지역적 참여를 확대되고 있습니다.
유럽은 민관 협력의 원활한 조정을 통해 견실한 시장 점유율을 유지하고 있습니다. 엄격한 동물 복지 규제로 인해 동물 사용 수를 줄이는 비침습적 검사법에 대한 수요가 증가하고 있으며, 윤리적 우선순위와 과학적 우선순위가 조화를 이루고 있습니다. 디스커버리 파크 벤처스의 Vox Imaging Technology에 대한 출자와 같은 투자 수단은 MRI 소형화에 새로운 자본을 투입하고, 자국 내 혁신 파이프라인을 확보하고 있습니다. 각 벤더사는 전임상 및 임상 분야에 걸친 통합 소프트웨어 플랫폼을 중시하고 있습니다. 유나이티드 이미징(United Imaging)의 트랜스레이셔널 아키텍처는 설치류 연구에서 인간 연구로 데이터를 원활하게 이관할 수 있게 하여, 임상적으로 예측 가능한 영상 워크플로우에 대한 유럽의 집중을 강화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, preclinical imaging market size in 2026 is estimated at USD 4.67 billion, growing from 2025 value of USD 4.46 billion with 2031 projections showing USD 5.85 billion, growing at 4.64% CAGR over 2026-2031.
This report is Segmented by Modality (Optical Imaging Systems, Nuclear Imaging Systems, Micro-MRI, Micro-CT, and More), Application (Oncology, Neurology, Cardiovascular Disorders, and More), End User (Pharmaceutical & Biotechnology Companies, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Preclinical Imaging Market Trends and Insights
AI-Augmented Multimodal Imaging: Redefining Research Capabilities
Automated image acquisition and cross-modality analysis powered by artificial intelligence now cut processing times by as much as 70%, freeing scientists to focus on interpretation rather than data wrangling. The technology enables synchronized anatomical, functional, and molecular readouts within the same animal, boosting statistical power while reducing cohort sizes. Fluorescence microscopy paired with 3T-7T MRI furthers insight into ionic shifts in cardiac and neurologic tissue, demonstrating the preclinical imaging market's push toward non-invasive, longitudinal observation of disease progression. Commercial platforms embedding AI pipelines also simplify onboarding for less-experienced laboratories, widening the user base and injecting fresh demand into the preclinical imaging market.
Expansion of Cell & Gene Therapy Pipelines Driving Demand for Longitudinal In-vivo Tracking
Sixteen U.S. approvals for cell and gene therapies through 2024 created ripple effects that permeate discovery and toxicology workflows. Academic hubs such as Stanford's Center for Cell and Gene Therapy illustrate how reporter gene imaging allows transplanted cells to be followed for months, providing safety and persistence data that regulators require. These needs translate to sustained orders for multimodal scanners capable of sensitive, whole-body tracking, reinforcing long-term growth in the preclinical imaging market.
Scarcity of Skilled Operators for Multimodal Systems in Emerging Markets
Hybrid scanners demand cross-training in MRI, PET, optics, and data science, skills rarely found in a single individual. Laboratory downtime arises when qualified staff migrate to higher-paying hubs, constraining capacity expansion. Vendors respond with cloud-based remote operation dashboards that stretch expert support across facilities, yet talent shortages persist, tempering the pace of new installations in parts of Asia, Latin America, and Africa.
Other drivers and restraints analyzed in the detailed report include:
- Government-Sponsored National Preclinical Imaging Infrastructure Programs
- Increase in Preclinical Research Funding from Private and Public Organizations
- Strict Regulations in Preclinical Research
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Optical systems retained 34.78% of the preclinical imaging market in 2025, benefiting from affordability, intuitive operation, and real-time readouts that suit routine oncology and infectious-disease studies. The segment's installed base remains pivotal for high-throughput screening, yet its CAGR lags emerging alternatives. Hybrid systems, notably PET/SPECT/CT and PET/MR, are forecast to grow 9.43% annually through 2031 as investigators seek multi-parametric insights without multiple anesthetic events. Advanced devices such as the MILABS VECTor integrate functional and anatomical imaging down to 4 µm, expanding experimental design latitude. Revvity's IVIS SpectrumCT 2 exemplifies the convergence trend by adding CT attenuation correction to optical data, thereby enhancing quantification accuracy and boosting the preclinical imaging market size for hybrid platforms.
Falling component costs and improved workflow automation further accelerate hybrid adoption. Research consortia in Asia and Europe increasingly mandate multimodal capabilities when procuring shared equipment, highlighting the strategic shift from single-modality reliance. These preferences feed recurring demand for service contracts and software upgrades, deepening vendor revenue streams across the preclinical imaging market.
Complete Report Scope:
- By Modality
- Optical Imaging Systems
- Nuclear Imaging Systems (PET/SPECT)
- Micro-MRI
- Micro-CT
- Micro-Ultrasound
- Photoacoustic Imaging Systems
- Hybrid & Multi-modal Platforms
- Other Modalities
- By Application
- Oncology
- Neurology
- Cardiovascular Disorders
- Immunology & Infectious Diseases
- Metabolic Disorders
- Others
- By End User
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutions
- Contract Research Organizations
- Government & Non-profit Labs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 47.62% of the preclinical imaging market in 2025. Federal grants like SBIR and sustained venture capital inflows finance a dense network of academic-industry collaborations. Centers such as MD Anderson Cancer Center house 7 T MRI and tri-modality PET/SPECT/CT systems, underlining the region's commitment to maintaining technological edge. Breakthroughs such as integrated photoacoustic tomography-MRI workflows have emerged from U.S. labs, enabling concurrent vascular and metabolic imaging that refines tumor characterization.
Asia is the fastest-growing region with a 9.16% CAGR through 2031. China and Japan spearhead investment in sophisticated facilities, while national funding schemes streamline procurement approvals. Hong Kong Polytechnic University's installation of 7 T MRI and advanced photoacoustic ultrasound reflects the region's rapid capability build-up. Governments also nurture domestic CROs, offering subsidies that offset high import tariffs on imaging components, expanding regional participation in the preclinical imaging market.
Europe maintains robust share through well-coordinated public-private partnerships. Stringent animal welfare regulations accelerate demand for non-invasive modalities that reduce animal numbers, aligning ethical and scientific priorities. Investment vehicles like Discovery Park Ventures' stake in Vox Imaging Technology channel fresh capital into MRI miniaturization, ensuring a pipeline of home-grown innovation. Vendors emphasize harmonized software platforms across preclinical and clinical lines: United Imaging's translational architecture lets data flow seamlessly from rodent to human studies, reinforcing Europe's focus on clinically predictive imaging workflows.
- Bruker
- PerkinElmer
- FUJIFILM
- Siemens Healthineers
- Mediso
- MR Solutions
- Aspect Imaging
- Trifoil Imaging
- Miltenyi Biotec B.V. & Co. KG
- United Imaging Healthcare
- Rigaku
- MILabs
- VisualSonics Inc. (FUJIFILM Sonosite)
- Photon etc.
- AXT Pty Ltd
- IVIM Technology
- Advanced Molecular Vision
- Cubresa Inc.
- Scanco Medical AG
- Thermo Fisher Scientific
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of AI-Augmented Multimodal Imaging Platforms for Small-Animal Studies
- 4.2.2 Expansion of Cell & Gene Therapy Pipelines Driving Demand for Longitudinal In-vivo Tracking
- 4.2.3 Government-Sponsored National Preclinical Imaging Infrastructure Programs
- 4.2.4 Increase in Preclinical Research Funding, by Both Private and Public Organizations
- 4.2.5 Miniaturization of High-Field MRI Magnets Enabling Point-of-Need Rodent Imaging
- 4.2.6 Integration of Molecular Imaging with CRISPR-Based Animal Models
- 4.3 Market Restraints
- 4.3.1 Scarcity of Skilled Operators for Multi-modal Systems in Emerging Markets
- 4.3.2 Strict Regulations in Preclinical Research
- 4.3.3 High Installation and Operational Costs associated with Preclinical Imaging Modalities
- 4.3.4 Limited Standardization Across Imaging Modalities and Protocols
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Modality
- 5.1.1 Optical Imaging Systems
- 5.1.2 Nuclear Imaging Systems (PET/SPECT)
- 5.1.3 Micro-MRI
- 5.1.4 Micro-CT
- 5.1.5 Micro-Ultrasound
- 5.1.6 Photoacoustic Imaging Systems
- 5.1.7 Hybrid & Multi-modal Platforms
- 5.1.8 Other Modalities
- 5.2 By Application
- 5.2.1 Oncology
- 5.2.2 Neurology
- 5.2.3 Cardiovascular Disorders
- 5.2.4 Immunology & Infectious Diseases
- 5.2.5 Metabolic Disorders
- 5.2.6 Others
- 5.3 By End User
- 5.3.1 Pharmaceutical & Biotechnology Companies
- 5.3.2 Academic & Research Institutions
- 5.3.3 Contract Research Organizations
- 5.3.4 Government & Non-profit Labs
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Bruker Corporation
- 6.3.2 PerkinElmer Inc.
- 6.3.3 FUJIFILM Holdings Corporation
- 6.3.4 Siemens Healthineers AG
- 6.3.5 Mediso Ltd
- 6.3.6 MR Solutions Ltd
- 6.3.7 Aspect Imaging Ltd
- 6.3.8 Trifoil Imaging
- 6.3.9 Miltenyi Biotec B.V. & Co. KG
- 6.3.10 United Imaging Healthcare Co. Ltd
- 6.3.11 Rigaku Corporation
- 6.3.12 MILabs B.V.
- 6.3.13 VisualSonics Inc. (FUJIFILM Sonosite)
- 6.3.14 Photon etc.
- 6.3.15 AXT Pty Ltd
- 6.3.16 IVIM Technology Corp.
- 6.3.17 Advanced Molecular Vision, Inc.
- 6.3.18 Cubresa Inc.
- 6.3.19 Scanco Medical AG
- 6.3.20 Thermo Fisher Scientific Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment