

|
시장보고서
상품코드
2120468
애플리케이션 성능 관리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Application Performance Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
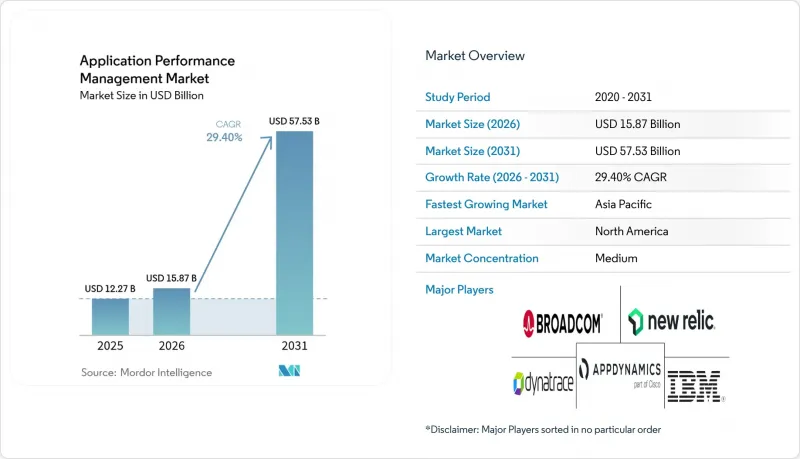
에 의하면, 애플리케이션 성능 관리 시장 규모는 2025년에 122억 7,000만 달러로 평가되었습니다. 2026년 158억 7,000만 달러에서 2031년까지 575억 3,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 29.40%를 나타낼 전망입니다.
본 보고서는 도입 형태(On-Premise, 클라우드), 기업 규모(중소기업, 대기업), 구성 요소(솔루션, 서비스),용도 유형(웹 기반, 모바일, 마이크로서비스), 최종 사용자 산업(은행, 금융서비스 및 보험(BFSI), IT 및 통신, 소매, 의료, 제조, 기타), 지역(북미, 남미, 유럽, APAC, MEA)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 애플리케이션 성능 관리 시장 동향 및 인사이트
클라우드 네이티브 및 마이크로서비스 아키텍처로의 급속한 전환
모놀리식 스택을 분산형 마이크로서비스로 대체하고 있는 기업들은 현재 트랜잭션당 약 35개의 상호 연결된 구성 요소를 오케스트레이션하고 있으며, 이러한 복잡성의 급증으로 인해 레거시 에이전트로는 효율적으로 추적할 수 없게 되었습니다. Kubernetes는 기본 제어 플레인이 되었으며, New Relic의 eBPF 기반 솔루션은 코드 변경 없이 모든 파드와 서비스를 자동으로 감지합니다. 개발 주기 단축(최대 40% 단축)으로 인해 빌드 단계와 실행 단계의 연속성이 점점 더 중요해지고 있습니다. 그 결과, 분산 추적, 서비스 메시 가시성, 그리고 일시적인 워크로드에 적응하는 토폴로지 기반 분석에 대한 수요가 급증하고 있습니다. 각 벤더는 메트릭, 로그, 추적을 거의 실시간으로 상호 연관시켜 차별화를 꾀하며, 릴리스 속도가 신뢰성 목표를 초과하지 않도록 하고 있습니다.
DevOps 툴체인 전반에 걸친 통합적인 가시성에 대한 수요 증가
대기업에서는 5개 이상의 모니터링 도구를 일상적으로 병행하여 사용하고 있어, 엔지니어들은 대시보드 간을 빈번하게 전환해야만 하며, 이로 인해 인시던트 해결에 시간이 오래 걸리고 있습니다. OpenTelemetry의 부상은 통합을 촉진하여, 팀이 데이터 수집과 분석 엔진을 분리할 수 있게 해줍니다. 다양한 도구를 단일 플랫폼으로 통합한 기업에서는 인시던트 해결 시간이 30% 단축되고 운영 오버헤드가 25% 감소한 것으로 보고되었습니다. 현재 중앙 거버넌스 기관이 도메인 전반에 걸친 텔레메트리 요구 사항에 비추어 구매를 검토하고 있으며, 통합된 가시성은 예산상 필수 요건으로 자리 잡고 있습니다. 따라서 애플리케이션 성능 관리(APM) 시장에서는 의사결정 루프를 가속화하는 메트릭, 로그, 트레이스, 이벤트를 통합한 워크플로를 제공하는 벤더가 높이 평가받고 있습니다.
FinOps를 통한 툴스택 최적화에 따른 예산 압박
FinOps 감사를 통해 모니터링 비용이 클라우드 청구액에서 불균형한 비율을 차지하고 있음이 밝혀졌습니다. 한 기업의 경우, 단일 플랫폼만으로도 연간 6,500만 달러 이상의 비용이 발생했던 사례도 있습니다. 카디널리티에 연동된 종량제 과금은 예측 불가능한 비용을 초래하여 도구 합리화를 촉진하고 있습니다. 비용 거버넌스 분야의 스타트업 기업들은 가시성 관련 청구서를 상세하게 분석하여, 미사용 라이선스나 계절적 피크 시기에 급증하는 ‘하이워터마크’ 과금을 지적하고 있습니다. 중소기업은 가장 먼저 그 영향을 받으며, 풀스택 모니터링 도입을 미루는 경우가 많아지고 있습니다. 이에 대응하여 각 벤더사는 현재 적응형 데이터 보존, 온디맨드 라이선싱 계층, 그리고 비용 가시성과 비즈니스 가치를 일치시키는 이상치 기반 샘플링 등의 대책으로 대응하고 있습니다.
부문 분석
2025년, 클라우드 서비스는 애플리케이션 성능 관리(APM) 시장 점유율의 62.15%를 차지했고 연평균 성장률(CAGR) 32.55%로 확대될 것으로 예측되며, 이는 SaaS가 기본 이용 모델임을 뒷받침합니다. 기업은 인프라 관리를 벤더에 위탁함으로써 즉시 전 세계로 확장할 수 있으며, 지속적인 기능 제공이 가능해집니다. 데이터 보호 규제로 인해 텔레메트리 데이터의 일부를 On-Premise에 보관해야 하는 경우, 하이브리드 모델이 부상하고 있습니다. 이 경우, 엣지 에이전트가 편집된 인사이트를 클라우드 기반 AI 레이어로 전송하여 상관 분석을 수행합니다. 사용량 기반 과금제로 인해 비용은 부하에 따라 조정되지만, 초과 사용을 피하기 위해서는 주의가 필요합니다. 각 벤더는 트래픽에 따른 스로틀링 및 적응형 저장 기능을 추가하고 있으며, 이를 통해 규정 준수 요구 사항이 서로 다른 각 산업 분야에서 애플리케이션 성능 관리 시장은 지속적으로 확대되고 있습니다.
이와 병행하여 멀티 클라우드 설계도에 가시성이 통합되면서, AWS, Azure, Google Cloud 및 프라이빗 스택을 아우르는 단일 대시보드가 보급되고 있습니다. 사용자들은 기존의 SNMP 트랩 대신 클라우드 네이티브 API를 채택하여 도입을 가속화하고 있습니다. 엣지 컴퓨팅은 모니터링을 디바이스에 더 가깝게 수행함으로써, IoT나 저지연이 요구되는 소매 업계에서 1초 미만의 이상 감지를 실현합니다. 이러한 진전에 힘입어 클라우드 도입은 플랫폼 혁신의 지표로서 입지를 공고히 하고 있으며, AI, 자동 복구, 예측 기능 모듈의 전개 속도를 결정짓고 있습니다.
2025년 애플리케이션 성능 관리(APM) 시장 규모에서 대기업은 57.05%의 점유율을 차지했으며, 이는 Tier 1 솔루션에 의존하는 확립된 세계 인프라 환경을 반영합니다. 이러한 기업들은 풀스택 상관 분석을 우선시하며, 워크플로우를 효율화하기 위해 5개의 도구를 2개로 통합하는 경우가 많습니다. 반면, 중소기업(SME)은 SaaS 도입으로 가치 실현까지 걸리는 시간이 대폭 단축되고, 종량제 요금제로 인해 진입 장벽이 낮아짐에 따라 33.55%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 자동화된 계측 기능으로 인해 희소한 관측성 인력에 대한 의존도가 낮아지는 한편, Honeycomb의 Grit 인수로 강화된 자연어 처리 기능을 활용한 AI 번역 쿼리를 통해 비전문가 사용자도 인사이트를 도출할 수 있게 되었습니다.
중소기업은 워크로드 규모에 맞추어 확장 가능한 모듈식 번들을 선호하며, 코드를 재측정하지 않고도 분석 백엔드를 전환할 수 있는 OpenTelemetry를 지지하고 있습니다. 1달러 단위의 비용을 엄격하게 관리하는 소규모 팀에서는 FinOps 운영 체제가 더욱 철저하게 정착되어 있으며, 이용 현황을 한눈에 파악할 수 있는 대시보드의 활용이 촉진되고 있습니다. 이러한 민주화로 인해 애플리케이션 성능 관리(APM) 시장의 잠재 고객 기반이 확대되면서, 벤더들은 엔터프라이즈급 보안을 유지하면서도 도입을 간소화한 ‘라이트’ 요금제 제공을 요구받고 있습니다.
지역별 분석
북미는 2025년, 성숙한 클라우드 생태계와 New Relic, Datadog, Dynatrace가 주도하는 밀집된 벤더 환경에 힘입어 애플리케이션 성능 관리(APM) 시장의 37.75%를 계속 차지했습니다. 미국에서는 규정 준수 규제가 엄격해지는 가운데, 은행과 병원이 IT 지출의 더 큰 비중을 가시성에 할당하고 있는 반면, 캐나다의 통신 및 에너지 업계에서는 고가용성 목표를 달성하기 위해 APM이 도입되고 있습니다. 멕시코에서는 전자상거래의 확대에 따라 실제 사용자 모니터링에 대한 관심이 높아지고 있습니다.
아시아태평양은 중국, 인도, 동남아시아 전역에 걸친 하이퍼스케일러의 데이터센터 확장에 힘입어 연평균 성장률(CAGR) 31.25%로 성장하고 있습니다. 정부의 디지털화 추진 정책과 5G 네트워크 구축으로 용도 응답성에 대한 기대가 높아지고 있습니다. 일본 및 한국의 제조업체들은 예측 유지보수를 통한 가동 중단 방지에 중점을 두고, 인더스트리 4.0 생산 라인에 APM을 통합하고 있습니다. 인도의 IT 서비스 제공업체들은 고객과의 SLA를 보장하기 위해 아웃소싱 계약에 가시성을 포함시키고 있습니다.
유럽에서는 GDPR(EU 개인정보보호규정) 및 데이터를 국경 내에 유지하도록 하는 새로운 주권 규제의 영향으로 APM이 꾸준히 보급되고 있습니다. 영국과 독일이 지출을 주도하고 있으며, 락인(lock-in)을 최소화하기 위해 OpenTelemetry 준수를 중시하고 있습니다. 프랑스에서는 원격의료 도입이 진행되고 있으며, 이탈리아에서는 전자정부 포털의 현대화가 추진되고 있고, 북유럽 국가들에서는 그린 에너지 마이크로그리드를 위한 엣지 모니터링에 투자가 이루어지고 있습니다. 중동 및 아프리카는 여전히 초기 단계이지만, 핀테크와 전자상거래가 부상함에 따라 그 성장이 가속화되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the application performance management market size was valued at USD 12.27 billion in 2025 and estimated to grow from USD 15.87 billion in 2026 to reach USD 57.53 billion by 2031, at a CAGR of 29.40% during the forecast period (2026-2031).
This report is Segmented by Deployment (On-Premise, Cloud), Enterprise Size (SMEs, Large Enterprises), Component (Solutions, Services), Application Type (Web-Based, Mobile, Microservices), End-User Industry (BFSI, IT and Telecom, Retail, Healthcare, Manufacturing, and More), and Geography (North America, South America, Europe, APAC, MEA). The Market Forecasts are Provided in Terms of Value (USD).
Global Application Performance Management Market Trends and Insights
Rapid Shift to Cloud-Native and Micro-Services Architectures
Enterprises replacing monolithic stacks with distributed microservices now orchestrate roughly 35 interconnected components per transaction, a complexity surge that legacy agents cannot trace efficiently. Kubernetes has become the default control plane, and New Relic's eBPF-powered offering auto-discovers every pod and service without code changes. Faster development cycles, up to 40% shorter, intensify the need for continuity between build and run phases. Consequently, demand spikes for distributed tracing, service-mesh visibility, and topology-aware analytics that adjust to ephemeral workloads. Vendors differentiate by correlating metrics, logs, and traces in near real time to keep release velocity from outpacing reliability targets.
Rising Demand for Unified Observability Across DevOps Tool-Chains
Large enterprises routinely juggle five or more monitoring tools, forcing engineers to swivel between dashboards, prolonging incident resolution. OpenTelemetry's rise catalyzes consolidation, letting teams decouple data collection from analysis engines. Firms that collapse tool sprawl into single-pane platforms report 30% quicker resolution times and 25% lower operations overhead. Central governance bodies now vet purchases against cross-domain telemetry requirements, cementing unified observability as a budgetary mandate. The Application Performance Management market, therefore, rewards vendors offering integrated metric, log, trace, and event workflows that accelerate decision loops.
Budget Squeeze from FinOps Optimization of Tool Stacks
FinOps audits expose monitoring spend as a disproportionate slice of cloud bills; one enterprise topped USD 65 million yearly on a single platform. Consumption pricing tied to cardinality drives unpredictable charges, spurring tooling rationalization. Cost-governance startups parse observability invoices, flagging unused licenses and high-water-mark billing that spikes during seasonal peaks. SMEs feel the pinch first, often postponing full-stack monitoring rollouts. Vendors now counter with adaptive data retention, on-demand licensing tiers, and anomaly-based sampling that aligns cost visibility with business value.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Mobile and IoT Transactions Requiring Real-Time Insight
- Growth in Digital-First Customer Experience Programs
- Complex, Expensive Licensing Models Limiting Wider Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud offerings commanded 62.15% of the Application Performance Management market share in 2025 and are projected to advance at a 32.55% CAGR, confirming SaaS as the default consumption model. Enterprises offload infrastructure management to vendors, unlocking instant global reach and continuous feature delivery. Hybrid models rise where data protection rules keep subsets of telemetry on-site; here, edge agents forward redacted insights to cloud-based AI layers for correlation. Consumption billing aligns cost to load, though it requires vigilance to avoid overruns. Vendors add traffic-aware throttling and adaptive retention so that the Application Performance Management market continues to broaden across verticals with contrasting compliance footprints.
A parallel trend sees observability embedded into multi-cloud blueprints, with single dashboards spanning AWS, Azure, Google Cloud, and private stacks. Users adopt cloud-native APIs over traditional SNMP traps, speeding onboarding. Edge computing pushes monitoring closer to devices, granting sub-second anomaly detection for IoT and low-latency retail. These developments cement cloud deployment as the bellwether of platform innovation, setting the cadence for AI, auto-remediation, and predictive capacity modules.
Large enterprises held a 57.05% share of the Application Performance Management market size in 2025, reflecting entrenched global estates that rely on Tier-1 solutions. These firms prioritize full-stack correlation, often consolidating from five tools to two to streamline workflows. SMEs, however, clock the fastest 33.55% CAGR as SaaS onboarding slashes time-to-value and pay-as-you-go billing lowers entry barriers. Automated instrumentation reduces dependence on scarce observability talent, while AI-translated queries help non-experts extract insights with natural language capabilities boosted by Honeycomb's Grit acquisition.
SMEs gravitate toward modular bundles that grow with workload scale, favoring OpenTelemetry so they can switch analytics back ends without reinstrumenting code. FinOps hygiene is stronger among small teams that track every dollar, encouraging high-visibility usage dashboards. This democratization widens the Application Performance Management market addressable base, compelling vendors to ship "lite" tiers that preserve enterprise-grade security yet simplify onboarding.
Complete Report Scope:
- By Deployment
- On-premise
- Cloud
- By Enterprise Size
- Small and Medium-Sized Enterprises (SMEs)
- Large Enterprises
- By Component
- Solutions
- Application Performance Monitoring and Analytics
- End-User Experience Monitoring
- Infrastructure and Network Monitoring
- Services
- Professional Services
- Managed Services
- Solutions
- By Application Type
- Web-based Applications
- Mobile Applications
- Micro-services and Containerised Workloads
- By End-user Industry
- Banking, Financial Services and Insurance (BFSI)
- Information Technology and Telecommunications
- Retail and E-commerce
- Healthcare and Life Sciences
- Manufacturing
- Government and Public Sector
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 37.75% of the Application Performance Management market in 2025, supported by mature cloud ecosystems and a dense vendor landscape led by New Relic, Datadog, and Dynatrace. U.S. banks and hospitals allocate bigger slices of IT spend to observability as compliance regimes tighten, while Canada's telecommunications and energy verticals adopt APM to secure high-availability targets. Mexico sees expanding digital commerce that heightens interest in real-user monitoring.
Asia-Pacific is growing at a 31.25% CAGR, fueled by hyperscaler data-center rollouts across China, India, and Southeast Asia. Government digital agendas and 5G network launches raise expectations for app responsiveness. Japanese and South Korean manufacturers integrate APM into Industry 4.0 lines, focusing on predictive downtime avoidance. Indian IT service providers embed observability into outsourcing contracts to guarantee client SLAs.
Europe shows steady uptake, shaped by GDPR and emerging sovereignty rules that keep data within borders. The U.K. and Germany lead spending, emphasizing OpenTelemetry compliance to minimize lock-in. France grows telehealth adoption, Italy modernizes e-government portals, and the Nordics invest in edge monitoring for green-energy microgrids. Middle East and Africa remain nascent but accelerate as fintech and e-commerce gain prominence.
- Cisco Systems, Inc. (AppDynamics)
- New Relic, Inc.
- Dynatrace, Inc.
- International Business Machines Corporation
- Broadcom Inc. (Including CA Technologies)
- Microsoft Corporation
- Micro Focus International plc
- Datadog, Inc.
- Splunk Inc. (incl. SignalFx)
- Akamai Technologies, Inc.
- SolarWinds Corporation
- Riverbed Technology, Inc.
- Oracle Corporation
- BMC Software, Inc.
- Elastic N.V.
- Instana LLC (IBM)
- ManageEngine - Zoho Corporation Pvt. Ltd.
- LogicMonitor, Inc.
- AppOptics (SolarWinds)
- Correlsense Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid shift to cloud-native and micro-services architectures
- 4.2.2 Rising demand for unified observability across DevOps tool-chains
- 4.2.3 Proliferation of mobile and IoT transactions requiring real-time insight
- 4.2.4 Growth in digital-first customer experience programs
- 4.2.5 AI-driven auto-remediation reducing MTTR (under-reported)
- 4.2.6 Edge-to-core performance data monetisation by telecom operators (under-reported)
- 4.3 Market Restraints
- 4.3.1 Budget squeeze from FinOps optimisation of tool stacks
- 4.3.2 Complex, expensive licensing models limiting wider adoption
- 4.3.3 Skill-set gap in distributed-tracing and open telemetry (under-reported)
- 4.3.4 Data-sovereignty hurdles for cross-border APM data lakes (under-reported)
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macro-Economic Shifts
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment
- 5.1.1 On-premise
- 5.1.2 Cloud
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium-Sized Enterprises (SMEs)
- 5.2.2 Large Enterprises
- 5.3 By Component
- 5.3.1 Solutions
- 5.3.1.1 Application Performance Monitoring and Analytics
- 5.3.1.2 End-User Experience Monitoring
- 5.3.1.3 Infrastructure and Network Monitoring
- 5.3.2 Services
- 5.3.2.1 Professional Services
- 5.3.2.2 Managed Services
- 5.3.1 Solutions
- 5.4 By Application Type
- 5.4.1 Web-based Applications
- 5.4.2 Mobile Applications
- 5.4.3 Micro-services and Containerised Workloads
- 5.5 By End-user Industry
- 5.5.1 Banking, Financial Services and Insurance (BFSI)
- 5.5.2 Information Technology and Telecommunications
- 5.5.3 Retail and E-commerce
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Manufacturing
- 5.5.6 Government and Public Sector
- 5.5.7 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Australia and New Zealand
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems, Inc. (AppDynamics)
- 6.4.2 New Relic, Inc.
- 6.4.3 Dynatrace, Inc.
- 6.4.4 International Business Machines Corporation
- 6.4.5 Broadcom Inc. (Including CA Technologies)
- 6.4.6 Microsoft Corporation
- 6.4.7 Micro Focus International plc
- 6.4.8 Datadog, Inc.
- 6.4.9 Splunk Inc. (incl. SignalFx)
- 6.4.10 Akamai Technologies, Inc.
- 6.4.11 SolarWinds Corporation
- 6.4.12 Riverbed Technology, Inc.
- 6.4.13 Oracle Corporation
- 6.4.14 BMC Software, Inc.
- 6.4.15 Elastic N.V.
- 6.4.16 Instana LLC (IBM)
- 6.4.17 ManageEngine - Zoho Corporation Pvt. Ltd.
- 6.4.18 LogicMonitor, Inc.
- 6.4.19 AppOptics (SolarWinds)
- 6.4.20 Correlsense Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


