|
시장보고서
상품코드
2120503
중동 및 아프리카의 접착제 및 실란트 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2025-2031년)Middle East And Africa Adhesives And Sealants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2025 - 2031) |
||||||
 Mordor Intelligence
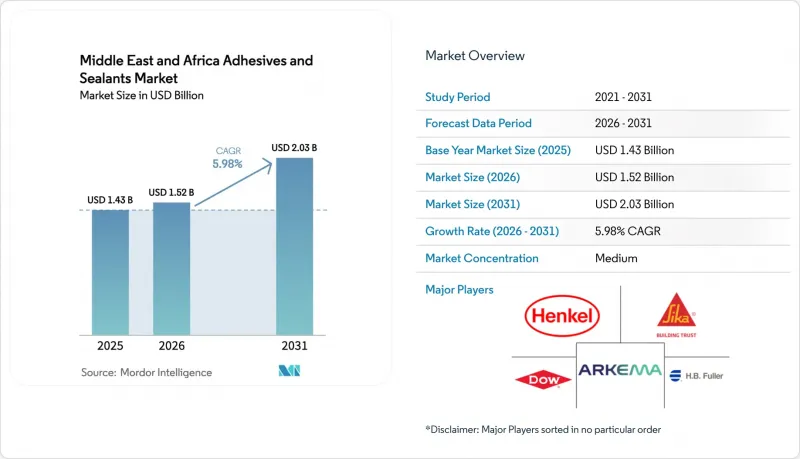
에 의하면, 중동 및 아프리카의 접착제 및 실란트 시장 규모는 2025년에 14억 3,000만 달러로 평가되었습니다. 2026년 15억 2,000만 달러에서 2031년까지 20억 3,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.98%를 나타낼 전망입니다.
본 보고서는 접착제 수지별(아크릴, 에폭시, 폴리우레탄, 기타), 접착제 기술별(핫멜트, 반응성, 용제형, UV 경화형, 수성),실란트 수지별(폴리우레탄, 실리콘, 기타), 최종 사용자 산업별(자동차, 건축 및 건설, 기타), 지역별(사우디아라비아, 아랍에미리트, 남아프리카공화국, 이집트, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
중동 및 아프리카의 접착제 및 실란트 시장 동향 및 인사이트
‘사우디 비전 2030’에 따른 건설 메가 프로젝트
공공투자기금(PIF)은 2025년, NEOM, 키디야, 킹 살만 파크 등의 핵심 프로젝트에 400억 달러를 투자했습니다. NEOM의 직선형 도시에 사용되는 커튼월 유리에는 하루 12시간의 직사광선을 견디기 위해 자외선 차단 첨가제가 배합된 구조용 실리콘 실란트가 사용되고 있습니다. 레드씨 디벨롭먼트의 마린 빌라에서는 3,000시간의 염수 분무 사이클을 견딜 수 있는 폴리우레탄계 접착제가 채택되었으며, 이에 따라 Sika와 Wacker Chemie에서 새로운 1액형 시스템이 개발되었습니다. 프리캐스트 패널에 사용되는 속경화형 에폭시 수지는 공사 기간을 40% 단축하고, 대규모 건설 현장에서의 노동력을 절감합니다. 이와 유사한 사양이 카타르의 루사일 시티 2단계 프로젝트에도 적용되었으며, 이곳에서는 반응성 폴리우레탄 실란트가 고층 타워의 복합재 클래딩을 접착하고 있습니다.
GCC 및 이집트 전역에서 전자상거래 주도형 포장 붐
아랍에미리트의 전자상거래 총 상품 가치는 2025년에 92억 달러에 달했으며, 이는 골판지 상자 수요를 전년 대비 18% 끌어올려 식품 접촉 규정을 충족하는 수성 전분계 접착제의 채택을 촉진했습니다. 이집트의 판지 생산량은 아마존과 Noon이 물류 허브를 확장함에 따라 2025년에 180만 톤에 달하여, 분당 60개의 상자를 생산하는 라인에서 핫멜트 접착제 사용을 주도했습니다. H.B. Fuller의 2025년형 폴리올레핀계 핫멜트 접착제는 15℃ 더 낮은 온도에서 재활용 크라프트 라이너를 접착하여 가공업체의 에너지 사용량을 12% 절감합니다. 사우디아라비아의 전자상거래 보급률은 소매 매출의 14%로 두 배 증가했으며, 이에 따라 조왓(Jowatt)사는 무단 개봉 방지 테이프의 배합 개발을 목적으로 리야드에 기술 센터를 개설했습니다. 또한, 121℃의 살균 처리를 견디는 레토르트 파우치의 경우, 반응성 폴리우레탄 라미네이트용 접착제가 아크릴 에멀젼을 대체하고 있습니다.
엄격한 VOC 규제 및 그린 빌딩 기준
두바이의 그린빌딩 규제는 실내용 접착제의 VOC 함량을 50g/L, 실외용을 100g/L로 제한하고 있어, 이에 따라 배합 개발자들은 수성 시스템으로의 전환을 강요받고 있습니다. 남아프리카공화국의 ‘그린스타’ 평가 제도에서는 30g/L라는 인센티브 대상 기준이 도입되었으나, 2025년 시점에서 이 기준을 충족한 수입 제품은 불과 12%에 그쳤습니다. 사우디아라비아는 2024년에 GSO 2756을 채택하여 EU의 제한 기준을 준용했으나, 제3자 기관의 검사가 필요하게 됨에 따라 제품 출시 주기가 6주 연장되었습니다. 제품 1개당 재조성 비용은 최대 15만 달러에 달하고, 소규모 사업자들의 참여를 주저하게 만들었고, 결과적으로 전용 연구개발 예산을 보유한 다국적 기업들 사이에서 시장 점유율이 집중되는 결과를 낳았습니다. 이집트는 제안되었던 VOC 법의 시행을 2027년까지 연기함으로써, 계획되었던 수성 도료에 대한 투자에 불확실성을 초래했습니다.
부문별 분석
아크릴계 접착제는 2025년 수요의 29.46%를 차지하며, 중동 및 아프리카의 접착제 및 실란트 시장에서 가장 높은 점유율을 기록했습니다. 이는 전자상거래 택배에 사용되는 감압 테이프에서 그 속건성 덕분입니다. 폴리우레탄계 접착제는 모로코의 자동차 앞유리 접착 및 사우디아라비아의 구조용 유리 공사에서 400% 이상의 파단 성장률이 요구됨에 따라, 다른 모든 화학계 접착제를 상회하는 연평균 성장률(CAGR) 6.24%로 확대될 것으로 예측됩니다. 에폭시계 시스템은 풍력 터빈 블레이드나 프리캐스트 콘크리트의 접착 용도에서 수요가 증가하고 있지만, 사용 가능 시간(팟 라이프)이 2시간에 불과하여 공사 일정이 촉박한 현장에서는 채택이 제한되고 있습니다. 실리콘계 접착제는 주로 ISO 10993의 생체적합성이 필수로 요구되는 고온 환경 하의 자동차 부품이나 웨어러블 센서 용도로 사용되고 있습니다.
보다 광범위한 대체 동향으로는 스낵 식품 포장용 라미네이트에서는 아크릴계가 선호되는 반면, 모듈식 건축용 패널 조립에서는 폴리우레탄계의 점유율이 확대되고 있습니다. 시아노아크릴레이트 계열은 애프터마켓 수리 부문에서 틈새 시장으로 자리 잡고 있지만, 골판지 밀봉에는 VAE·EVA 계열 핫멜트가 주류를 이루고 있으며, Jowat와 H.B. Fuller가 지역 공급량의 60%를 차지하고 있습니다. 페놀계 및 폴리아미드계 접착제는 브레이크 라이닝 및 섬유 라미네이트 부문에서 안정적인 수요를 유지하고 있습니다. 인프라 메가 프로젝트가 진행됨에 따라 중동 및 아프리카의 폴리우레탄 배합제와 관련된 접착제 및 실란트 시장 규모는 전체 성장률에 비해 현저히 상승할 것으로 예측되며, 이에 따라 공급업체들의 현지 프리폴리머 합성에 대한 투자가 촉진될 전망입니다.
두바이에서 VOC(휘발성 유기 화합물) 상한치 50g/L가 도입됨에 따라, 2025년 수요 중 수성 제품이 37.28%를 차지하며 중동 및 아프리카의 접착제 및 실란트 시장 전체에서 가장 큰 기술 점유율을 기록했습니다. 2액형 에폭시 및 습기 경화형 폴리우레탄을 포함한 반응성 시스템은 배터리 팩 조립 및 복합 패널 접착에서 고강도와 급속 경화가 중요시됨에 따라, 2031년까지 연평균 성장률(CAGR) 6.31%를 나타낼 것으로 예측됩니다. 핫멜트는 고속 포장 라인에서 사용되며, 폴리올레핀계 기반 제품은 EVA계 제품에 비해 에너지 사용량을 12% 절감합니다.
용제계 제품의 경우 규제가 단계적으로 강화되면서 시장 확대가 제한되고 있습니다. UV 경화형 접착제의 경우, 시카(Seeka)사가 LED 램프 아래에서 8초 만에 경화되는 실리콘 실란트를 출시하여 자동차용 유리 라인의 체류 시간을 절반으로 줄인 데 힘입어 수요가 증가하고 있습니다. 규제 준수 기한이 다가오는 가운데, 중동 및 아프리카의 접착제 및 실란트 시장에서 수성 및 UV 경화형 제품의 점유율은 상승하고 있으며, 기존 용제계 제품 제조업체들은 설비를 갱신할 수밖에 없거나, 수익성이 낮은 부문에서 철수하게 될 것으로 보입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the Middle East and Africa adhesives and sealants market size was valued at USD 1.43 billion in 2025 and is estimated to grow from USD 1.52 billion in 2026 to reach USD 2.03 billion by 2031, at a CAGR of 5.98% during the forecast period (2026-2031).
This report is Segmented by Adhesives Resin (Acrylic, Epoxy, Polyurethane, and More), Adhesives Technology (Hot-Melt, Reactive, Solvent-Borne, UV-Cured, and Water-Borne), Sealants Resin (Polyurethane, Silicone, and More), End-User Industry (Automotive, Construction, and More), and Geography (Saudi Arabia, UAE, South Africa, Egypt, Rest of MEA). Market Forecasts are in Value (USD).
Middle East And Africa Adhesives And Sealants Market Trends and Insights
Construction Mega-Projects Under Saudi Vision 2030
The Public Investment Fund deployed USD 40 billion in 2025 into anchor projects such as NEOM, Qiddiya, and King Salman Park. Curtain-wall glazing at NEOM's linear city uses structural silicone sealants formulated with UV-blocking additives to withstand 12 hours of daily sun exposure. Marine villas in the Red Sea Development rely on polyurethane adhesives able to resist 3,000-hour salt-fog cycles, prompting new one-component systems from Sika and Wacker Chemie. Fast-cure epoxies on precast panels accelerate schedules by 40%, reducing labor on mega sites. Similar specifications extend to Lusail City Phase II in Qatar, where reactive polyurethane sealants bond composite cladding on high-rise towers.
E-Commerce-Led Packaging Boom Across GCC and Egypt
United Arab Emirates e-commerce gross merchandise value reached USD 9.2 billion in 2025, boosting corrugated-box demand 18% year on year and pushing uptake of water-borne starch adhesives that satisfy food-contact regulations. Egyptian paperboard output climbed to 1.8 million metric tons in 2025 as Amazon and Noon scaled fulfillment hubs, driving hot-melt adhesive usage on 60-carton-per-minute lines. H.B. Fuller's 2025 polyolefin hot-melt bonds recycled kraft liner at 15 °C lower temperatures, cutting converter energy use by 12%. Saudi e-commerce penetration doubled to 14% of retail sales, prompting Jowat to open a Riyadh technical center for tamper-evident tape formulations. Reactive polyurethane laminating adhesives are also displacing acrylic emulsions in retort pouches that survive 121 °C sterilization.
Stringent VOC Regulations and Green-Building Codes
Dubai's Green Building Regulations cap interior adhesive VOC content at 50 g/L and exterior at 100 g/L, steering formulators toward water-borne systems. South Africa's Green Star rating introduced a 30 g/L incentive threshold that just 12% of imported products met in 2025. Saudi Arabia adopted GSO 2756 in 2024, mirroring EU limits and extending product-launch cycles by six weeks due to third-party tests. Reformulation costs reach up to USD 150,000 per product, deterring smaller players and consolidating share among multinationals with dedicated R&D budgets. Egypt deferred its proposed VOC law to 2027, injecting uncertainty into planned water-borne investment.
Other drivers and restraints analyzed in the detailed report include:
- Automotive OEM and Aftermarket Expansion in Morocco and Egypt
- Modular Construction Uptake in East Africa
- Petrochemical Feedstock Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acrylic adhesives held 29.46% of 2025 demand, the highest share within the Middle East and Africa adhesives and sealants market, owing to their fast-tack performance in pressure-sensitive tapes used for e-commerce parcels. Polyurethane grades are forecast to expand at a 6.24% CAGR, outpacing all other chemistries as automotive windshield bonding in Morocco and structural glazing in Saudi Arabia demand elongation-at-break above 400%. Epoxy systems are witnessing increased demand from wind-turbine blade and precast-concrete bonding, yet their two-hour pot life constrains uptake on rapid site schedules. Silicone adhesives find their applications mainly in high-temperature automotive and wearable-sensor applications where ISO 10993 biocompatibility is mandatory.
Wider substitution trends favor acrylics in packaging laminates for snack foods, while polyurethanes gain in modular-construction panel assembly. Cyanoacrylates remain niche in aftermarket repair, and VAE/EVA hot-melts dominate carton sealing with Jowat and H.B. Fuller controlling 60% regional supply. Phenolic and polyamide adhesives stay stable in brake-lining and textile lamination. As infrastructure megaprojects advance, the Middle East and Africa adhesives and sealants market size linked to polyurethane formulations is projected to rise disproportionately within overall growth, reinforcing supplier investments in local pre-polymer synthesis.
Water-borne chemistries accounted for 37.28% of 2025 demand following Dubai's 50 g/L VOC ceiling, the largest technology share across the Middle East and Africa adhesives and sealants market. Reactive systems, including two-component epoxies and moisture-cure polyurethanes, are projected to grow at a 6.31% CAGR through 2031 as battery-pack assembly and composite panel bonding prioritize high strength with rapid cure. Hot-melts are used in high-speed packaging lines, where polyolefin bases reduce energy use by 12% over EVA options.
Solvent-borne grades face incremental regulation that restricts their expansion. UV-cured adhesives are witnessing rising demand after Sika introduced a silicone sealant that cures in eight seconds under LED lamps, halving automotive glass line dwell time. As compliance deadlines tighten, the Middle East and Africa adhesives and sealants market share of water-borne and UV platforms will rise, compelling legacy solvent formulators to retool or exit low-margin segments.
Complete Report Scope:
- By Adhesives Resin
- Acrylic
- Cyanoacrylate
- Epoxy
- Polyurethane
- Silicone
- VAE/EVA
- Other Resins
- By Adhesives Technology
- Hot-Melt
- Reactive
- Solvent-Borne
- UV-Cured
- Water-Borne
- By Sealants Resin
- Polyurethane
- Epoxy
- Acrylic
- Silicone
- Polysulfide
- Other Resins
- By End-User Industry
- Aerospace
- Automotive
- Building and Construction
- Footwear and Leather
- Healthcare
- Packaging
- Woodworking and Joinery
- Other End-user Industries
- By Geography
- Saudi Arabia
- South Africa
- United Arab Emirates
- Qatar
- Bahrain
- Egypt
- Rest of Middle-East and Africa
List of Companies Covered in this Report:
- Arkema
- AVERY DENNISON CORPORATION
- 3M
- Dow
- H.B. Fuller Company
- Henkel AG & Co. KGaA
- Huntsman International LLC
- Illinois Tool Works Inc.
- Jowat SE
- MAPEI S.p.A
- Momentive Performance Materials
- Permoseal (Pty) Ltd
- PIDLITE
- RPM International Inc.
- H.B. Fuller Company.
- Sika AG
- Soudal Group
- The Industrial Group Ltd
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Construction mega-projects under Saudi Vision 2030
- 4.2.2 E-commerce-led packaging boom across GCC and Egypt
- 4.2.3 Automotive OEM and aftermarket expansion in Morocco and Egypt
- 4.2.4 Modular construction uptake in East Africa
- 4.2.5 Gulf localisation mandates for hygiene-product adhesives
- 4.3 Market Restraints
- 4.3.1 Stringent VOC regulations and green-building codes
- 4.3.2 Petrochemical feed-stock price volatility
- 4.3.3 Limited cold-chain logistics for water-borne chemistries
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Adhesives Resin
- 5.1.1 Acrylic
- 5.1.2 Cyanoacrylate
- 5.1.3 Epoxy
- 5.1.4 Polyurethane
- 5.1.5 Silicone
- 5.1.6 VAE/EVA
- 5.1.7 Other Resins
- 5.2 By Adhesives Technology
- 5.2.1 Hot-Melt
- 5.2.2 Reactive
- 5.2.3 Solvent-Borne
- 5.2.4 UV-Cured
- 5.2.5 Water-Borne
- 5.3 By Sealants Resin
- 5.3.1 Polyurethane
- 5.3.2 Epoxy
- 5.3.3 Acrylic
- 5.3.4 Silicone
- 5.3.5 Polysulfide
- 5.3.6 Other Resins
- 5.4 By End-User Industry
- 5.4.1 Aerospace
- 5.4.2 Automotive
- 5.4.3 Building and Construction
- 5.4.4 Footwear and Leather
- 5.4.5 Healthcare
- 5.4.6 Packaging
- 5.4.7 Woodworking and Joinery
- 5.4.8 Other End-user Industries
- 5.5 By Geography
- 5.5.1 Saudi Arabia
- 5.5.2 South Africa
- 5.5.3 United Arab Emirates
- 5.5.4 Qatar
- 5.5.5 Bahrain
- 5.5.6 Egypt
- 5.5.7 Rest of Middle-East and Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global-level overview, Market-level overview, Core segments, Financials, Strategic information, Market rank/share, Products and services, Recent developments)
- 6.4.1 Arkema
- 6.4.2 AVERY DENNISON CORPORATION
- 6.4.3 3M
- 6.4.4 Dow
- 6.4.5 H.B. Fuller Company
- 6.4.6 Henkel AG & Co. KGaA
- 6.4.7 Huntsman International LLC
- 6.4.8 Illinois Tool Works Inc.
- 6.4.9 Jowat SE
- 6.4.10 MAPEI S.p.A
- 6.4.11 Momentive Performance Materials
- 6.4.12 Permoseal (Pty) Ltd
- 6.4.13 PIDLITE
- 6.4.14 RPM International Inc.
- 6.4.15 H.B. Fuller Company.
- 6.4.16 Sika AG
- 6.4.17 Soudal Group
- 6.4.18 The Industrial Group Ltd
- 6.4.19 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment