

|
시장보고서
상품코드
2120628
풍력 터빈 유지보수, 수리 및 점검(MRO) : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Wind Turbine Maintenance, Repair, And Overhaul (MRO) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
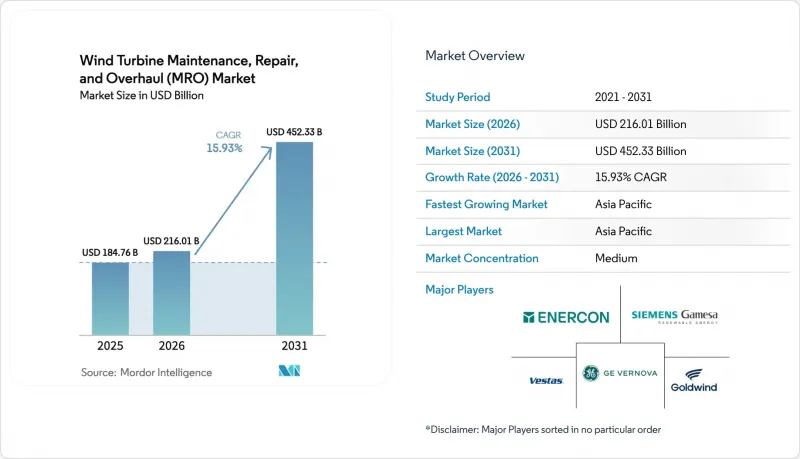
에 의하면, 풍력 터빈 유지보수, 수리 및 점검(MRO) 시장 규모는 2025년에 1,847억 6,000만 달러로 평가되었습니다. 2026년에 2,160억 1,000만 달러에 달하고, 2031년까지 4,523억 3,000만 달러에 이를 것으로 예측되며, 2026-2031년에 걸쳐 CAGR 15.93%로 성장할 전망입니다.
본 보고서는 운영 지역별(온쇼어, 오프쇼어), 서비스 유형별(유지보수, 수리 및 점검), 구성품별(로터 블레이드, 나셀·드라이브트레인, 발전기, 타워, 전력 전자·제어),지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다.
세계의 풍력 터빈 유지보수, 수리 및 점검(MRO) 시장 동향 및 인사이트
수명 연장 개조를 통한 풍력 터빈의 수명 연장
사업자들은 전면적인 리파워링에 비해 4분의 1 수준의 설비 투자로 가동 기간을 5-10년 연장할 수 있는 개조 프로그램을 점점 더 많이 선택하고 있습니다. 독일에서만 해도 블레이드 스퍼 보강 및 메인 베어링 교체를 통해 2005년 이전에 설치된 4GW 이상의 설비 수명을 연장하고 있으며, 새로운 기초 공사에 수반되는 24-36개월의 인허가 취득 기간을 피하고 있습니다. 프로젝트 비용은 일반적으로 터빈 1기당 15만-40만 달러이지만, 완전 교체 시에는 120만-180만 달러가 소요됩니다. 베스타스(Vestas)의 보고에 따르면, 수명 연장 계약이 차지하는 2025년 서비스 수익 비중은 18%에 달하여 2023년의 11%에서 증가했습니다. 미국에서는 인플레이션 억제법(Inflation Reduction Act)의 생산 세액 공제를 통해 기존 설비에서 발생하는 증산분이 보상받기 때문에 이러한 추세가 가속화되고 있습니다. 2024년 DNV GL이 갱신한 IEC 61400 수명 연장 가이드라인의 공표로 인증 리스크가 감소했으며, ISP 각사가 개보수 공사를 놓고 적극적으로 경쟁할 수 있는 길이 열렸습니다.
AI를 활용한 예측 분석을 통한 예기치 못한 가동 중단 시간 감소
SCADA 스트림, 진동 데이터, 열화상 이미지를 분석하는 머신러닝 알고리즘을 통해 고장을 4-8주 전에 감지할 수 있게 되었으며, 사후 대응형 작업 지시가 상태 기반 작업으로 전환되고 있습니다. 2025년 중반까지 25GW에 도입된 지멘스·가메사의 ‘디지털 서비스’ 플랫폼은 예기치 못한 가동 중지 시간을 22% 줄이고, 터빈 1기당 연간 3만 5,000달러의 긴급 출동 비용을 절감했습니다. GE의 ‘Digital Wind Farm’ 제품군은 18GW 규모의 설비에서 가동률을 15% 향상시켰습니다. 해상 풍력 발전소 소유주들은 이 기술을 특히 높이 평가하고 있으며, 조기 경보를 활용하여 개입 작업을 단일 캠페인으로 통합함으로써 선박 용선 비용을 최대 40% 절감하고 있습니다. 2018년 이전에 제조된 터빈은 센서 설치 밀도가 낮아 사후 개조에 한계가 있어, 계측 기기 업그레이드 시장이 형성되고 있습니다.
5MW 초과급 기어박스의 지속적인 신뢰성 문제
베어링의 미세 피팅, 기어의 스파링, 윤활유 오염으로 인해 6-8MW급 풍력 발전 설비에서 기어박스 고장이 가동 중단 시간의 최대 단일 원인으로 지속되고 있으며, 해상 크레인 동원 및 발전 손실을 포함하면 긴급 수리 비용이 120만 달러에 달하기도 합니다. 2024년에 발표된 1,200기의 터빈을 대상으로 한 동료 심사 연구에 따르면, 기어박스는 전체 구성 요소의 12%에 불과함에도 불구하고 총 가동 중단 시간의 38%를 차지하는 것으로 나타났습니다. 지멘스-가메사(Siemens-Gamesa)는 자사의 8MW 플랫폼에서 예상보다 많은 베어링 고장이 발생한 것을 계기로, 보증 적립금을 1억 8,000만 유로 증액했습니다. ZF의 2025년형 모듈식 기어박스는 현장에서 베어링 교체가 가능해 작업 시간을 40% 단축시켜 주지만, 구형 유닛의 개조는 대부분의 소유주에게 여전히 경제성이 떨어지는 상황입니다.
부문별 분석
2025년, 육상 풍력 발전 설비는 풍력 터빈 유지보수, 수리 및 점검(MRO) 시장 매출의 90.1%를 차지했습니다. 이는 도로 접근성이 용이하고 인건비가 저렴하다는 점을 반영한 것입니다. 이 부문에서 터빈 1기당 연간 평균 지출액은 3만 5,000달러 전후이며, 연간 2회의 정기 유지보수 방문이 이루어지고 선박 비용은 최소화됩니다. 대조적으로, 해상 풍력 터빈 유지보수, 수리 및 점검(MRO) 시장 규모에서 해상 부문의 점유율은 급속히 확대되고 있으며, 개발 사업자들이 해안에서 더 멀리 떨어진 곳에 15MW를 초과하는 풍력 터빈을 설치함에 따라 2031년까지 연평균 성장률(CAGR) 28.3%로 성장하고 있습니다. 해상 풍력 터빈 1기당 연간 MRO 지출은 일반적으로 9만 5,000달러이며, 그 비용의 거의 절반을 선박 물류비가 차지합니다.
부유식 풍력 발전의 경우, 여기에 추가적인 비용 요인이 더해집니다. 동적 계류 시스템, 피치 및 롤로 인한 플랫폼의 흔들림, 작업 가능한 기상 조건의 제한된 기간과 같은 요인으로 인해, 흔들림을 보정하는 갱웨이 및 자율형 점검 드론이 필요합니다. 일본이 120억 엔을 투자해 추진하고 있는 로봇식 블레이드 수리 도구 개발 프로그램은 기존 로프 액세스 방식으로는 해상 작업에 불충분하다는 업계의 인식을 여실히 보여주고 있습니다. 해상 작업이 전 세계 전체 작업량에서 차지하는 비중이 높아짐에 따라, 전문 해양 도급업체들은 높은 이익률을 확보하고, 선박과 인증 기술자가 여전히 부족한 이 신흥 공급망을 통합해 나갈 것으로 예측됩니다.
지역별 분석
아시아태평양은 2025년 전 세계 매출의 53.9%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 17.6%를 나타낼 것으로 예측됩니다. 중국의 ‘제14차 5개년 계획’에서는 2015년 이전에 설치된 50GW 규모의 자산을 대상으로 제어 장치 업그레이드와 블레이드 연장이 의무화되어 있어, 이에 따라 개조 비용이 증가하고 해당 지역의 풍력 터빈 유지보수, 수리 및 점검(MRO) 시장 규모가 확대되고 있습니다. 2025년 10월에 개설된 골드윈드의 내몽골 서비스 허브 덕분에 기어박스 및 예비 부품의 리드타임이 절반으로 단축되었습니다. 인도의 생산 연계형 인센티브 제도에서는 정비를 마친 풍력 터빈에 대해 1kWh당 15루피의 보조금이 지급되므로, 소유주는 폐기 처분 대신 여러 부품을 교체하는 재구축에 대한 투자를 촉진하고 있습니다.
유럽은 30GW 규모의 해상 풍력 발전 설비와 엄격한 운영 기준으로 인해 여전히 고부가가치 시장을 형성하고 있습니다. 영국의 ‘라운드 4’ 해저 권리 부여 조건에서는 개발 사업자가 유지보수 작업의 60%를 국내 선박으로 수행해야 할 의무가 있어, 이를 통해 현지 밸류체인의 확충이 촉진되고 있습니다. 독일과 네덜란드는 중량물 운반 작업에 대한 수요를 뒷받침하고 있는 반면, 스페인에서는 6개월의 허가 취득 주기로 인해 육상 풍력 발전소의 리파워링이 가속화되고 있습니다.
북미에서는 ‘인플레이션 감축법(Inflation Reduction Act)’에 따른 생산 세액 공제 연장이 호재로 작용하고 있으며, 이에 따라 기어박스, 블레이드, 인버터 업그레이드 후에도 구형 터빈이 수익성을 유지하며 계속 가동되고 있습니다. 2025년 11월 GE가 수주한 3억 2,000만 달러 규모의 인도 육상 MRO 계약은 개조, 정비, 분석을 결합한 장기 계약에 대한 OEM의 의지를 여실히 보여주고 있습니다.
남미와 중동 및 아프리카는 계속해서 신흥 수요원으로 부상하고 있습니다. 브라질의 ANEEL은 현재 블레이드의 연례 점검과 2년마다의 오일 품질 분석을 의무화하고 있으며, 이로 인해 ISP(점검·유지보수) 부문에 신규 시장 진출기업이 증가하고 있습니다. 모로코와 남아프리카공화국은 2017-2019년에 설치된 풍력 터빈이 수명의 중간 시점에 접어들면서, 아프리카 시장에서 최초로 대규모 오버홀을 맞이하게 될 국가들입니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the wind turbine maintenance, repair, and overhaul market size is projected to be USD 184.76 billion in 2025, USD 216.01 billion in 2026, and reach USD 452.33 billion by 2031, growing at a CAGR of 15.93% from 2026 to 2031.
This report is Segmented by Location of Deployment (Onshore and Offshore), Service Type (Maintenance, Repair, and Overhaul), Component (Rotor Blades, Nacelle and Drivetrain, Generator, Tower, and Power-Electronics and Control), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Wind Turbine Maintenance, Repair, And Overhaul (MRO) Market Trends and Insights
Extended Turbine Lifespans Through Life-Extension Retrofits
Operators are increasingly choosing retrofit programs that add 5-10 additional operating years at one-quarter the capital outlay of full repowering. Germany alone has extended more than 4 GW of pre-2005 capacity by reinforcing blade spars and replacing main bearings, circumventing the 24-36-month permitting cycle tied to new foundations. Project costs typically fall between USD 150,000 and USD 400,000 per turbine, compared with USD 1.2 million to USD 1.8 million for a complete replacement. Vestas reported that life-extension contracts reached 18% of its 2025 service revenue, up from 11% in 2023. The trend is accelerating in the United States because the Inflation Reduction Act's production tax credit rewards incremental output from existing assets. Publication of DNV GL's updated IEC 61400 lifetime-extension guidelines in 2024 has lowered certification risk and opened the door for ISPs to compete aggressively for retrofit work.
AI-Driven Predictive Analytics Reduce Unplanned Downtime
Machine-learning algorithms that parse SCADA streams, vibration data, and thermal imagery are detecting failures 4-8 weeks in advance, turning reactive work orders into condition-based tasks. Siemens Gamesa's Digital Services platform, deployed across 25 GW by mid-2025, lowered unplanned downtime by 22% and trimmed emergency call-out costs by USD 35,000 per turbine per year. GE's Digital Wind Farm suite delivered a 15% availability gain across 18 GW of installations. Offshore owners value the technology most, using early alerts to cluster interventions into single campaigns and shave vessel charter budgets by up to 40%. Retrofits are limited by sparse sensor coverage on turbines built before 2018, creating an aftermarket for instrumentation upgrades.
Persistent Gearbox Reliability Issues in>5 MW Class
Bearing micropitting, gear-tooth spalling, and lubrication contamination keep gearbox failures the largest single cause of downtime in the 6-8 MW fleet, driving emergency repairs that can reach USD 1.2 million when offshore crane mobilization and lost generation are counted. A 2024 peer-reviewed study covering 1,200 turbines found gearbox outages at 38% of total downtime hours despite representing only 12% of the component count. Siemens Gamesa increased warranty provisions by EUR 180 million after higher-than-expected bearing failures on its 8 MW platform. While ZF's 2025 modular gearbox allows in-situ bearing swaps and trims intervention time by 40%, retrofitting legacy units remains uneconomical for most owners.
Other drivers and restraints analyzed in the detailed report include:
- Service-Oriented OEM Business Models (Power-by-the-Hour)
- National Repowering Incentives for >10-Year-Old Fleets
- Scarcity of Blade-Repair Technicians & Composite Materials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Onshore installations represented 90.1% of wind turbine maintenance, repair & overhaul (MRO) market revenue in 2025, reflecting easier road access and lower labor rates. The segment's average annual spend per turbine hovers near USD 35,000, with two scheduled maintenance visits each year and minimal vessel costs. In contrast, the offshore share of the wind turbine maintenance, repair & overhaul (MRO) market size is rising quickly, advancing at 28.3% CAGR through 2031 as developers install >15 MW turbines farther from shore. A single offshore turbine typically consumes USD 95,000 annually in MRO outlays, with vessel logistics absorbing almost half of that bill.
Floating-wind adds yet another cost layer. Dynamic mooring systems, pitch-roll platform motion, and scarcer weather windows require motion-compensated gangways and autonomous inspection drones. Japan's JPY 12 billion program to build robotic blade-repair tools underscores industry recognition that conventional rope-access methods will not suffice offshore. As offshore work claims a larger slice of global capacity, specialized marine contractors are expected to capture outsized margins and consolidate a young supply chain still short on vessels and certified technicians.
Complete Report Scope:
- By Location of Deployment
- Onshore
- Offshore
- By Service Type
- Maintenance
- Repair
- Overhaul
- By Component
- Rotor Blades
- Nacelle and Drivetrain
- Generator
- Tower
- Power-Electronics and Control
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Finland
- Sweden
- Tukey
- Netherlands
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Australia
- Vietnam
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Egypt
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific retained 53.9% of 2025 global revenue and is expected to clock a 17.6% CAGR through 2031. China's 14th Five-Year Plan mandates controller upgrades and blade extensions across 50 GW of pre-2015 assets, lifting retrofit outlays and enlarging the wind turbine maintenance, repair & overhaul (MRO) market size in the region. Goldwind's Inner Mongolia service hub, opened in October 2025, halves lead times for gearboxes and spares. India's production-linked incentive grants INR 15 per kWh for overhauled turbines, encouraging owners to invest in multi-component rebuilds rather than decommission.
Europe remains a high-value arena owing to its 30 GW offshore fleet and strict operating codes. The UK's Round 4 seabed awards compel developers to use domestic vessels for 60% of maintenance activity, spurring local supply-chain build-out. Germany and the Netherlands anchor demand for heavy-lift campaigns, while Spain accelerates onshore repowering with six-month permitting cycles.
North America benefits from the Inflation Reduction Act's extended production tax credit, which keeps older turbines profitably spinning after gearbox, blade, and inverter upgrades. GE's USD 320 million Indian onshore MRO contract in November 2025 illustrates OEM appetite for long-dated agreements that blend retrofit, overhaul, and analytics.
South America and the Middle East & Africa remain emerging contributors. Brazil's ANEEL now enforces annual blade inspections and biennial oil analysis, spawning new ISP entrants. Morocco and South Africa are the first African markets to confront large-scale overhauls as 2017-2019 turbines approach mid-life.
- Siemens Gamesa Renewable Energy SA
- Vestas Wind Systems A/S
- General Electric Company
- Goldwind Science & Technology Co. Ltd.
- Enercon GmbH
- Suzlon Energy Ltd.
- Nordex SE
- Envision Energy Ltd.
- ZF Friedrichshafen AG
- Moventas Gears Oy
- Stork (Fluor)
- Mistras Group
- Integrated Power Services LLC
- Dana SAC UK Ltd.
- Offshore Heavy Transport ASA (OHT)
- B9 Energy O&M Ltd.
- GEV Wind Power
- LM Wind Power (GE)
- BladeRepair.com
- Global Wind Service A/S
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Extended turbine lifespans through life-extension retrofits
- 4.2.2 AI-driven predictive analytics reduce unplanned downtime
- 4.2.3 Service-oriented OEM business models (power-by-the-hour)
- 4.2.4 National repowering incentives for >10-yr-old fleets
- 4.2.5 Floating-wind rollout creates specialized MRO demand
- 4.3 Market Restraints
- 4.3.1 Persistent gearbox reliability issues in >5 MW class
- 4.3.2 Scarcity of blade-repair technicians & composite materials
- 4.3.3 Revenue squeeze from 20-year service contract price-wars
- 4.3.4 Logistics bottlenecks for offshore heavy-lift vessels
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Location of Deployment
- 5.1.1 Onshore
- 5.1.2 Offshore
- 5.2 By Service Type
- 5.2.1 Maintenance
- 5.2.2 Repair
- 5.2.3 Overhaul
- 5.3 By Component
- 5.3.1 Rotor Blades
- 5.3.2 Nacelle and Drivetrain
- 5.3.3 Generator
- 5.3.4 Tower
- 5.3.5 Power-Electronics and Control
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Spain
- 5.4.2.5 Russia
- 5.4.2.6 Finland
- 5.4.2.7 Sweden
- 5.4.2.8 Tukey
- 5.4.2.9 Netherlands
- 5.4.2.10 Rest of Europe
- 5.4.3 Asia Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Vietnam
- 5.4.3.7 Rest of Asia Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Egypt
- 5.4.5.4 Morocco
- 5.4.5.5 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Siemens Gamesa Renewable Energy SA
- 6.4.2 Vestas Wind Systems A/S
- 6.4.3 General Electric Company
- 6.4.4 Goldwind Science & Technology Co. Ltd.
- 6.4.5 Enercon GmbH
- 6.4.6 Suzlon Energy Ltd.
- 6.4.7 Nordex SE
- 6.4.8 Envision Energy Ltd.
- 6.4.9 ZF Friedrichshafen AG
- 6.4.10 Moventas Gears Oy
- 6.4.11 Stork (Fluor)
- 6.4.12 Mistras Group
- 6.4.13 Integrated Power Services LLC
- 6.4.14 Dana SAC UK Ltd.
- 6.4.15 Offshore Heavy Transport ASA (OHT)
- 6.4.16 B9 Energy O&M Ltd.
- 6.4.17 GEV Wind Power
- 6.4.18 LM Wind Power (GE)
- 6.4.19 BladeRepair.com
- 6.4.20 Global Wind Service A/S
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


