|
시장보고서
상품코드
2120668
자동차 에어백 팽창장치 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Airbag Inflator - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
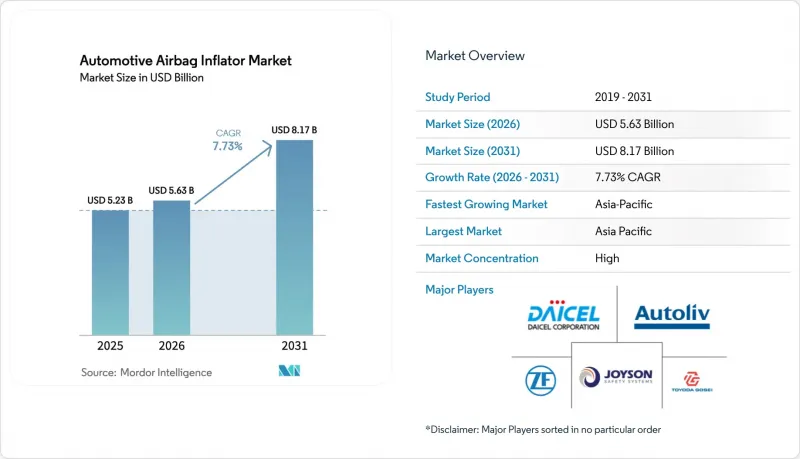
에 의하면, 자동차 에어백 팽창장치 시장 규모는 2025년에 52억 3,000만 달러로 평가되었고, 2026년 56억 3,000만 달러에서 2031년까지 81억 7,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 7.73%를 기록할 전망입니다.
본 보고서는 에어백의 유형(조수석용, 커튼, 무릎 에어백 등), 인플레이터의 유형(화약식, 저장 가스식 등), 차종(승용차 등), 추진제의 화학 조성(아지드계 및 비아지드계),기술 단계(단단식 및 2단/다단식), 판매 채널(OEM 및 애프터마켓), 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 및 수량(단위)으로 제시되어 있습니다.
세계 자동차용 에어백 인플레이터 시장 동향 및 인사이트
EV용 기가캐스팅 섀시가 초박형 커튼 인플레이터 수요를 창출하고 있습니다.
테슬라의 ‘사이버트럭’ 및 ‘모델 Y’는 거대한 프레스기로 주조된 일체형 리어 언더바디를 채택하고 있습니다. 이러한 혁신으로 기존의 B필러 보강 구역이 제거되어 사이드 커튼 인플레이터에 할당되는 공간이 대폭 축소되었습니다. 마찬가지로 BYD의 ‘시걸’ 및 ‘돌핀’ 시리즈도 메가 캐스팅을 채택하여 화이트 바디의 부품 수를 대폭 줄였지만, 그 대가로 안전벨트 고정 장치용 공간이 더욱 제한되는 결과를 낳았습니다. 이에 대응하여 현대모비스는 2024년, 방출 저감 기준을 충족하도록 설계된 도어 장착형 커튼 모듈을 도입했습니다. 그 결과, 각 공급업체들은 원통형 화약식 인플레이터에서 하이브리드형 플랫팩식 장치로 전환하고 있습니다. 이러한 새로운 장치는 아르곤이나 질소 등의 압축 가스와 웨이퍼 형태의 고체 화약을 결합하여 더 빠른 전개와 최고 온도 저하를 실현하고 있습니다. 이러한 전환은 기존 차량에서 여전히 화약식 장치가 널리 사용되고 있음에도 불구하고, 하이브리드식 인플레이터에 대한 지지가 높아지고 있음을 반영합니다.
ADAS 주도 하에 중국산 중형 SUV에 다단식 인플레이터 채택
중국 브랜드가 제조하는 다양한 센서가 탑재된 중형 SUV에서는 충돌 심각도 데이터와 인플레이터의 제어 로직을 융합함으로써, 더 넓은 승객 범위를 보호하기 위한 최적화된 가스 방출을 실현하고 있습니다. 신차 안전 평가 프로그램(NCAP)에서의 5성급 평가는 쇼룸에서의 어필력을 높여주며, 다단계 인플레이터를 ADAS의 가치를 시각적으로 보여주는 증거로 부각시키고 있습니다. 다단계 인플레이터 도입이 지연되고 있는 자동차 제조업체는 쇼룸에서의 비교 평가에서 불리한 입장에 처할 위험이 있으며, 타사를 따라갈 수밖에 없는 압박에 직면해 있습니다. 소프트웨어 업데이트를 통해 향후 보정 미세 조정이 가능해짐에 따라, OEM 제조업체는 설비 갱신 비용을 절감할 수 있습니다. 부품 공급업체들은 이러한 추세를 활용하여 펌웨어 유지보수 계약의 업셀링을 도모하고, 연금형 수익원을 추가하고 있습니다. 따라서 센서 퓨전과 인플레이터 제어의 융합을 통해 자동차 에어백 인플레이터 시장의 프리미엄 가격대가 유지되고 있습니다.
헬륨 공급 부족
지정학적 혼란으로 인해 산업용 헬륨의 현물 가격이 상승하면서, 저장 가스식 인플레이터의 부품 원가가 증가해 이익률이 압박받고 있습니다. 탄자니아에서는 ‘그린 헬륨’ 탐사가 진행 중이며, 예비 유량 데이터에 따르면 안전 시스템 제조업체에 실질적인 상업적 공급이 가능할 것으로 시사되고 있습니다. 이에 대응해 각 OEM 업체들은 헬륨을 화약용 가스로 희석하는 하이브리드식 인플레이터로 조달을 전환하고 있습니다. 현재 계약 조항에는 헬륨 가격 조정 산정식이 포함되어 있어, 위험의 일부가 공급업체 측으로 전가되고 있습니다. 일시적인 현상이긴 하지만, 비용의 급등으로 인해 저장식 인플레이터의 신규 설계 업데이트 속도는 이미 둔화되고 있으며, 자동차 에어백 인플레이터 시장 내 해당 하위 부문의 단기적인 성장세도 주춤하고 있습니다.
부문 분석
2025년, 탑승자용 에어백은 자동차용 에어백 인플레이터 시장 점유율의 30.69%를 차지했습니다. 이러한 우위는 견고한 측면 충돌 보호를 의무화하는 별점 평가 기준에 기인합니다. 최근 사양 업데이트에서는 좁은 루프 레일을 따라 충전 균일성을 높이는 세분화된 가스 유로에 대한 관심이 나타나고 있습니다. 신흥 기가캐스트 EV 프레임에는 더 슬림한 레일이 채택되고 있으므로, 타원형 단면의 실린더를 사용함으로써 루프 높이 제약을 늘리지 않고도 가스용량을 유지할 수 있습니다. 자동차용 에어백 인플레이터 시장에서는 형상 혁신과 신뢰성 높은 화학 기술을 결합한 플랫폼이 계속해서 높이 평가받고 있습니다.
보행자 보호용 에어백은 2031년까지 9.82%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 하지 부상에 더 중점을 두는 충돌 시험용 더미와 보험 평가 모델이 그 보급을 뒷받침하고 있습니다. 공급업체들은 현재 기존 대시보드 하부 빔에 클립으로 고정할 수 있는 일체형 하우징을 제공하여 생산 라인에서의 조립 시간을 단축하고 있습니다. 차량 구매 업체들은 무릎 보호 기능이 탑재된 경우 근로자 재해 보상 청구 건수가 감소한다는 점을 강조하고 있으며, 이는 사양 채택률 향상으로 이어지고 있습니다. 이러한 성장 모멘텀의 확대에 힘입어 자동차용 에어백 인플레이터 업계의 장기적인 다각화가 강화되고 있으며, 단일 지배적 카테고리가 아닌 여러 성장 요인의 혜택을 받고 있습니다.
2025년에는 확립된 공급망과 저장 가스식 대체품에 대한 비용 면에서의 우위를 바탕으로, 화약식 인플레이터가 66.56%의 점유율을 유지하며 여전히 핵심 제품으로서의 지위를 지켰습니다. 그러나 헬륨 가격의 급등과 적응형 제어 시스템의 필요성으로 인해 하이브리드식 인플레이터에 대한 관심이 높아지고 있으며, 이 부문은 연평균 성장률(CAGR) 8.27%로 성장세를 보이고 있습니다. 300바의 헬륨-아르곤 혼합 가스에 의존하는 저장 가스식 장치는 EU의 제재로 인해 공급이 부족해지면서 지지를 잃어가고 있습니다. 하이브리드 설계는 소형 고체 충전재와 가스 저장 탱크를 융합하여, 백의 신속한 충진과 전복 사고 시 장시간 압력 유지를 균형 있게 조화시키는 2단계 팽창을 가능하게 합니다. ZF와 오토리브는 기가 주조를 통해 패키지 깊이를 35mm에 불과하게 확보할 수 있는 전기 SUV를 위해 플랫팩형 하이브리드 모듈의 실증 시험을 진행하고 있습니다.
화약식 인플레이터는 여전히 60리터 에어백을 30밀리초 이내에 팽창시키지만, EU의 REACH 지침에 따라 저독성 질산구아니딘 추진제로의 전환이 진행되고 있습니다. 저장 가스식 인플레이터는 조용한 전개가 가능하다는 점을 위해 추가 비용을 감수하는 틈새 고급차 프로그램에서 채택되고 있습니다. 하이브리드식 인플레이터는 전자 제어 장치와 가변 압력 밸브를 결합한 것으로, 유엔 R155 사이버 보안 규정의 뒷받침을 받아 2031년까지 18%의 시장 점유율을 차지할 것으로 예측됩니다.
지역별 분석
아시아태평양은 2025년 전 세계 매출의 38.88%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 9.42%를 기록할 전망으로, 이는 모든 지역 중 가장 높은 성장률입니다. 2025년에는 중국이 단독으로 자동차용 에어백 인플레이터 시장의 28%를 차지했습니다. 2024년의 엄격한 C-NCAP 규제로 인해, 중국 신차 승용차의 76%에는 이미 2단계식 운전자용 모듈이 탑재되어 있습니다. 인도의 인플레이터 시장은 ‘생산 연계형 인센티브(PLI) 계획’의 혜택을 받고 있으며, 이에 따라 ZF Rane사가 타밀나두주에 300만 유닛 규모의 공장을 건설하는 등의 투자가 촉진되고 있습니다. 일본에서는 개정된 JNCAP 평가 기준이 외부 에어백 채택을 촉진하고 있어, 보행자 보호 기능 보급률이 68%로 다른 국가들을 앞서고 있습니다.
남미는 연평균 성장률(CAGR) 7.23%로 그 뒤를 잇고 있으며, 브라질의 ‘Rota 2030’ 계획에서는 2026년부터 안전벨트 시스템의 대부분에 대해 현지 조달을 의무화하고 있어, 국내에서의 인플레이터 조립이 촉진되고 있습니다. 아르헨티나의 자동차 제조업체들은 메르코수르(MERCOSUR)의 수출 경로를 활용하는 한편, 세계 공급업체의 현지 자회사들은 관세를 회피하기 위해 소규모 공장을 설립하고 있습니다. 북미의 성장률은 4.76%입니다. 운전석·조수석용 에어백의 장착률은 98%로 포화 상태에 이르렀으나, EV 플랫폼의 도입과 타카타(Takata)제 에어백 교체 작업의 지속으로 인해 소폭이지만 상승 추세를 유지하고 있습니다.
유럽은 연평균 성장률(CAGR) 5.44%로 성장을 지속하고, 있습니다. 2026년 1월부터 ‘탄소 국경 조정 메커니즘’이 도입되어 아시아로부터의 수입 비용이 상승함에 따라, 1차 공급업체들은 폴란드와 루마니아에 저탄소 거점을 설립하도록 유도되고 있습니다. 유럽에서는 REACH 규정 준수가 가속화되고 있는 것을 반영하여, 아지화나트륨의 점유율은 이미 26%까지 하락했습니다. 중동 및 아프리카에서는 위조 인플레이터의 유입으로 어려움을 겪고 있으며, 이로 인해 공급업체에 대한 신뢰가 훼손되고 있습니다. 한편, 러시아의 연평균 성장률(CAGR)은 3.51%에 그치고 있는데, 이는 제재로 인해 저장 가스 모듈에 필수적인 헬륨 공급이 차질을 빚고 있기 때문입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the automotive airbag inflator market size was valued at USD 5.23 billion in 2025 and is estimated to grow from USD 5.63 billion in 2026 to reach USD 8.17 billion by 2031, at a CAGR of 7.73% during the forecast period (2026-2031).
This report is Segmented by Airbag Type (Passenger, Curtain, Knee, and More), Inflator Type (Pyrotechnic, Stored-Gas, and More), Vehicle Type (Passenger Cars and More), Propellant Chemistry (Azide-Based and Non-Azide), Technology Stage (Single-Stage, and Dual/Multi-Stage), Sales Channel (OEM and Aftermarket), and Geography. Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Automotive Airbag Inflator Market Trends and Insights
EV Giga-Casting Chassis Creating Need for Ultra-Slim Curtain Inflators
Tesla's Cybertruck and Model Y utilize single-piece rear underbodies, cast in massive presses. This innovation removes traditional B-pillar reinforcement zones and significantly reduces the space available for side-curtain inflators. Similarly, BYD's Seagull and Dolphin lines employ mega-castings, which drastically cut the body-in-white part count but result in a more constrained space for restraint hardware. In response, Hyundai Mobis introduced door-mounted curtain modules in 2024, designed to meet ejection-mitigation standards. As a result, suppliers are shifting from cylindrical pyrotechnic inflators to hybrid flat-pack devices. These newer devices combine compressed gases, such as argon or nitrogen, with a wafer-style solid charge, enabling faster deployment and lower peak temperatures. This transition reflects the growing preference for hybrid inflators, even as pyrotechnic units remain widely used in existing installations.
ADAS-Led Adoption of Multi-Stage Inflators in Chinese Mid-SUVs
Sensor-rich mid-SUVs manufactured by Chinese brands fuse crash-severity data with inflator logic, allowing tailored gas releases that protect a wider occupant range. Five-star New Car Assessment Program scores support showroom appeal and showcase multi-stage inflators as visible proof of ADAS value. Automakers that lag in multi-stage deployment risk negative showroom comparisons, creating fast-follower pressure. Software updates allow future calibration tweaks, shielding OEMs from retooling costs. Component suppliers leverage the trend to upsell firmware maintenance contracts, adding an annuity-style revenue layer. Therefore, the convergence of sensor fusion and inflator modulation sustains premium price points within the automotive airbag inflator market.
Helium Supply Crunch
Geopolitical disruptions lifted industrial-grade helium spot prices, inflating the bill of materials for stored-gas inflators and squeezing margins. Exploration campaigns in Tanzania seek green helium, with preliminary flow-rate data suggesting a viable commercial supply for safety-system producers. OEMs respond by shifting procurement toward hybrid inflators that dilute helium with pyrotechnic gas. Contract clauses now include helium-price adjustment formulas, transferring part of the risk back to suppliers. While temporary, cost spikes have already slowed new design iterations for stored gas, moderating near-term growth for that subsegment of the automotive airbag inflator market.
Other drivers and restraints analyzed in the detailed report include:
- L4/L5 Autonomous Vehicle Rollout Demanding Multi-Directional Inflator Arrays
- Emergence of Indian Export Hubs
- Lithium-Ion Battery Fire Risks Delaying EV Airbag Integration
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger airbags represented 30.69% of the automotive airbag inflator market share in 2025. Their dominance rests on star-rating protocols that mandate robust side-impact protection. Recent refreshes reveal interest in segmented gas channels that enhance fill uniformity along narrow roof rails. Emerging giga-cast EV frames create slimmer rails, so oval-section cylinders preserve gas volume without raising roof-height constraints. The automotive airbag inflator market continues to reward platforms that mix shape innovation with reliable chemistry.
Pedestrian-protection airbags register the fastest 9.82% CAGR to 2031. Crash dummies that weigh more on lower-leg injuries and insurance scoring models reinforce uptake. Suppliers now offer one-piece housings that clip into existing under-dash beams, trimming line-side assembly minutes. Fleet buyers highlight lower worker-compensation claims when knee protection is present, boosting specification rates. Growing traction strengthens the long-term diversity of the automotive airbag inflator industry, which benefits from multiple growth vectors rather than a single dominant category.
Pyrotechnic inflators remained the anchor with a 66.56% share in 2025, supported by well-established supply chains and cost advantages over stored-gas alternatives. However, rising helium prices and the need for adaptive control systems have driven increased interest in hybrid inflators, with the segment gaining traction at an 8.27% CAGR. Stored-gas units, which rely on 300-bar helium-argon blends, lose favor as EU sanctions squeeze supply. Hybrid designs fuse a compact solid charge with a gas reservoir, enabling two-stage inflation that balances rapid bag fill and extended pressure for rollover events. ZF and Autoliv are field-testing flat-pack hybrid modules for electric SUVs whose giga-castings allow only 35 mm of package depth.
Pyrotechnic inflators still inflate a 60-liter bag within 30 ms, but EU REACH directives drive a pivot toward low-toxicity guanidine-nitrate propellants. Stored-gas inflators occupy niche luxury programs that accept cost premiums for quieter deployment. Hybrid inflators are forecast to capture 18% share by 2031, driven by UN R155 cybersecurity rules that pair electronic control units with variable-pressure valves.
Complete Report Scope:
- By Airbag Type
- Passenger
- Curtain
- Knee
- Side
- Pedestrian Protection
- By Inflator Type
- Pyrotechnic
- Stored-Gas
- Hybrid
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Vehicles
- By Propellant Chemistry
- Azide-Based
- Non-Azide (e.g., Guanidine Nitrate)
- By Technology Stage
- Single-Stage
- Dual-Stage & Multi-Stage
- By Sales Channel
- OEM Fitted
- Aftermarket / Recall Replacement
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific owned 38.88% of global revenue in 2025 and is on track for a 9.42% CAGR through 2031, the steepest among all regions. China alone accounted for 28% of the automotive airbag inflator market in 2025; stringent 2024 C-NCAP rules mean 76% of new Chinese passenger cars already feature dual-stage driver modules. India's inflator segment benefits from the Production-Linked Incentive plan, which has prompted investments such as ZF Rane's 3 million-unit plant in Tamil Nadu. Japan leads pedestrian-protection penetration at 68% as revised JNCAP scoring incentivizes external airbags.
South America follows with a 7.23% CAGR, as Brazil's Rota 2030 mandates most local content for restraint systems starting in 2026, encouraging in-country inflator assembly. Argentina's automakers leverage MERCOSUR export routes, while local subsidiaries of global suppliers open smaller plants to bypass tariffs. North America grows at 4.76%; although driver-passenger airbags saturate at 98% fitment, EV platform launches and ongoing Takata replacements sustain nominal upticks.
Europe posts a 5.44% CAGR as the Carbon Border Adjustment Mechanism raises costs on Asian imports from January 2026, motivating tier-ones to establish lower-carbon sites in Poland and Romania. Sodium-azide's share has already dropped to 26% in Europe, reflecting accelerated REACH compliance. The Middle East and Africa wrestle with counterfeit inflator influxes that depress supplier confidence, while Russia's 3.51% CAGR lags due to sanctions cutting helium supplies vital for stored-gas modules.
- Autoliv Inc.
- ZF Friedrichshafen AG
- Joyson Safety Systems (Key SS)
- Daicel Corporation
- Nippon Kayaku Co.
- ARC Automotive Inc.
- Toyoda Gosei Co.
- Hyundai Mobis Co.
- Continental AG
- Denso Corporation
- Yanfeng Safety Systems
- Nihon Plast Co.
- Ashimori Industry Co.
- Takata (Residual Recall Operations)
- Kolon Industries Inc.
- GWR Safety Systems
- ARC China Ltd.
- Tenaris Inflators
- Jinzhou Jinheng Automotive
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Drivers
- 4.1.1 EV Giga-Casting Chassis Creating Need for Ultra-Slim Curtain Inflators
- 4.1.2 ADAS-Led Adoption of Multi-Stage Inflators in Chinese Mid-SUVs
- 4.1.3 L4/L5 Autonomous Vehicle Rollout Demanding Advanced Multi-Directional Inflator Arrays
- 4.1.4 Emergence of Indian Export Hubs Elevating Captive Inflator Off-take
- 4.1.5 Phase-out of Azide Propellants Driving EU & Japan Retrofit Demand
- 4.1.6 UN-R155 Cyber-Security Compliance Boosting Smart Inflator Modules in NA
- 4.2 Market Restraints
- 4.2.1 Helium Supply Crunch Inflating Stored-Gas Inflator Pricing
- 4.2.2 Lithium-ion Battery Fire Risks Delaying EV Airbag System Integration
- 4.2.3 EU Carbon Border Tariff Raising Cost of Asian Inflator Imports
- 4.2.4 Proliferation of Counterfeit Inflators in MEA Eroding OEM Programs
- 4.3 Value / Supply-Chain Analysis
- 4.4 Regulatory or Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value & Volume)
- 5.1 By Airbag Type
- 5.1.1 Passenger
- 5.1.2 Curtain
- 5.1.3 Knee
- 5.1.4 Side
- 5.1.5 Pedestrian Protection
- 5.2 By Inflator Type
- 5.2.1 Pyrotechnic
- 5.2.2 Stored-Gas
- 5.2.3 Hybrid
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Heavy Commercial Vehicles
- 5.4 By Propellant Chemistry
- 5.4.1 Azide-Based
- 5.4.2 Non-Azide (e.g., Guanidine Nitrate)
- 5.5 By Technology Stage
- 5.5.1 Single-Stage
- 5.5.2 Dual-Stage & Multi-Stage
- 5.6 By Sales Channel
- 5.6.1 OEM Fitted
- 5.6.2 Aftermarket / Recall Replacement
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Rest of North America
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Spain
- 5.7.3.5 Russia
- 5.7.3.6 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 India
- 5.7.4.2 China
- 5.7.4.3 Japan
- 5.7.4.4 South Korea
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East and Africa
- 5.7.5.1 United Arab Emirates
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 Turkey
- 5.7.5.4 Egypt
- 5.7.5.5 South Africa
- 5.7.5.6 Rest of Middle-East and Africa
- 5.7.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Autoliv Inc.
- 6.4.2 ZF Friedrichshafen AG
- 6.4.3 Joyson Safety Systems (Key SS)
- 6.4.4 Daicel Corporation
- 6.4.5 Nippon Kayaku Co.
- 6.4.6 ARC Automotive Inc.
- 6.4.7 Toyoda Gosei Co.
- 6.4.8 Hyundai Mobis Co.
- 6.4.9 Continental AG
- 6.4.10 Denso Corporation
- 6.4.11 Yanfeng Safety Systems
- 6.4.12 Nihon Plast Co.
- 6.4.13 Ashimori Industry Co.
- 6.4.14 Takata (Residual Recall Operations)
- 6.4.15 Kolon Industries Inc.
- 6.4.16 GWR Safety Systems
- 6.4.17 ARC China Ltd.
- 6.4.18 Tenaris Inflators
- 6.4.19 Jinzhou Jinheng Automotive
7 Market Opportunities & Future Outlook
- 7.1 White-space and Unmet-Need Assessment