|
시장보고서
상품코드
2120755
고성능 타이어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)High Performance Tires - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
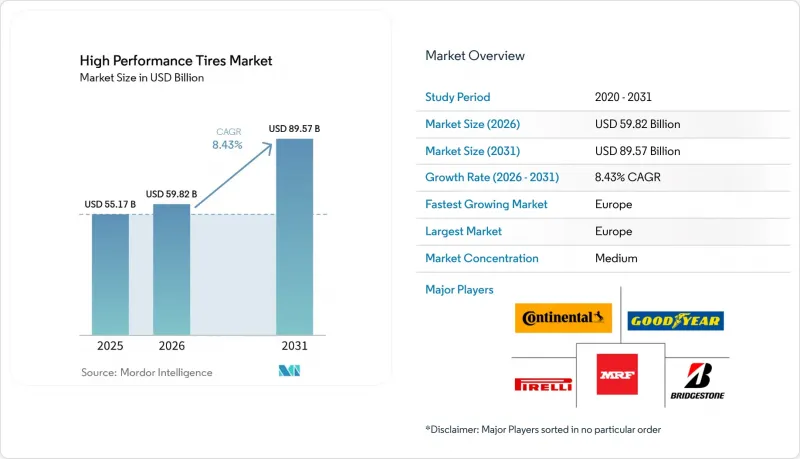
에 의하면, 고성능 타이어 시장 규모는 2025년 551억 7,000만 달러에서 2026년에는 598억 2,000만 달러에 이르고, 2026-2031년 CAGR 8.43%로 성장을 지속하여 2031년에는 895억 7,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 유형별(레이싱 슬릭, 트레드 타이어, 기타), 판매 채널별(OEM 및 애프터마켓), 용도별(레이싱카 등), 타이어 유형별(여름용, 겨울용, 사계절용), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계 고성능 타이어 시장 동향 및 인사이트
전기차의 토크와 중량으로 인해 전용으로 설계된 고성능 타이어가 필요합니다.
배터리식 전기차는 동급 내연기관 모델보다 250-350kg 더 무거워, 이로 인해 접지면에 가해지는 하중이 증가하고, 급가속 시 트레드 마모가 최대 5분의 2까지 가속화됩니다. 2024년 5월에 출시된 브리지스톤의 ‘Turanza EV’는 아라미드 벨트와 고실리카 고무를 조합하여 열을 방출하는 반면, 한코크의 ‘iON evo SUV’는 사이드월을 보강하여 고속도로에서 정숙한 주행을 실현하고 있습니다. 타이어·림 협회는 전기차 전용 하중 지수를 표준화하기 위해 2024년에 ‘고하중(HL)’ 마크를 도입했습니다. 콘티넨탈의 ‘EcoContact Next’는 듀얼 컴파운드 트레드를 채택하여, 전기차 특유의 토크 급상승 시에도 제동 그립을 유지합니다. 2025년에는 전 세계 전기차 판매 대수가 2,000만 대를 넘어설 것으로 예상되는 가운데, 전기차 전용 타이어 라인은 기존의 UHP 타이어에 비해 4분의 1 더 높은 이익률을 실현하고 있습니다.
SUV/고급차의 휠 크기 확대가 OEM용 UHP 타이어 채택을 견인
최근 프리미엄 부문 신차의 상당 부분이 이전보다 현저히 대형화된 휠을 장착하고 있습니다. 포르쉐는 ‘타이칸 크로스투리스모’에 대형 타이어를 채택하고, 메르세데스-벤츠는 ‘EQS’에서 더 큰 옵션을 제안함으로써 한계에 도전하고 있어, 로우 프로파일 UHP 타이어에 대한 수요를 확고히 하고 있습니다. 대형 림은 사이드월의 처짐을 줄여 응답성을 향상시키지만, 동시에 충격 위험도 높입니다. 이에 대응하여 피렐리는 ‘P Zero Elect’ 시리즈에 소음 차단 폼 층을 적용했습니다. 이러한 추세는 걸프 지역에서 고급 SUV가 경차 판매의 상당 부분을 차지하는 중동에서 강력한 지지를 얻고 있습니다.
높은 가격이 비용에 민감한 지역에서의 보급을 저해하고 있다.
세계은행에 따르면, 고성능 타이어는 중급급 대체품에 비해 가격이 훨씬 비싸기 때문에 1인당 소득 수준이 낮은 시장에서는 구하기 어렵습니다. 브라질에서는 인플레이션 심화와 고급 타이어에 대한 높은 수입 관세로 인해 소비자들이 합리적인 가격의 제품을 선택하는 경향이 있습니다. 한편, 남아프리카공화국과 이집트 두 나라에서는 위조 타이어가 시장의 상당한 점유율을 차지하고 있습니다. 동남아시아에서는 유통 구조가 세분화되어 있어 이익률이 제한적이며, 가격에 민감한 소비자들은 접지력보다 내구성을 우선시하고 있습니다.
부문 분석
2025년 기준, 레이싱 슬릭은 고성능 타이어 시장 점유율의 44.72%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 8.49%로 확대될 것으로 예측됩니다. 접지 면적이 넓다는 장점 덕분에 코너링 시 그립력이 크게 향상되는 반면, 젖은 노면에서의 트랙션이 부족하기 때문에 그 사용은 서킷으로 한정되어 있습니다. 균형 잡힌 홈과 실리카가 풍부하게 함유된 컴파운드를 특징으로 하는 트레드가 있는 UHP 여름용 타이어 및 사계절용 타이어는 일상적인 운전 요구를 충족시킵니다. 메르세데스 EQE에 기본 장착된 콘티넨탈의 ‘UltraContact NXT’는 주로 재생 가능한 소재를 배합하고 저소음성을 자랑하여 OEM 순정 타이어로서의 입지를 확고히 하고 있습니다.
피렐리는 FSC 인증 고무와 재생 카본블랙을 채택하여 최신 F1 타이어를 더욱 친환경적인 미래로 이끌고 있습니다. 한편, 슬릭 컴파운드에는 바이오 유래 원료가 점점 더 많이 도입되고 있습니다. 미쉐린의 ‘파일럿 스포츠 5’는 하이브리드 컴파운드 트레드를 통해 뛰어난 젖은 노면 그립력을 유지하면서도 세미 슬릭에 필적하는 랩 타임을 실현하고 있습니다. 장갑차 및 오지용 차량을 위한 런플랫 및 셀프 실링 사양의 타이어는 승차감보다 펑크 저항성을 우선시합니다. 고성능 타이어 시장에서는 트레드가 있는 타이어에 비해 훨씬 높은 매출 총이익률을 자랑하는 특수 슬릭 타이어의 생산이 계속해서 선호되고 있습니다.
2025년 매출의 78.10%를 OEM 채널이 차지하고 있으며, 이는 자동차 제조업체와의 다년간의 형식 인증 계약이 원동력이 되고 있습니다. BMW iX에 탑재된 피렐리의 ‘사이버 타이어’ 센서는 기술 통합의 깊이를 보여줍니다. 그러나 아시아태평양의 ‘트랙 데이’ 문화와 중동의 사막 랠리에 힘입어 애프터마켓은 2031년까지 연평균 8.55%라는 더 빠른 속도로 성장할 것으로 예측됩니다. 세미 슬릭 타이어의 교체 주기는 일상용 차량용보다 훨씬 짧기 때문에 거래액은 크게 증가할 것입니다.
OEM용 출하량은 규모를 확대하고 있지만, 자동차 제조업체들이 계약을 놓고 경쟁함에 따라 매년 지속적인 가격 압박에 직면하고 있습니다. 대조적으로, 애프터마켓의 이익률은 전략적인 유통업체와의 제휴 및 전자상거래가 가져다주는 투명성 덕분에 상당히 높은 수준을 유지하고 있습니다. 굿이어의 ‘이글 F1 어시메트릭 6’은 안전성을 내세워 일상용 운전자층에게 어필하고 있는 반면, BF 굿리치의 오프로드용 타이어 라인업은 사막 랠리 시장을 휩쓸고 있습니다. 고성능 타이어 시장의 이러한 양면성 덕분에, 이 회사는 안정적인 OEM 수주의 혜택을 누리면서도 수익성이 높은 애호가층 수요에도 대응할 수 있게 되었습니다.
지역별 분석
2025년, 유럽은 고성능 타이어 시장의 38.35%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 8.52%를 나타낼 것으로 예측됩니다. 이러한 성장은 주로 ‘유로 7’ 마모 한계치 도입에 의해 주도되고 있으며, 이로 인해 저마모 기술의 혁신이 가속화되고 있습니다. 독일의 각 OEM 업체들은 구름 저항이 높고 센서가 내장된 타이어에 점점 더 주력하고 있으며, 그 결과 피렐리의 ‘Cyber Tyre’나 콘티넨탈의 ‘UltraContact NXT’와 같은 첨단 제품들이 각사의 프리미엄 전기차에 채택되고 있습니다.
중국, 일본, 한국 및 동남아시아 국가들을 포함한 아시아태평양에서는 전동화의 진전과 소득 수준 상승을 배경으로 초고성능(UHP) 타이어의 보급이 급속히 진행되고 있습니다. 중국에서는 더욱 엄격한 기준이 도입됨에 따라 타이어 제조 시 실리카 사용 확대가 촉진되고 있으며, 중책(Zhongce)이나 링롱(Linglong)과 같은 국내 브랜드가 고성능 제품 라인업을 강화하는 데 한몫하고 있습니다. 일본의 브리지스톤과 요코하마 고무는 겨울용 타이어 기술에 대한 전문 지식을 활용하여 수출을 확대하고 있는 반면, 한코크는 포뮬러 E에 대한 독점 공급을 통해 브랜드 이미지를 강화하고 있습니다. 인도에서는 아폴로와 MRF가 열대 기후에 적합한 내열성 컴파운드 개발에 주력하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the high-performance tire market size is expected to grow from USD 55.17 billion in 2025 to USD 59.82 billion in 2026 and is forecast to reach USD 89.57 billion by 2031 at 8.43% CAGR over 2026-2031.
This report is Segmented by Type (Racing Slick, Tread Tire, and Other Types), Sales Channel (OEM and Aftermarket), Application (Racing Cars and More), Tire Type (Summer, Winter, and All-Season), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global High Performance Tires Market Trends and Insights
Electrified-Vehicle Torque & Weight Require Purpose-Built HP Tires
Battery-electric vehicles weigh 250-350 kg more than comparable internal-combustion models, which increases contact-patch loads and accelerates tread wear by up to two-fifths under hard acceleration . Bridgestone's Turanza EV, launched in May 2024, combines aramid belts with high-silica rubber to dissipate heat, while Hankook's iON evo SUV reinforces sidewalls for silent highway running. The Tire and Rim Association introduced the High Load (HL) symbol in 2024 to standardize EV-specific load indices. Continental's EcoContact Next applies a dual-compound tread that maintains braking grip despite EV torque spikes. With global EV sales expected to exceed 20 million units in 2025, dedicated EV lines are earning margin premiums of one-fourth over conventional UHP tires.
SUV / Luxury Rim-Size Upsizing Drives OEM UHP Fitment
In recent years, a significant portion of new vehicles in the premium segment has been equipped with larger wheels, showcasing a notable increase compared to earlier periods. Porsche has opted for large tires on its Taycan Cross Turismo, while Mercedes-Benz is pushing the envelope with even bigger options on its EQS, solidifying the demand for low-profile UHP tires. While larger rims enhance responsiveness by reducing sidewall flex, they also heighten the risk of impact. In response, Pirelli has integrated noise-canceling foam layers into its P Zero Elect series. This trend finds strong backing in the Middle East, where luxury SUVs represent a considerable share of light-vehicle sales in the Gulf region.
Price Premium Curbs Uptake in Cost-Sensitive Regions
According to the World Bank, high-performance tires are significantly more expensive than mid-tier alternatives, making them less accessible in markets with lower per-capita income levels. In Brazil, rising inflation and high import tariffs on premium tires encourage consumers to opt for budget options. Meanwhile, counterfeit tires have captured a notable share of the market in both South Africa and Egypt. In Southeast Asia, a fragmented distribution landscape limits profit margins, as price-sensitive consumers prioritize durability over grip.
Other drivers and restraints analyzed in the detailed report include:
- CO2 / Rolling-Resistance Mandates Accelerate Silica-Rich Compounds
- Euro 7 Particulate Caps Spur Low-Wear Tread Designs
- Natural-Rubber & Petro-Polymer Volatility Squeezes Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Racing slicks held 44.72% of the high-performance tire market share in 2025 and are projected to advance at an 8.49% CAGR to 2031. While their contact-patch advantage significantly enhances cornering grip, the lack of wet-weather traction limits their use to circuits. Treaded UHP summer and all-season tires, featuring balanced grooves and silica-rich compounds, cater to daily driving needs. Continental's UltraContact NXT, now standard on the Mercedes EQE, boasts a blend of predominantly renewable materials and low noise, securing its place in OEM fitments.
Pirelli is steering its latest F1 tires towards a greener future, using FSC-certified rubber and recycled carbon black, while slick compounds are increasingly incorporating bio-based inputs. Michelin's Pilot Sport 5, with its hybrid-compound tread, delivers lap times comparable to semi-slicks, all while maintaining superior wet grip. Catering to armored and remote-area vehicles, run-flat and self-sealing variants prioritize puncture resilience over comfort. The high-performance tire market continues to favor specialized slick production, enjoying significantly higher gross margins than their treaded counterparts.
The OEM channel accounted for 78.10% of 2025 revenue, driven by multi-year homologation contracts with automakers. Pirelli's Cyber Tyre sensors on BMW's iX show the depth of technical integration. Yet, the aftermarket is forecast to grow faster, at 8.55% through 2031, driven by the Asia Pacific's track-day culture and the Middle East's desert rallies. Semi-slick replacements are required much sooner than those for daily drivers, resulting in a significant increase in transaction values.
While OEM volumes achieve scale, they face consistent annual price pressure as automakers competitively bid contracts. In contrast, considerably higher aftermarket margins depend on strategic distributor partnerships and the transparency offered by e-commerce. Goodyear's Eagle F1 Asymmetric 6 capitalizes on safety credentials to appeal to daily drivers, whereas BFGoodrich's off-road lineup dominates the desert-rally segment. This duality in the high-performance tire market allows it to benefit from consistent OEM orders while catering to the lucrative enthusiast demand.
Complete Report Scope:
- By Type
- Racing Slick
- Tread Tire
- Other Types
- By Sales Channel
- OEM
- Aftermarket
- By Application
- Racing Cars
- Off-the-Road Vehicles
- Other Vehicle Types
- By Tire Type
- Summer
- Winter
- All-Season
- By Region
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- Spain
- Italy
- France
- Russia
- Rest of Europe
- Asia Pacific
- India
- China
- Japan
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Europe controlled 38.35% of the high-performance tire market in 2025 and is projected to grow at an 8.52% CAGR through 2031. This growth is largely driven by the introduction of Euro 7 abrasion limits, which are accelerating innovations in low-wear technologies. German OEMs are increasingly focusing on tires with high rolling resistance ratings and integrated sensors, leading to the adoption of advanced products like Pirelli's Cyber Tyre and Continental's UltraContact NXT in their premium electric vehicles.
Asia Pacific, including countries such as China, Japan, South Korea, and those in Southeast Asia, is experiencing rapid growth in the adoption of ultra-high-performance (UHP) tires, fueled by increasing electrification and rising income levels. China's implementation of stricter standards is encouraging greater use of silica in tire production, helping domestic brands like Zhongce and Linglong enhance their performance offerings. Japan's Bridgestone and Yokohama are leveraging their expertise in winter tire technology for exports, while Hankook's exclusive supply to Formula E is strengthening its brand image. In India, Apollo and MRF are focusing on developing heat-resistant compounds suitable for tropical climates.
- Compagnie Generale des Etablissements Michelin
- Bridgestone Corporation
- The Goodyear Tire & Rubber Company
- Continental AG
- Pirelli & C. S.p.A.
- Hankook Tire & Technology Co., Ltd.
- Yokohama Rubber Co., Ltd.
- Sumitomo Rubber Industries, Ltd.
- Nokian Tyres plc (Nokian Renkaat Oyj)
- Toyo Tire & Rubber Co., Ltd.
- Kumho Tire Co., Inc.
- MRF Tyres
- Apollo Tyres Ltd.
- Madras Rubber Factory Limited
- Zhongce Rubber Group Co., Ltd.
- Shandong Linglong Tire Co., Ltd.
- Sailun Group Co., Ltd.
- Giti Tire (Fujian) Co., Ltd.
- Cheng Shin Rubber Ind. Co., Ltd.
- Triangle Tire Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Electrified-Vehicle Torque & Weight Require Purpose-Built HP Tires
- 4.2.2 SUV / Luxury Rim-Size Upsizing Drives OEM UHP Fitment
- 4.2.3 CO2 / Rolling-Resistance Mandates Accelerate Silica-Rich Compounds
- 4.2.4 Euro 7 Particulate Caps Spur Low-Wear Tread Designs
- 4.2.5 Expanding Motorsport & Enthusiast Culture Fuels Aftermarket Demand
- 4.2.6 AI-Enabled Smart-Tire Platforms Create Premium Data Services
- 4.3 Market Restraints
- 4.3.1 Price Premium Curbs Uptake in Cost-Sensitive Regions
- 4.3.2 Natural-Rubber & Petro-Polymer Volatility Squeezes Margins
- 4.3.3 Euro 7 Abrasion Tests Add Compliance Costs
- 4.3.4 Emerging Airless / 3-D-Printed Concepts Threaten Pneumatics
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Type
- 5.1.1 Racing Slick
- 5.1.2 Tread Tire
- 5.1.3 Other Types
- 5.2 By Sales Channel
- 5.2.1 OEM
- 5.2.2 Aftermarket
- 5.3 By Application
- 5.3.1 Racing Cars
- 5.3.2 Off-the-Road Vehicles
- 5.3.3 Other Vehicle Types
- 5.4 By Tire Type
- 5.4.1 Summer
- 5.4.2 Winter
- 5.4.3 All-Season
- 5.5 By Region
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 Spain
- 5.5.3.4 Italy
- 5.5.3.5 France
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Compagnie Generale des Etablissements Michelin
- 6.4.2 Bridgestone Corporation
- 6.4.3 The Goodyear Tire & Rubber Company
- 6.4.4 Continental AG
- 6.4.5 Pirelli & C. S.p.A.
- 6.4.6 Hankook Tire & Technology Co., Ltd.
- 6.4.7 Yokohama Rubber Co., Ltd.
- 6.4.8 Sumitomo Rubber Industries, Ltd.
- 6.4.9 Nokian Tyres plc (Nokian Renkaat Oyj)
- 6.4.10 Toyo Tire & Rubber Co., Ltd.
- 6.4.11 Kumho Tire Co., Inc.
- 6.4.12 MRF Tyres
- 6.4.13 Apollo Tyres Ltd.
- 6.4.14 Madras Rubber Factory Limited
- 6.4.15 Zhongce Rubber Group Co., Ltd.
- 6.4.16 Shandong Linglong Tire Co., Ltd.
- 6.4.17 Sailun Group Co., Ltd.
- 6.4.18 Giti Tire (Fujian) Co., Ltd.
- 6.4.19 Cheng Shin Rubber Ind. Co., Ltd.
- 6.4.20 Triangle Tire Co., Ltd.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment