

|
시장보고서
상품코드
2120830
스포츠 의학 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Sports Medicine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 스포츠 의학 시장 규모는 2025년에 72억 7,000만 달러, 2026년에 77억 4,000만 달러, 2031년까지 107억 6,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 6.81%를 기록할 전망입니다.
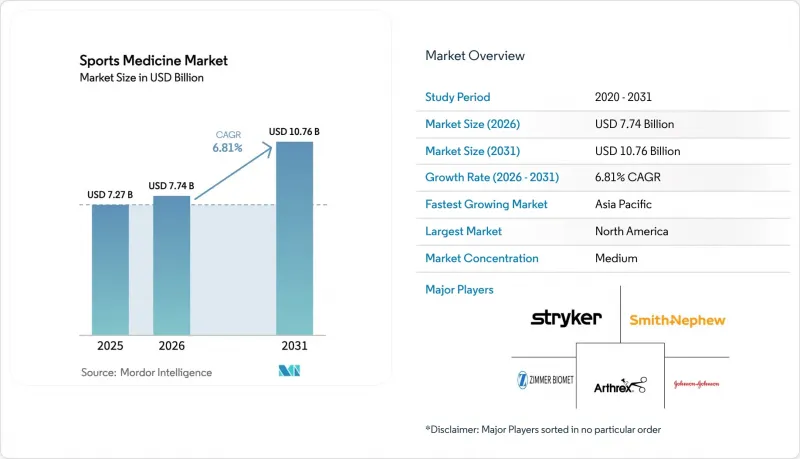
본 보고서는 제품 유형(정형외과용 임플란트 등), 용도(무릎, 어깨, 발·발목, 고관절·서혜부, 팔꿈치, 손·손목, 척추, 기타 손상), 최종 사용자(병원, 외래수술센터(ASC),재택 간호, 기타 최종 사용자), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계 스포츠 의학 시장 동향 및 인사이트
근골격계 및 스포츠 관련 부상으로 인한 부담 증가
2024년에는 17억 1,000만 명 이상이 근골격계 질환을 앓고 있으며, 이는 전 세계적으로 장애의 가장 큰 원인이 되고 있습니다. 스포츠 참여는 부상 유병률에 기여하고 있으며, 미국에서는 연간 약 25만 2,000건의 전방십자인대 재건술이 시행되고 있으며, 여성 운동선수는 생체역학적 및 호르몬적 요인으로 인해 최대 8배 더 높은 위험에 직면해 있습니다. 2024년에는 미국 성인의 24.3%가 만성 통증으로 고통받고 있어, 이로 인해 정형외과 진료, 영상 진단 및 치료에 대한 안정적인 수요가 보장되고 있습니다. 사춘기 스포츠 외상은 수십년후 외과적 치료가 필요한 경우가 많아 ‘미뤄진 수요’가 발생하고 있으며, 이는 장기적인 수요의 안정성을 뒷받침하고 있습니다. 소득 계층에 관계없이 충족되지 않은 임상적 수요는 여전히 높으며, 보험 환급 정책이 변동하더라도 일정한 성장이 예상됩니다.
저침습 관절경 수술로의 전환
1cm 미만의 절개로 감염 위험이 낮아지고, 회복 기간이 단축되며, 당일 퇴원이 가능하기 때문에 현재 연부 조직 복원술에서는 관절경 수술이 주류를 이루고 있습니다. 존슨앤드존슨 메드텍(Johnson & Johnson MedTech)은 2024년, 관절경 수술용 타워에 실시간 분석 기능을 추가하여 기구의 움직임 데이터를 훈련 피드백으로 변환함으로써 숙달 곡선을 단축했습니다. 2024년 FDA 승인을 획득한 지머 바이오메트(Zimmer Biomet)사의 ‘ROSA Shoulder’는 수술 시간을 15% 단축하고 임플란트 위치 결정 정밀도를 향상시킴으로써, 역형 인공 어깨 관절 전치환술을 외래 환경에서 시행하기에 적합하게 만들었습니다. CMS는 2025 회계연도에 외래수술센터(ASC)에 대한 지급액을 2.6% 인상하여 병원 외래 부서와의 격차를 줄이는 동시에 수술의 외래 이전을 촉진하고 있습니다. 관절경 수술은 합병증 발생률이 낮은 것으로 보고되고 있어, 지급 기관은 포괄 지급 제도를 지지하고 있으며, 이를 통해 비용 관리와 환자의 예후가 조화를 이루고 있습니다. 이 기술의 전환에 따라 각 제조업체들은 시각화 시스템, 일회용 셰이버, 멸균 팩에 들어 있는 임플란트 키트 등을 제품 라인업에 추가하고 있습니다.
높은 비용과 보상 불확실성
포괄지불 모델에서는 치료 사례별 지출에 상한선이 설정되고, 수술 후 합병증이 발생한 의료기관에는 페널티가 부과되므로, 임플란트 가격에 대한 적극적인 협상이나 저비용 시스템의 표준화가 불가피합니다. 민간 보험사는 기준가 기반 가격 책정을 채택하고 있으며, 브랜드와 관계없이 보험 지급액을 제한하고 있어 프리미엄 기능에 대한 제조업체의 협상력이 약화되고 있습니다. 혈소판 농축 혈장(PRP) 및 줄기세포 주사에 대한 사전 승인 지연은 전담 청구 담당 직원이 없는 소규모 진료소에 장벽이 되고 있으며, 그 결과 생물학적 제제의 투여량이 억제되고 있습니다. 일본에서는 2년마다 실시되는 보험 급여 재검토에 따라 2024년에 특정 관절경 수술의 보수가 인하되어, 수익 예측을 복잡하게 만드는 국제적인 변동성이 부각되었습니다. 외래수술센터(ASC)는 미미한 이익률로 운영되고 있기 때문에 공급업체에 대해 유연한 위탁 판매 및 위험 분담 조건을 요구하고 있습니다. 이러한 동향으로 인해 의료기기 제조업체는 레지스트리나 실세계 데이터를 통해 자사 제품의 우월성을 입증해야 할 필요에 직면하고 있으며, 그 결과 시장 진입 비용이 증가하고 있습니다.
부문 분석
2025년, 스포츠 의학 시장에서 매출 점유율 35.54%로 가장 큰 비중을 차지한 것은 정형외과용 임플란트였습니다. 이는 외과의사들이 내구성이 뛰어난 기계적 고정을 위해 여전히 나사, 플레이트, 봉합 앵커에 의존하고 있기 때문입니다. 그럼에도 불구하고, 임상적 근거의 확대와 보험 급여 적용 확대에 힘입어 정형외과용 바이오로직스가 가장 급격한 성장 궤도를 확보했습니다. 재생의학용 정형외과 생물학적 제제의 스포츠 의학 시장 규모는 예측 기간 동안 12억 달러에서 23억 달러로 확대될 것으로 예상되며, 이는 생물학적 회복으로의 전환을 여실히 보여주고 있습니다. 병원과 외래 진료 센터에서는 PRP(다혈소판 혈장) 및 골수 농축액을 위한 현장 진단(Point-of-Care) 제제 시스템을 도입하여 무균 상태를 유지하면서 시술 시간을 단축하고 있습니다. 주요 의료기기 제조업체들은 임플란트 제품 라인에 생물 유래 이식편, 콜라겐 스캐폴드, 합성 증량제를 추가하고 있으며, 향후 제품 포트폴리오의 경쟁력은 금속 고정과 생물학적 보강 기술의 융합에 달려 있음이 입증되고 있습니다.
시술 기법의 편차가 치료 결과의 재현성을 저해할 가능성이 있으므로, 외과의사에 대한 교육은 여전히 중요한 촉진요인으로 남아 있습니다. 주요 학술 기관에서는 현재 펠로우십 커리큘럼에 정형생물학적 치료 모듈을 포함시키고, 환자 선정 및 표준화된 주입 프로토콜을 중시하고 있습니다. 동시에 의료 보험사들은 등록 자료를 분석하여, 조기 스포츠 복귀 및 재수술 감소에 따른 장기적인 비용 절감 효과를 확인하고 있습니다. 이러한 데이터가 축적되면 보험 환급 체계가 명확해져, 스포츠 의학 시장 전반에서 정형외과 생물학적 치료의 보급이 더욱 가속화될 것입니다.
지역별 분석
북미는 여전히 가장 중요한 지역 시장으로, 2025년에는 시장의 40.32%를 차지했습니다. 내셔널 풋볼 리그(NFL)와 아마존 웹 서비스(AWS)간의 제휴는 데이터 기반의 부상 예방 접근 방식을 부각시키고 있으며, 그 영향은 대학 및 청소년 프로그램으로까지 파급되어 예측 분석에 대한 수요를 뒷받침하고 있습니다. CMS(미국 의료보험 서비스 센터)는 종합적 지불 모델을 지속적으로 개선하여 가격 투명성을 촉진하는 한편, 임플란트 공급업체에 임상적 가치 검증을 장려하고 있습니다. 밀집된 ASC(외래수술센터(ASC)) 네트워크와 광범위한 민간 보험 적용으로 인해 외래 서비스의 급속한 확산이 촉진되고 있습니다. 사내 물리치료를 포함한 기업 대상 웰니스 이니셔티브 덕분에 초기 단계의 부상에 대해 즉각적인 평가와 의뢰가 이루어지고 있어, 대상 환자층이 더욱 확대되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 7.65%로 성장할 것입니다. 중국은 ‘건강 중국 2030’ 이니셔티브에 따라 지역 재활센터에 자금을 지원하여 조기 개입을 촉진하는 한편, 정형외과 의료에 대한 공공 접근성을 확대되고 있습니다. 인구의 3분의 1 가까이가 65세 이상인 일본에서는 관절 보존 수술에 대한 수요가 지속되고 있지만, 보험 환급액 삭감에 직면해 있어 병원들은 비용 대비 효과가 높은 임플란트 도입을 강요받고 있습니다. 인도에서는 확대되는 중산층이 헬스클럽 회원 수를 늘려 과사용 손상 증가를 초래하는 한편, 민간 정형외과 진료소의 수익을 끌어올리고 있습니다. 규제 환경에는 차이가 있습니다. 중국에서는 신속 승인 제도가 국내 혁신을 뒷받침하고 있는 반면, 일본의 의약품 및 의료기기종합기구(PMDA)는 엄격한 증거 기준을 유지하고 있어 다국에 걸친 임상시험 체계를 갖춘 기업에 유리하게 작용하고 있습니다.
유럽에서는 의료기기 규정 준수 비용과 공공 예산 제약으로 인해 성장에 편차가 나타나고 있습니다. 독일과 프랑스의 대규모 의료 시스템에서는 로봇 수술이 도입되고 있지만, 보험 급여 상한선이 설정되어 있어 임플란트의 고액 비용을 정당화해야 합니다. 중동에서는 의료 관광 수요를 유치하기 위해 정형외과 센터에 대한 투자가 진행되고 있는 반면, 브라질의 상파울루와 리우데자네이루에 있는 사립 병원에서는 환율 변동에도 불구하고 저침습 관절경 수술이 채택되고 있습니다. 이러한 지역들을 종합해 보면, 보험 급여 정책과 인프라의 성숙도가 모자이크처럼 혼재되어 있어 제품 출시 순서나 가격 전략에 영향을 미치고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the sports medicine market size is projected to be USD 7.27 billion in 2025, USD 7.74 billion in 2026, and reach USD 10.76 billion by 2031, growing at a CAGR of 6.81% from 2026 to 2031.
This report is Segmented by Product Type (Orthopedic Implants, and More), Application (Knee, Shoulder, Foot & Ankle, Hip & Groin, Elbow, Hand & Wrist, Spine, and Other Injuries), End User (Hospitals, Ascs, Home Care, and Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America). Market Forecasts are in Value (USD).
Global Sports Medicine Market Trends and Insights
Escalating Burden of Musculoskeletal and Sports-Related Injuries
More than 1.71 billion people lived with musculoskeletal conditions in 2024, making it the leading cause of disability worldwide. Sports participation contributes to injury prevalence, with approximately 252,000 anterior cruciate ligament reconstructions performed annually in the United States, and female athletes facing up to an eight-fold higher risk due to biomechanical and hormonal factors. Chronic pain affected 24.3% of American adults in 2024, ensuring a steady flow of orthopedic consultations, imaging, and interventions. Deferred demand emerges as adolescent sports injuries often require surgical care decades later, underscoring the durable volume pipeline. Across income strata, unmet clinical needs remain high, ensuring baseline growth even when reimbursement policies fluctuate.
Shift Toward Minimally Invasive Arthroscopic Procedures
Arthroscopy now dominates soft-tissue repair because sub-centimeter incisions reduce the risk of infection, shorten recovery time, and support same-day discharge. Johnson & Johnson MedTech added real-time analytics to arthroscopic towers in 2024, converting instrument motion data into training feedback that shortens learning curves. Zimmer Biomet's ROSA Shoulder, cleared by the FDA in 2024, cuts operative time by 15% and improves implant positioning accuracy, making reverse total shoulder arthroplasty suitable for outpatient settings. CMS increased ambulatory surgery center payments by 2.6% for 2025, closing the gap with hospital outpatient departments and incentivizing the migration of procedures. Payers endorse bundled reimbursement because arthroscopy reports low complication rates, aligning cost control with patient outcomes. The technology shift prompts manufacturers to update their product mixes to include visualization systems, single-use shavers, and sterile-packed implant kits.
High Costs and Reimbursement Uncertainty
Bundled payment models cap episode spending and penalize institutions for post-operative complications, forcing aggressive implant price negotiations and standardization around lower-cost systems. Private insurers adopt reference-based pricing, limiting reimbursement irrespective of brand, eroding manufacturer leverage over premium features. Prior authorization delays for platelet-rich plasma and stem-cell injections discourage small practices that lack dedicated billing staff, thereby constraining the volume of biologics. Japan's biennial reimbursement reviews cut specific arthroscopy rates in 2024, illustrating international volatility that complicates revenue forecasting. Ambulatory surgery centers operate on slim margins, demanding flexible consignment and risk-sharing terms from suppliers. These dynamics prompt device makers to validate their superiority through registries and real-world evidence, thereby increasing the cost of market access.
Other drivers and restraints analyzed in the detailed report include:
- Advances in Regenerative and Biologic Therapies
- Rising Investments in Professional Leagues and Fitness Infrastructure
- Proliferation of Low-Cost Counterfeit Bracing Devices Online
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Orthopedic implants contributed the largest 35.54% revenue share of the sports medicine market in 2025 because surgeons remain reliant on screws, plates, and suture anchors for durable mechanical fixation. Nevertheless, orthobiologics secured the steepest growth trajectory, aided by expanding clinical proof points and higher reimbursement adoption. The sports medicine market size for regenerative orthobiologics is projected to rise from USD 1.2 billion to USD 2.3 billion over the forecast period, highlighting the pivot toward biologically driven repair. Hospitals and outpatient centers are integrating point-of-care preparation systems for PRP and bone-marrow concentrates, reducing procedure times while maintaining sterility. Larger device firms are adding biologic grafts, collagen scaffolds, and synthetic extenders to their implant lines, confirming that future portfolio competitiveness hinges on blending metal fixation with biologic augmentation.
Surgeon education remains a crucial enabler because technique variation can hamper outcome reproducibility. Leading academic centers now include orthobiologic modules in fellowship curricula, emphasizing patient selection and standardized injection protocols. Simultaneously, healthcare payers analyze registries to confirm long-term cost offsets from faster return-to-sport and reduced re-operations. Such data, once mature, will clarify reimbursement pathways and further accelerate orthobiologic penetration across the sports medicine market.
Complete Report Scope:
- By Product Type
- Orthopedic Implants
- Arthroscopy Devices
- Orthobiologics
- Braces & Supports
- Bandages & Tapes
- Other Product Types
- By Application
- Knee Injuries
- Shoulder Injuries
- Foot & Ankle Injuries
- Hip & Groin Injuries
- Elbow Injuries
- Hand & Wrist Injuries
- Spine Injuries
- Other Injuries
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Home Care Settings
- Other End User
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest Of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest Of Asia-Pacific
- Middle East And Africa
- GCC
- South Africa
- Rest Of Middle East And Africa
- South America
- Brazil
- Argentina
- Rest Of South America
- North America
Geography Analysis
North America remained the most significant regional contributor, accounting for 40.32% of the market in 2025. The National Football League's collaboration with Amazon Web Services underscores a data-driven approach to injury prevention that reverberates across collegiate and youth programs, boosting demand for predictive analytics. CMS continues to refine bundled payment models, promoting price transparency and encouraging implant suppliers to validate clinical value. Dense ASC networks and widespread private insurance coverage facilitate the rapid adoption of outpatient services. Corporate wellness initiatives that include onsite physiotherapy further enlarge the addressable patient base because early-stage injuries receive immediate evaluation and referral.
Asia-Pacific advances at a 7.65% CAGR to 2031. China funds neighborhood rehabilitation centers under the Healthy China 2030 initiative, encouraging early intervention and expanding public access to orthopedic care. Japan, with nearly one-third of its population aged 65 years or older, sustains demand for joint preservation but faces reimbursement cuts that prompt hospitals to adopt cost-effective implants. India's expanding middle class fuels health club memberships, heightening overuse injuries and increasing private orthopedic practice revenue. Regulatory environments differ: China's fast-track approvals aid domestic innovation, while Japan's Pharmaceuticals and Medical Devices Agency maintains rigorous evidence thresholds that favor companies with multinational clinical operations.
Europe experiences uneven growth due to the costs of complying with the Medical Device Regulation and public budget constraints. Large systems in Germany and France deploy robotic surgery but must justify the premium expense of implants under capped reimbursement. The Middle East invests in orthopedic centers to capitalize on medical tourism, while Brazil's private hospitals in Sao Paulo and Rio de Janeiro adopt minimally invasive arthroscopy, despite currency fluctuations. Combined, these regions present a mosaic of reimbursement policies and infrastructure maturity that influence product launch sequences and pricing strategies.
- Anika Therapeutics
- Arthrex
- Breg
- Conmed
- Enovis Corporation (DJO Global)
- Integra LifeSciences
- Johnson & Johnson
- Karl Storz
- Medtronic
- Mueller Sports Medicine
- Performance Health Holding Inc.
- Smith+Nephew Plc
- Stryker
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Burden of Musculoskeletal and Sports-Related Injuries
- 4.2.2 Shift Toward Minimally Invasive Arthroscopic Procedures
- 4.2.3 Advances in Regenerative and Biologic Therapies
- 4.2.4 Rising Investments in Professional Leagues and Fitness Infrastructure
- 4.2.5 Ambulatory Surgery Center Expansion Accelerating Outpatient Procedures
- 4.2.6 AI-Powered Motion Analysis and Predictive Injury Prevention Tools
- 4.3 Market Restraints
- 4.3.1 High Costs and Reimbursement Uncertainty
- 4.3.2 Stringent Region-Specific Regulatory Requirements
- 4.3.3 Limited Adoption of Digital Rehabilitation Among Aging Cohorts
- 4.3.4 Proliferation of Low-Cost Counterfeit Bracing Devices Online
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitute Products
- 4.7.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Orthopedic Implants
- 5.1.2 Arthroscopy Devices
- 5.1.3 Orthobiologics
- 5.1.4 Braces & Supports
- 5.1.5 Bandages & Tapes
- 5.1.6 Other Product Types
- 5.2 By Application
- 5.2.1 Knee Injuries
- 5.2.2 Shoulder Injuries
- 5.2.3 Foot & Ankle Injuries
- 5.2.4 Hip & Groin Injuries
- 5.2.5 Elbow Injuries
- 5.2.6 Hand & Wrist Injuries
- 5.2.7 Spine Injuries
- 5.2.8 Other Injuries
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Home Care Settings
- 5.3.4 Other End User
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest Of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest Of Asia-Pacific
- 5.4.4 Middle East And Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest Of Middle East And Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest Of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Anika Therapeutics Inc.
- 6.3.2 Arthrex Inc.
- 6.3.3 Breg Inc.
- 6.3.4 CONMED Corporation
- 6.3.5 Enovis Corporation (DJO Global)
- 6.3.6 Integra LifeSciences Corporation
- 6.3.7 Johnson & Johnson Services Inc.
- 6.3.8 KARL STORZ SE & Co. KG
- 6.3.9 Medtronic Plc
- 6.3.10 Mueller Sports Medicine Inc.
- 6.3.11 Performance Health Holding Inc.
- 6.3.12 Smith+Nephew Plc
- 6.3.13 Stryker Corporation
- 6.3.14 Zimmer Biomet Holdings Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


