

|
시장보고서
상품코드
2121277
기술용 세라믹 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Technical Ceramics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
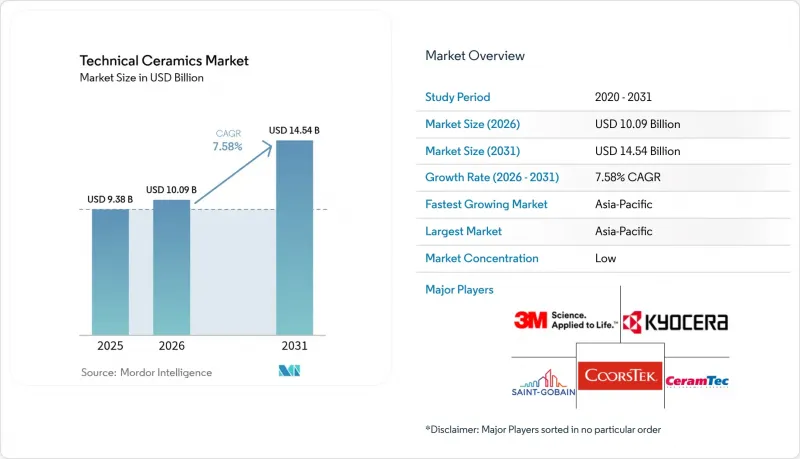
에 의하면, 2026년 산업용 세라믹 시장 규모는 100억 9,000만 달러로 추정되며, 2025년 93억 8,000만 달러에서 2031년에는 145억 4,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 7.58%를 기록할 전망입니다.
본 보고서는 제품 유형(모놀리식 세라믹, 세라믹 매트릭스 복합재료 등), 재료 분류(산화물 세라믹, 비산화물 세라믹, 기타), 최종 사용자 산업(전기 및 전자, 자동차, 기타),주요 용도(절연체·기판, 열 관리 부품, 기타), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다.
전 세계 기술용 세라믹 시장 동향 및 인사이트
아시아태평양의 반도체 및 소비자용 전자기기 생산 확대
대만, 중국 본토, 일본, 한국의 팹 증설로 인해 1,000°C를 초과하는 피크 접합 온도를 견디면서도 유전체의 무결성을 확보할 수 있는 질화알루미늄 및 실리콘카바이드 기판 수요 기준선이 재설정되고 있습니다. 질화 갈륨 아키텍처를 추구하는 칩 설계자들은 기존의 금속 리드 프레임으로는 감당할 수 없을 정도로 열 예산을 급속히 확대하고 있으며, 세라믹 패키지는 처리량 향상을 위해 필수적인 요소가 되고 있습니다. 교세라는 세라믹 기판 공급을 차세대 프로세서 노드와 조율하기 위해 일본 국내의 전용 생산 라인에 4억 7,000만 달러를 투자하고 있습니다. 가마의 검증 주기는 반도체 클린룸보다 길기 때문에 기판의 성장 주기와 리소그래피 양산 일정을 동기화하는 것은 여전히 어렵지만, Tier 1 디바이스 제조업체들은 현재 공급을 확보하기 위해 수년에 걸친 인수 계약을 체결하고 있습니다. 한편, 지방 자치 단체는 해외 원자재에 대한 의존도를 낮추기 위해 첨단 소재 클러스터에 대한 지원을 동시에 추진하고 있습니다. 이러한 정책적 움직임으로 인해 리드타임 단축과 가격 변동 완화가 기대됩니다.
EV 파워트레인의 열 관리 요구
2024년, 전 세계 전기차 출하 대수는 1,500만 대를 돌파했으며, 현재는 거의 모든 플랫폼의 업그레이드에서 더 소형 인버터로 더 많은 전력을 공급하는 800V 전기 아키텍처가 목표로 설정되어 있습니다. 실리콘 카바이드(SiC) 파워 모듈은 실리콘 소자에 비해 3배 빠른 속도로 열을 방출하지만, 허용되는 접합부 온도 범위는 여전히 좁아, 200 W/mK를 초과하는 열전도율을 자랑하는 세라믹 히트 스프레더가 이 설계 요건에 가장 적합합니다. CeramTec사의 ‘칩 온 히트싱크(Chip-on-Heat-Sink)’ 솔루션은 절연 분리를 유지하면서 열 저항을 저감합니다. 이러한 조합을 통해 진동이 심한 자동차 환경에서도 모듈의 수명을 연장할 수 있습니다. 자동차 제조업체는 가격에 민감하지만, 열적 결함으로 인한 보증 책임을 고려할 때 단가는 비싸더라도 신뢰성이 높은 세라믹 제품이 구매 결정 요인이 됩니다. 중국, 유럽, 미국에서 차량의 전기화가 가속화됨에 따라 세라믹 기판, 버스바, 젤 코팅된 냉각 플레이트에 대한 수요도 마찬가지로 확대되고 있습니다.
고유한 취성 및 가공 손실 문제
내열성과 내마모성을 동시에 실현하는 경도는 소결 후 연마 공정에서 파단 위험을 높입니다. 20-30%의 수율 저하는 단가를 상승시키고 리드 타임을 연장시킵니다. 섬유 강화 세라믹 매트릭스 복합재료는 균열 전파를 억제하지만, 적층 및 침투 처리 공정이 추가되기 때문에 내구성 향상을 상쇄할 정도로 공정이 복잡해집니다. 적층 가공는 니어넷쉐이프의 대안을 제공하지만, 사용 가능한 재료의 유형나 생산 능력은 여전히 기존의 프레스 성형에 미치지 못하여, 시제품 제작 이외의 분야에서의 채택은 제한적입니다.
부문 분석
2025년, 모놀리식 세라믹은 대규모 및 균일한 품질을 실현하는 성숙한 프레스 및 소결 라인을 통해 기술용 세라믹 시장에서 46.10%의 점유율을 유지했습니다. 산업용 OEM 기업들이 강철 부품보다 수명이 긴 알루미나 재질의 본체로 펌프, 노즐, 절연체를 교체하고 있기 때문에 이 부문은 여전히 한 자릿수 중반대의 성장률을 기록할 전망입니다. 한편, 복합재 등급은 8.72%의 연평균 성장률(CAGR)을 기록하며, 30% 이상의 경량화와 1,500°C 이상의 내열성을 요구하는 항공우주 및 방위 분야의 예산을 유치하여 기술용 세라믹 시장 전체를 견인할 것으로 보입니다. 2026년에는 엔진 열부 부문만으로도 기술용 세라믹 시장 규모의 11억 8,000만 달러를 차지할 전망입니다. 급속 강제 공기 소결과 같은 가공 기술의 비약적인 발전으로 치밀화 공정이 몇 시간에서 몇 분으로 단축되어 에너지 비용이 절감되고, 모놀리식 제품과의 가격 차이도 줄어들고 있습니다. 이러한 효율화가 진행됨에 따라 복합재료는 모놀리식 제품 시장 점유율을 잠식할 것으로 예상되지만, 자동차 및 산업 플랜트에서는 여전히 예측 가능한 수축률과 낮은 불량률이 중요시되므로 모놀리식 제품을 완전히 대체하지는 않을 것입니다.
코팅 분야는 과도기적인 경로로 기능하고 있습니다. OEM 각사는 기존 금속 부품에 지르코니아나 실리콘 카바이드를 스프레이 도포함으로써, 어셈블리 전체를 재설계하지 않고도 열유속을 단계적으로 향상시킬 수 있습니다. 이러한 개조 방식은 가동 중단에 따른 예산이 제한적인 석유화학용 버너나 디젤 미립자 필터에서 널리 채택되고 있습니다. 세라믹 섬유는 취급 톤수는 적지만, 단열재 시장에서 여전히 큰 영향력을 행사하고 있습니다. 1,100°C까지의 내열성을 갖춘 에어로겔 충전 섬유 퀼트가 LNG 선박의 화물창에 채택되고 있으며, 이는 특수한 성능이 소규모 하위 부문에서 높은 가격을 유지하고 있음을 보여주는 또 다른 지표가 되고 있습니다.
알루미나, 지르코니아, 멀라이트 등의 산화물계 재료는 풍부한 원료 공급과 확립된 공정 관리 덕분에 2025년 매출의 62.80%를 차지했습니다. 이러한 등급의 재료는 다양한 산업 분야에서 커패시터의 유전체나 내마모 플레이트의 기초가 되고 있습니다. 한편, 실리콘 카바이드, 실리콘 나이탈리아드, 그리고 신흥 소재인 붕소 카바이드와 같은 비산화물계 소재는 저밀도이면서도 구리에 버금가는 열전도율을 겸비하고 있어 수주 증가세가 가속화되고 있습니다. 비산화물계 소재는 2031년까지 연평균 7.76%의 성장 궤도에 올라 있으며, 산화물 유리 상으로는 감당할 수 없는 최첨단 디바이스에 대응함으로써 기술용 세라믹 시장을 확대되고 있습니다. 비용 측면의 장벽은 여전히 존재하지만, 제조 라인의 수율이 향상되고 불량률이 5% 미만으로 떨어짐에 따라 비산화물 소재의 가격 프리미엄은 점차 축소되고 있습니다. 규제에 따른 연비 기준 강화와 데이터센터의 열유속 증가는 모두 이러한 고성능 등급에 대해 장기적이고 지속적인 호재가 될 것임을 시사합니다.
복합재료 및 하이브리드 재료 부문에서는 산화물 매트릭스에 비산화물 위스커나 섬유를 융합함으로써 인성과 전도성의 시너지 효과를 실현하고 있습니다. 고전압 하에서 절연 파괴를 견디는 란탄 첨가 알루미나 블렌드에 대한 관심이 높아지고 있으며, 이러한 특성은 그리드 규모의 고체 변압기 프로젝트에서 높이 평가받고 있습니다. 이러한 교차 조합은 향후 시장 점유율 경쟁이 ‘산화물 대 비산화물’이 아닌 ‘하이브리드 대 단일 상’이 될 것이라는 주장을 뒷받침하며, 복잡성은 증가하겠지만 해결책의 선택지는 넓어지고 있습니다.
지역별 분석
아시아태평양은 2025년에 43.40%의 점유율로 기술용 세라믹 시장을 독점하고 있으며, 2031년까지 연평균 성장률(CAGR) 7.84%를 기록할 전망입니다. 중국 본토는 알루미나 분말 소성의 대부분을 담당하고 있으며, 노동 집약적인 마감 공정에서 비용 면에서의 우위를 점하고 있지만, 전기 요금 상승과 환경 규제 준수를 위한 비용으로 인해 기존의 비용 차이는 점차 줄어들고 있습니다. 일본은 국가 반도체 산업 부흥 정책에 따라 초청정·고부가가치 기판으로 사업을 재편하고 있습니다. 교세라의 나가사키 공장은 2026년 가동 개시에 따라 국내 파인 세라믹 생산량을 10% 끌어올릴 전망입니다. 한국의 메모리 칩 산업 중심지는 결함이 적은 실리콘 질화물 기판에 대한 수요를 주도하고 있는 반면, 인도는 구자라트주와 타밀나두주에서의 면세 조치를 통해 전기차(EV) 공급망 투자자를 유치하고 있습니다. 또한 각 지방 정부는 폐기된 지르코니아와 이트리아를 회수하기 위한 재활용 회랑 구축을 추진하고 있으며, 이러한 노력은 장기적으로 원자재 수입 의존도를 낮출 가능성이 있습니다.
북미 시장은 성숙 단계에 있지만 혁신이 활발하여, 세라믹 매트릭스 복합재료와 관련된 전 세계 연구개발비의 30% 가까이를 차지하고 있습니다. 항공우주용 터빈 및 의료용 임플란트 수주의 대부분은 미국이 차지하고 있으며, 규제가 완화된 지역에서는 생략되기 쉬운 ISO 규격의 소성로 및 USP 클래스 VI 클린룸 기준이 이곳에서는 정당화되고 있습니다. 뉴욕에 건설될 생고뱅(Saint-Gobain)사의 4,000만 달러 규모의 촉매 운반체 공장은 100개의 일자리를 창출하는 동시에, 동부 해안의 석유 정제업체에 대한 납기 기간을 단축하게 될 것입니다. 캐나다의 광산 회사는 보크사이트와 희토류 정광을 공급하고 있지만, 여전히 원료의 대부분을 아시아의 제련소로 보내고 있습니다. 멕시코는 전기차(EV)용 인버터 조립 거점으로 부상하고 있으며, 이에 따라 기판 공급업체들은 USMCA(미국·멕시코·캐나다 협정)의 원산지 규정에 따른 관세를 회피하기 위한 니어쇼어링 전략을 검토하기 시작했습니다.
유럽은 전 세계 매출의 약 5분의 1을 차지하며, 상업적 성공과 지속가능성 요건을 모두 충족하고 있습니다. 독일의 공작기계 제조업체는 윤활유 수요를 60% 절감하는 내마모성 알루미나 가이드를 지정하고 있으며, 이는 EU의 에코디자인 기준에 부합합니다. 프랑스와 스페인에서는 수소 허브 시범 사업이 진행 중이며, 조만간 수천 제곱미터 규모의 고체 산화물 전해조 플레이트가 필요할 것으로 예측됩니다. 이 지역의 화학물질 안전 체계인 REACH는 엄격한 추적성을 의무화하고 있으며, 이러한 규정 준수 비용은 기존 기업을 뒷받침하는 한편 신규 사업 출범을 지연시키고 있습니다. 브렉시트 이후 영국의 정책은 첨단 소재 개발 가속화에 중점을 두고 있으며, 대학 연구실의 획기적인 성과를 3년 이내에 시범 생산 라인으로 전환하는 것을 목표로 하고 있습니다. 그러나 국내 수요가 제한적이기 때문에 본격적인 규모 확대는 수출 시장에 좌우될 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, technical ceramics market size in 2026 is estimated at USD 10.09 billion, growing from 2025 value of USD 9.38 billion with 2031 projections showing USD 14.54 billion, growing at 7.58% CAGR over 2026-2031.
This report is Segmented by Product Type (Monolithic Ceramics, Ceramic Matrix Composites, and More), Material Class (Oxide Ceramics, Non-Oxide Ceramics, Others), End-User Industry (Electrical and Electronics, Automotive, and More), Key Application (Insulators & Substrates, Thermal Management Components, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa).
Global Technical Ceramics Market Trends and Insights
Expanding Semiconductor & Consumer-Electronics Output in Asia Pacific
Fab build-outs across Taiwan, mainland China, Japan, and South Korea are resetting the demand baseline for aluminum nitride and silicon carbide substrates that can survive peak junction temperatures exceeding 1,000 °C while ensuring dielectric integrity. Chip designers pursuing gallium nitride architectures are widening thermal budgets faster than legacy metal lead-frames can handle, making ceramic packages an essential throughput enabler. Kyocera is funneling USD 470 million into a dedicated Japanese line to synchronize ceramic substrate availability with next-generation processor nodes. Synchronizing substrate growth cycles with lithography ramp-ups remains difficult because kilns require longer validation loops than semiconductor clean-rooms, but tier-one device makers are now signing multi-year offtake agreements to lock in supply. Regional governments are simultaneously underwriting advanced-materials clusters to reduce reliance on overseas feedstocks, a policy move that could compress lead times and moderate pricing volatility.
EV Power-Train Thermal-Management Needs
Global EV shipments surpassed 15 million units in 2024, and nearly every platform upgrade now targets 800 V electrical architectures that squeeze more power through smaller inverters. Silicon carbide power modules dissipate heat at triple the rate of silicon devices, yet the allowable junction temperature band remains tight, creating a design window ideally served by ceramic heat spreaders boasting greater than 200 W/mK conductivity. CeramTec's chip-on-heatsink solution lowers thermal resistance while maintaining dielectric separation, a combination that lengthens module life in high-vibration automotive environments. Automakers are price-sensitive, but warranty liabilities linked to thermal failures tip purchasing decisions toward high-reliability ceramics despite higher unit costs. As fleet electrification accelerates in China, Europe, and the United States, demand for ceramic substrates, busbars, and gel-coated cooling plates is scaling in parallel.
Intrinsic Brittleness & Machining Losses
Hardness that delivers heat and wear resistance simultaneously increases fracture risk during post-sinter grinding. Yield losses of 20-30% inflate unit costs and lengthen lead times. Fiber-reinforced ceramic-matrix composites mitigate crack propagation but add layer-up and infiltration steps that offset durability gains with higher process complexity. Additive manufacturing offers near-net-shape alternatives, yet material palettes and throughput still lag conventional presses, limiting adoption outside prototyping.
Other drivers and restraints analyzed in the detailed report include:
- Rising Use in High-Value Medical Implants & Devices
- Hydrogen-Electrolyzer Stack Components
- Critical-Minerals Supply-Chain Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monolithic ceramics retained 46.10% technical ceramics market share in 2025 due to mature press-and-sinter lines that deliver uniform quality at scale. The segment should still post mid-single-digit gains as industrial OEMs retrofit pumps, nozzles, and insulators with alumina bodies that outlast steel equivalents. Composite grades, however, will lift the overall technical ceramics market as their 8.72% CAGR attracts aerospace and defense budgets chasing weight savings above 30% alongside thermal ceilings beyond 1,500 °C. In 2026, the engine hot-section segment alone accounts for a USD 1.18 billion slice of the technical ceramics market size. Processing breakthroughs such as rapid forced-air sintering are collapsing densification steps from hours to minutes, trimming energy cost curves, and narrowing price spreads with monolithics. As these efficiencies propagate, composites are expected to erode monolithic share, but not displace them outright, because automotive and industrial plants still prize predictable shrinkage and low scrap rates.
The coatings niche serves as a transitional pathway: OEMs can spray zirconia or silicon carbide onto legacy metal parts, achieving incremental heat-flux gains without redesigning the entire assembly. This retrofit approach is popular in petrochemical burners and diesel particulate filters where shutdown budgets are tight. Ceramic fibers remain small in tonnage yet influential in insulation markets; aerogel-filled fiber quilts rated to 1,100 °C are seeing uptake in LNG ship cargo holds, another indicator that specialized performance credentials sustain premium pricing in smaller sub-segments.
Oxide families such as alumina, zirconia, and mullite delivered 62.80% of 2025 revenue owing to abundant raw material availability and well-documented process controls. These grades form the baseline for capacitor dielectrics and wear plates across multiple industries. Yet silicon carbide, silicon nitride, and emerging boron carbide non-oxide formulations are booking faster order growth because they combine lower density with thermal conductivities approaching copper. The non-oxide cohort is on a 7.76% trajectory through 2031, expanding the technical ceramics market by servicing frontier devices where oxide glass phases cannot survive. Cost barriers persist, but as fab line yields improve and reject rates fall below 5%, non-oxide price premiums are narrowing. Regulatory fuel-economy mandates and data-center heat-flux escalation both point to sustained long-run tailwinds for these higher-performance grades.
Composite or hybrid material classes merge oxide matrices with non-oxide whiskers or fibers, delivering synergistic toughness and conductivity. Interest is building in lanthanum-doped alumina blends that resist dielectric breakdown at elevated voltages, a property valued by grid-scale solid-state transformer projects. These cross-over formulations validate the thesis that future share battles will not be oxide versus non-oxide but hybrid versus single-phase, adding complexity yet widening solution space.
Complete Report Scope:
- By Product Type
- Monolithic Ceramics
- Ceramic Matrix Composites
- Ceramic Coatings
- Other Products
- By Material Class
- Oxide Ceramics
- Non-Oxide Ceramics
- Others
- By End-user Industry
- Electrical and Electronics
- Automotive
- Energy and Power
- Medical
- Aerospace and Defense
- Other End-user Industries
- By Key Application
- Insulators and Substrates
- Thermal Management Components
- Wear-resistant Parts and Bearings
- Bio-implants and Dental
- Armor and Protection
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific dominated the technical ceramics market with 43.40% share in 2025 and is tracking a 7.84% CAGR to 2031. Mainland China hosts the majority of alumina powder calcination and offers cost arbitrage in labor-intensive finishing steps, yet rising electricity tariffs and environmental compliance fees are eroding the historic savings gap. Japan is repositioning toward ultra-clean, high-value substrates that align with national semiconductor revival incentives; Kyocera's Nagasaki site will lift domestic fine-ceramic output by 10% upon its 2026 start-up. South Korea's memory-chip epicenter drives demand for low-defect silicon nitride boards, while India is luring EV supply-chain investors with tax holidays in Gujarat and Tamil Nadu. Regional governments are also mapping recycling corridors to capture scrap zirconia and yttria, an initiative that may dilute raw-material import dependencies over the long term.
North America is mature yet innovation-heavy, claiming nearly 30% of global R&D outlays tied to ceramic matrix composites. The United States accounts for the bulk of aerospace turbine and medical implant orders, justifying ISO-class kilns and USP Class VI clean-room protocols that less regulated regions bypass. Saint-Gobain's USD 40 million catalyst-carrier plant in New York will add 100 jobs and shorten delivery cycles for East-Coast petro-refiners. Canadian mining houses supply bauxite and rare-earth concentrates, but still send most feedstock to Asian refineries. Mexico is emerging as an assembly hub for EV inverters, prompting substrate suppliers to weigh near-shoring steps that sidestep USMCA rules-of-origin tariffs.
Europe claims roughly one-fifth of global revenue and aligns commercial success with sustainability mandates. Germany's machine-tool builders specify wear-resistant alumina guides that cut lubrication demand by 60%, dovetailing with EU eco-design standards. France and Spain are piloting hydrogen hubs that will soon require thousands of square meters of solid-oxide electrolyzer plates. The region's REACH chemical-safety framework compels tight traceability, a compliance cost that props up incumbents but slows new venture launches. Post-Brexit United Kingdom policy leans toward advanced materials catapults, aiming to translate university lab breakthroughs into pilot lines within three years, yet significant scale will hinge on export markets, given limited domestic demand.
- 3M
- CeramTec GmbH
- CoorsTek Inc.
- Dyson Technical Ceramics
- Kyocera Corporation
- Mantec Technical Ceramics Ltd
- McDanel Advanced Ceramic Technologies
- Morgan Advanced Materials
- NGK SPARK PLUG CO., LTD.
- Ortech, inc.
- Rauschert GmbH
- Saint-Gobain
- Schott AG
- STC Material Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding semiconductor and consumer-electronics output in Asia Pacific
- 4.2.2 EV power-train thermal-management needs
- 4.2.3 Rising use in high-value medical implants and devices
- 4.2.4 Hydrogen-electrolyser stack components
- 4.2.5 In-space manufacturing and satellite hardware
- 4.3 Market Restraints
- 4.3.1 High capital and processing cost
- 4.3.2 Intrinsic brittleness and machining losses
- 4.3.3 Critical-minerals supply-chain exposure
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Rivalry
- 4.6 Patent Analysis
- 4.7 Price Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Monolithic Ceramics
- 5.1.2 Ceramic Matrix Composites
- 5.1.3 Ceramic Coatings
- 5.1.4 Other Products
- 5.2 By Material Class
- 5.2.1 Oxide Ceramics
- 5.2.2 Non-Oxide Ceramics
- 5.2.3 Others
- 5.3 By End-user Industry
- 5.3.1 Electrical and Electronics
- 5.3.2 Automotive
- 5.3.3 Energy and Power
- 5.3.4 Medical
- 5.3.5 Aerospace and Defense
- 5.3.6 Other End-user Industries
- 5.4 By Key Application
- 5.4.1 Insulators and Substrates
- 5.4.2 Thermal Management Components
- 5.4.3 Wear-resistant Parts and Bearings
- 5.4.4 Bio-implants and Dental
- 5.4.5 Armor and Protection
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 3M
- 6.4.2 CeramTec GmbH
- 6.4.3 CoorsTek Inc.
- 6.4.4 Dyson Technical Ceramics
- 6.4.5 Kyocera Corporation
- 6.4.6 Mantec Technical Ceramics Ltd
- 6.4.7 McDanel Advanced Ceramic Technologies
- 6.4.8 Morgan Advanced Materials
- 6.4.9 NGK SPARK PLUG CO., LTD.
- 6.4.10 Ortech, inc.
- 6.4.11 Rauschert GmbH
- 6.4.12 Saint-Gobain
- 6.4.13 Schott AG
- 6.4.14 STC Material Solutions
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Increasing Usage in Nano Technology


