

|
시장보고서
상품코드
2121286
무선 재실감지 센서 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wireless Occupancy Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
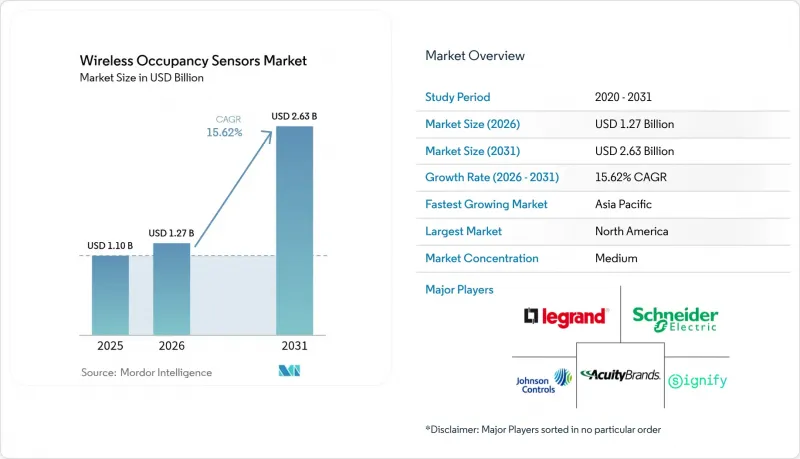
에 따르면 무선 재실감지 센서 시장 규모는 2025년 11억 달러에서 2026년에는 12억 7,000만 달러로 확대되고, 2026년부터 2031년까지 CAGR 15.62%를 기록하며 2031년에는 26억 3,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 기술별(수동형 적외선, 초음파, 듀얼 기술, 기타), 용도별(조명 제어, HVAC·환기, 보안·감시, 기타), 건축 유형별(주거, 상업, 산업, 기타), 네트워크 연결 방식별(Zigbee, Bluetooth/BLE, 기타), 최종사용자 산업별, 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 무선 재실감지 센서 시장의 동향 및 인사이트
엄격한 에너지 효율 규제
유럽연합(EU)의 ‘건축물 에너지 성능에 관한 지침’이나 캘리포니아주의 ‘Title 24’와 같은 에너지 규제에서는 조명 및 HVAC의 자동 제어가 의무화되어 있으며, 이는 무선 재실감지 센서 시장 솔루션에 대한 장기적인 수요의 기반이 되고 있습니다. 뉴욕시의 ‘Local Law 88’에서는 규정 위반에 대한 벌금이 추가되어, 단순한 투자 회수 계산을 넘어선 규제에 의한 수요가 확고해지고 있습니다. 각 제조사들은 EU에서는 5년마다, 미국의 일부 주에서는 3년마다 예측 가능한 갱신 주기를 예상하고 있으며, 이것이 지속적인 연구개발비 지출을 뒷받침하고 있습니다. 또한, 이러한 규제는 그동안 자동화를 선택 사항으로 여겨왔던 중소규모 건물의 개보수를 촉진하는 계기가 되고 있습니다. 이러한 조치들이 복합적으로 작용하여 프로젝트 파이프라인을 가속화하고, 예측 연평균 성장률(CAGR)을 3.2포인트 끌어올리는 요인이 되고 있습니다.
스마트 빌딩 및 IoT의 급속한 보급
Cisco Spaces나 Schneider Electric의 EcoStruxure와 같은 스마트 빌딩 플랫폼은 실시간 재실 데이터를 통합하여 HVAC, 조명, 유지보수를 자동화하고, 센서를 단일 기능 장치에서 기업 분석에 데이터를 제공하는 데이터 노드로 변화시키고 있습니다. Thread 및 Matter 프로토콜을 통해 상호 운용성 문제가 해결되어, Bluetooth, Zigbee, Wi-Fi 기기가 별도의 게이트웨이 없이도 공존할 수 있게 되었습니다. Aqara와 같은 벤더는 PIR 및 밀리파 듀얼 센서를 판매하고 있으며, 이 센서들은 개봉 후 바로 Apple Home, Alexa, Google 생태계에 연결할 수 있어 소비자의 활용 범위를 넓히고 있습니다. 이러한 네트워크 효과로 인해, 특히 아시아태평양의 신규 상업 시설에서 도입 속도가 가속화되고 있습니다. 그 결과, 스마트 빌딩의 보급은 무선 재실감지 센서 시장의 연평균 성장률(CAGR)에 4.1%포인트라는 가장 큰 상승 효과를 가져올 것으로 전망됩니다.
오작동 및 보정 문제
기존의 PIR 센서는 공조 기류나 온도 변동을 잘못 감지하여 사람이 없는데도 조명이 켜지는 경우가 있어, 에너지 절약 효과를 저해하는 원인이 되고 있습니다. 초음파 방식의 비행 시간(ToF) 장치는 이러한 환경에서의 감지 정확도를 향상시키지만, 설치 업체는 감도를 미세 조정해야 하므로 인건비 증가로 이어집니다. 듀얼 기술 융합 방식은 오탐지를 줄여주지만, 부품 수가 두 배로 늘어나고 배터리 소모도 증가합니다. 고급 밀리미터파 레이더는 여전히 고가이며, 많은 전기 기술자에게는 생소한 고도의 설정 작업이 필요합니다. AI를 활용한 자동 보정 기술이 성숙 단계에 도달하기 전까지는 이러한 기술적 장벽으로 인해 무선 재실감지 센서 시장의 연평균 성장률(CAGR)에서 2.1% 포인트가 차감될 것입니다.
부문 분석
수동형 적외선(PIR)은 저렴한 비용과 성숙한 기술 덕분에 2025년에도 45.45%의 점유율을 유지하며, 무선 재실감지 센서 시장 규모 측면에서 주류를 이루고 있습니다. PIR과 초음파 신호를 융합한 듀얼 기술 기기는, 공조 시설이 완비된 오픈 오피스에서 사용자가 더 높은 정확도를 요구함에 따라 20.08%의 연평균 성장률(CAGR)을 기록할 것으로 예측됩니다. 초음파 단독 센서는 안정적인 온도 환경이 음파를 통한 동체 감지에 적합하기 때문에 2위의 점유율을 차지하고 있습니다. 밀리파 레이더는 중요한 조명 및 공조(HVAC) 제어 결정을 위해 1초 이내에 재실 여부를 확인해야 하는 의료, 공항, 고급 오피스 구매자들의 관심을 끌고 있습니다. 컴퓨터 비전 및 음향식 변형 제품은 여전히 틈새 시장이지만, 소매 분석에서 인원 계수의 높은 정확도로 인해 주목받고 있습니다.
벤더들의 로드맵에서는 환경 패턴을 학습하여 오탐지를 대폭 줄이는 AI 융합 엔진의 통합이 진행되고 있으며, 이로 인해 무선 재실감지 센서 시장에 대한 신뢰가 높아지고 있습니다. Aqara의 FP300은 듀얼 PIR, 밀리파, 온도, 습도, 조도 센서를 결합하여 Matter 네트워크로 제어 데이터를 전송합니다. 이러한 플랫폼은 무선 업데이트를 채택하여 알고리즘의 발전에 따라 투자를 보호합니다. 부품 원가(BOM)는 상승하고 있지만, 재방문 감소로 인한 수명주기 비용 절감이 높은 가격을 정당화하며, 대규모 기업 도입의 길을 열어주고 있습니다.
조명 제어 부문은 상업 시설 인테리어 공사에 대한 수십 년간의 규제 덕분에 도입의 혜택을 누리며, 2025년에도 매출의 58.42%를 차지하는 주도적인 위치를 유지했습니다. 한편, 공조·환기 부문은 연평균 성장률(CAGR) 18.74%로 확대될 것으로 예측됩니다. 이는 팬데믹 이후 실내 공기질 기준에 맞춰 기류를 최적화하기 위해 재실자 데이터가 필수적임이 입증되었기 때문입니다. 보안 모니터링 부문에서는 센서를 경보 작동 및 대피 경로 조명에 활용함으로써 예산 전반에 걸친 시너지 효과를 창출하고 있습니다. 가장 높은 가치를 창출하고 있는 것은 ‘공간 이용 분석’ 부문으로, 고도 집계 기능을 통해 고급 부동산의 임대료 최적화가 가능해졌습니다.
Honeywell의 ‘Forge Sustainability+’는 점유 상황에 맞춰 조정된 HVAC가 쾌적성을 유지하면서 팬의 에너지 소비를 40% 절감할 수 있음을 보여주고 있으며, 에너지 계약과 연계된 무선 재실감지 센서 시장 규모에 있어 새로운 ROI의 원천을 개척하고 있습니다. 각 벤더들은 하드웨어 이익률을 넘어 데이터 구독을 수익화할 수 있는 클라우드 대시보드를 패키지로 제공하고 있습니다. 자산 추적 오버레이는 동일한 인프라를 활용하며, 시설 관리자가 추가 설비 투자 없이 TAM을 확대할 수 있는 멀티서비스 플랫폼을 제시하고 있습니다.
지역별 분석
2025년에는 북미가 매출 점유율 34.78%를 차지하며 1위를 기록했습니다. 이는 사실상 모든 상업 프로젝트에서 센서 설치를 의무화하는 ASHRAE 90.1-2019 및 Title 24 건축 기준에 힘입은 결과입니다. 미국은 밀리파 레이더의 연구 개발을 주도하고 있으며, Novelda와 같은 기업들이 환자실 용도로 미세한 움직임까지 추적 가능한 초광대역 감지기를 제공하고 있습니다. 캐나다의 LEED를 중시한 리모델링 추진과 멕시코의 공장 확장으로 인해, 때때로 발생하는 무역 정책의 불확실성에도 불구하고 지역 전체의 판매량은 유지되고 있습니다. 무선 재실감지 센서 시장은 에너지 절약형 기기로의 교체에 대한 연방 정부의 세제 혜택의 수혜를 계속 받고 있습니다.
아시아태평양은 가장 빠르게 성장하는 지역으로, 중국의 스마트 시티 구상과 일본의 제로 에너지 빌딩 목표가 센서 보급을 뒷받침하는 가운데, 연평균 성장률(CAGR)은 17.32%에 달할 것으로 예측됩니다. 인도의 ‘100개 스마트 시티 미션’과 5G의 광범위한 보급으로 인해 상업용 건물에 BLE 기반 시스템을 도입하기에 유리한 환경이 조성되었습니다. 한국은 자국의 전자기기 제조 역량을 활용해 리드타임을 단축하고 시스템 가격을 낮춤으로써, 국내 교육 및 의료 분야에서의 도입을 촉진하고 있습니다. 풍부한 현지 부품 공급 덕분에 이 지역은 전 세계적인 반도체 부족의 영향을 덜 받으며, 무선 재실감지 센서 시장의 성장 궤도를 뒷받침하고 있습니다.
유럽에서는 ‘건물 에너지 성능 지침’이 효과를 발휘하고 있으며, 정기적인 성능 감사가 의무화됨에 따라 지속적인 개보수 주기가 촉진되고 있습니다. 독일은 산업 자동화와의 시너지 효과가 뛰어나며, 한편 영국은 탄소 감축 자금을 공공 부문의 개보수 보조금으로 충당하고 있습니다. 프랑스는 스마트 그리드와 건물 간의 데이터 교환을 통해 수요 반응(Demand Response)에 대해 건물 측에 보상을 지급하는 방안을 모색하고 있으며, 이를 통해 센서는 규정 준수 비용이 아닌 수익을 창출하는 자산이 되고 있습니다. GDPR(일반 데이터 보호 규정)은 구매자를 엣지 처리형 솔루션으로 유도하며, 디바이스 상에서 분석을 수행하는 벤더를 우대하고 있습니다. 이러한 요인들이 결합되어 무선 센서는 유럽의 탈탄소화 로드맵의 핵심 요소로 자리 잡아가고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the wireless occupancy sensors market size is expected to grow from USD 1.1 billion in 2025 to USD 1.27 billion in 2026 and is forecast to reach USD 2.63 billion by 2031 at 15.62% CAGR over 2026-2031.
This report is Segmented by Technology (Passive Infrared, Ultrasonic, Dual Tech, and More), Application (Lighting Control, HVAC & Ventilation, Security & Surveillance, and More), Building Type (Residential, Commercial, Industrial, and More), Network Connectivity (Zigbee, Bluetooth/BLE, and More), End-User Industry, and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Wireless Occupancy Sensors Market Trends and Insights
Stringent Energy-Efficiency Mandates
Energy codes such as the European Union's Energy Performance of Buildings Directive and California Title 24 require automatic lighting and HVAC controls, anchoring long-term demand for wireless occupancy sensors market solutions. New York City's Local Law 88 adds financial penalties for non-compliance, cementing a regulatory pull that transcends simple payback calculations. Manufacturers see predictable upgrade cycles every five years in the EU and every three years in several U.S. states, which encourages sustained R&D spending. The mandates also catalyze retrofits in small and midsize buildings that previously viewed automation as discretionary. Collectively, these measures add 3.2 percentage points to the forecast CAGR by accelerating project pipelines.
Rapid Smart-Building & IoT Adoption
Smart-building platforms such as Cisco Spaces and Schneider Electric EcoStruxure integrate real-time occupancy data to automate HVAC, lighting, and maintenance, transforming sensors from single-function devices into data nodes that feed enterprise analytics. Thread and Matter protocols now remove interoperability headaches, letting Bluetooth, Zigbee, and Wi-Fi devices coexist without proprietary gateways. Vendors like Aqara ship dual PIR and mmWave sensors that join Apple Home, Alexa, and Google ecosystems out of the box, widening consumer reach. These network effects drive faster adoption curves, particularly in Asia-Pacific's new commercial builds. As a result, smart-building penetration will deliver the highest driver uplift at 4.1 percentage points to the wireless occupancy sensors market CAGR.
False Triggering & Calibration Issues
Conventional PIR sensors misread HVAC drafts and temperature swings, causing lights to turn on without occupants and eroding energy-savings claims. Ultrasonic Time-of-Flight devices improve detection in such environments, but installers must fine-tune sensitivity, boosting labor costs. Dual-tech fusion reduces false positives yet doubles component count and battery drain. Premium mmWave radar remains costly and needs skilled setup unfamiliar to many electricians. Until AI-assisted auto-calibration standards mature, these technical frictions subtract 2.1 percentage points from the wireless occupancy sensors market CAGR.
Other drivers and restraints analyzed in the detailed report include:
- Battery-Free Energy-Harvesting Sensors
- Hybrid-Work Demand for Space Analytics
- Data-Privacy & Cybersecurity Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passive Infrared maintained 45.45% share in 2025 thanks to low cost and maturity, positioning it as the volume anchor of the wireless occupancy sensors market. Dual-Tech devices that blend PIR and ultrasonic signals are projected to post a 20.08% CAGR as users demand higher precision in air-conditioned open offices. Ultrasonic standalone sensors hold the runner-up slot where stable temperatures favor sound-based motion detection. mmWave radar attracts healthcare, airport, and premium office buyers that need sub-second presence confirmation for critical lighting and HVAC decisions. Computer-vision and acoustic variants remain niche yet gain attention for people-counting accuracy in retail analytics.
Vendor roadmaps increasingly bundle AI fusion engines that learn environmental patterns to slash false positives, improving confidence in the wireless occupancy sensors market. Aqara's FP300 combines dual PIR, mmWave, temperature, humidity, and illuminance sensing to feed command data into Matter networks. Such platforms use over-the-air updates, protecting investment as algorithms evolve. While BOM costs rise, lifecycle savings from reduced callbacks justify the premium, setting the stage for larger enterprise rollouts.
Lighting Control retained 58.42% revenue dominance in 2025, benefiting from decades of code-driven deployment in commercial fit-outs. Yet HVAC & Ventilation is forecast to expand at a 18.74% CAGR, as occupancy data proves essential for right-sizing airflow to post-pandemic indoor-air-quality standards. Security & Surveillance uses sensors for alarm arming and egress path lighting, offering cross-budget synergies. The highest value accrues to Space-Utilization Analytics, where advanced counting functions enable rent optimization in premium real estate.
Honeywell's Forge Sustainability+ illustrates how occupancy-tuned HVAC can reduce fan energy by 40% while maintaining comfort, unlocking new ROI levers for the wireless occupancy sensors market size tied to energy contracts. Vendors package cloud dashboards that monetize data subscriptions beyond hardware margins. Asset-tracking overlays use the same infrastructure, giving facility managers a multi-service platform that widens TAM without extra capex.
Complete Report Scope:
- By Technology
- Passive Infrared (PIR)
- Ultrasonic
- Dual Tech (PIR + Ultrasonic)
- Microwave / mmWave Radar
- Other Technologies
- By Application
- Lighting Control
- HVAC and Ventilation
- Security and Surveillance
- Space-Utilization Analytics
- Other Applications
- By Building Type
- Residential
- Commercial
- Industrial
- Public and Institutional
- By Network Connectivity
- Zigbee
- Bluetooth / BLE
- Wi-Fi
- EnOcean (Energy-Harvesting)
- LoRa and Other LPWAN
- By End-User Industry
- Smart Buildings
- Healthcare Facilities
- Manufacturing
- Aerospace and Defense
- Consumer Electronics and Smart Home
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led with a 34.78% revenue share in 2025, powered by ASHRAE 90.1-2019 and Title 24 codes that mandate sensors in virtually all commercial projects. The United States spearheads mmWave radar R&D, with firms such as Novelda delivering ultra-wideband detectors capable of micro-motion tracking for patient-room applications Novelda. Canada's LEED-centric retrofit drive and Mexico's factory expansion sustain regional volume despite occasional trade policy uncertainties. The wireless occupancy sensors market continues to benefit from federal tax incentives for energy-efficient equipment upgrades.
Asia-Pacific is the fastest-growing territory, projected to post a 17.32% CAGR as China's smart-city blueprint and Japan's Zero-Energy-Building targets boost sensor penetration. India's 100-Smart-Cities Mission and widespread 5G rollout create fertile ground for BLE-based installations in commercial towers. South Korea leverages its electronics manufacturing capacity to shorten lead times and reduce system prices, driving adoption in local education and healthcare sectors. Abundant local component supply shields the region from global chip shortages, reinforcing the wireless occupancy sensors market growth trajectory.
Europe benefits from the Energy Performance of Buildings Directive, which enforces periodic performance audits that spur continuous retrofit cycles. Germany excels in industrial automation synergies, while the United Kingdom channels carbon-reduction funds into public-sector retrofit grants. France explores smart-grid-to-building data exchanges that pay buildings for demand-response, making sensors revenue-generating assets instead of compliance costs. GDPR steers buyers toward edge-processed solutions, favoring vendors with on-device analytics. Together, these factors embed wireless sensors as a foundational element of Europe's decarbonization roadmap.
- Legrand SA
- Schneider Electric SE
- Acuity Brands Inc.
- Eaton Corporation plc
- Leviton Manufacturing Co. Inc.
- Johnson Controls International plc
- Signify N.V.
- Lutron Electronics Co. Inc.
- Honeywell International Inc.
- General Electric Co.
- Hubbell Incorporated
- ABB Ltd.
- Siemens AG
- Texas Instruments Inc.
- Crestron Electronics Inc.
- Enlighted Inc. (Siemens)
- RAB Lighting Inc.
- Autani LLC
- PointGrab Ltd.
- Delta Electronics Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent energy-efficiency mandates
- 4.2.2 Rapid smart-building and IoT adoption
- 4.2.3 Battery-free energy-harvesting sensors
- 4.2.4 Hybrid-work demand for space analytics
- 4.2.5 ESG-linked occupancy-based HVAC contracts
- 4.2.6 AI-enabled mmWave fusion for zero-latency detection
- 4.3 Market Restraints
- 4.3.1 False triggering and calibration issues
- 4.3.2 Data-privacy and cybersecurity concerns
- 4.3.3 RF congestion in dense IoT deployments
- 4.3.4 Battery-disposal compliance costs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Passive Infrared (PIR)
- 5.1.2 Ultrasonic
- 5.1.3 Dual Tech (PIR + Ultrasonic)
- 5.1.4 Microwave / mmWave Radar
- 5.1.5 Other Technologies
- 5.2 By Application
- 5.2.1 Lighting Control
- 5.2.2 HVAC and Ventilation
- 5.2.3 Security and Surveillance
- 5.2.4 Space-Utilization Analytics
- 5.2.5 Other Applications
- 5.3 By Building Type
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.3.4 Public and Institutional
- 5.4 By Network Connectivity
- 5.4.1 Zigbee
- 5.4.2 Bluetooth / BLE
- 5.4.3 Wi-Fi
- 5.4.4 EnOcean (Energy-Harvesting)
- 5.4.5 LoRa and Other LPWAN
- 5.5 By End-User Industry
- 5.5.1 Smart Buildings
- 5.5.2 Healthcare Facilities
- 5.5.3 Manufacturing
- 5.5.4 Aerospace and Defense
- 5.5.5 Consumer Electronics and Smart Home
- 5.5.6 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 United Kingdom
- 5.6.2.2 Germany
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Rest of Asia-Pacific
- 5.6.4 Middle East
- 5.6.4.1 Israel
- 5.6.4.2 Saudi Arabia
- 5.6.4.3 United Arab Emirates
- 5.6.4.4 Turkey
- 5.6.4.5 Rest of Middle East
- 5.6.5 Africa
- 5.6.5.1 South Africa
- 5.6.5.2 Egypt
- 5.6.5.3 Rest of Africa
- 5.6.6 South America
- 5.6.6.1 Brazil
- 5.6.6.2 Argentina
- 5.6.6.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Legrand SA
- 6.4.2 Schneider Electric SE
- 6.4.3 Acuity Brands Inc.
- 6.4.4 Eaton Corporation plc
- 6.4.5 Leviton Manufacturing Co. Inc.
- 6.4.6 Johnson Controls International plc
- 6.4.7 Signify N.V.
- 6.4.8 Lutron Electronics Co. Inc.
- 6.4.9 Honeywell International Inc.
- 6.4.10 General Electric Co.
- 6.4.11 Hubbell Incorporated
- 6.4.12 ABB Ltd.
- 6.4.13 Siemens AG
- 6.4.14 Texas Instruments Inc.
- 6.4.15 Crestron Electronics Inc.
- 6.4.16 Enlighted Inc. (Siemens)
- 6.4.17 RAB Lighting Inc.
- 6.4.18 Autani LLC
- 6.4.19 PointGrab Ltd.
- 6.4.20 Delta Electronics Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


