|
시장보고서
상품코드
2121334
1,4-부탄디올 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)1,4 Butanediol - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 1,4-부탄디올 시장 규모는 2026년에 266만 톤으로 추정되며, 예측 기간(2026-2031년)에 CAGR 3.64%로 성장을 지속하여, 2031년까지 318만 톤에 이를 전망입니다.
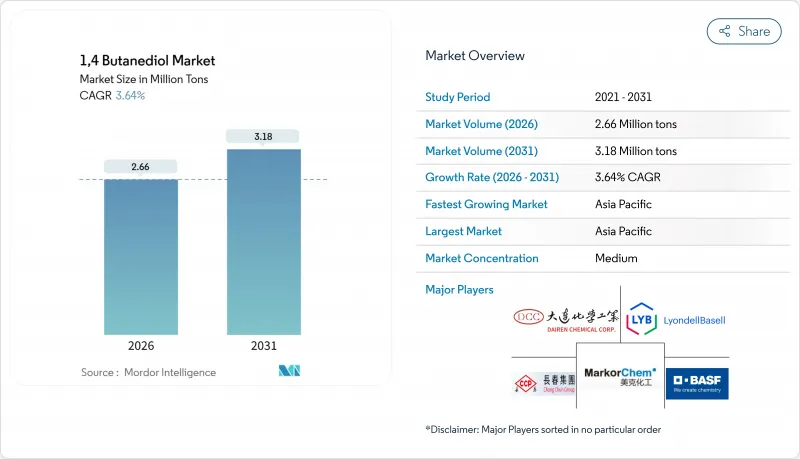
본 보고서는 제조 공정(레페법, 데이비법, 부타디엔계, 프로파일렌옥사이드계 등), 파생 제품(테트라하이드로푸란(THF) 등), 최종 사용자 산업(자동차, 전기 및 전자,의료 및 제약 등) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 수량(톤) 단위로 제시되어 있습니다.
전 세계 1,4-부탄디올 시장 동향 및 인사이트
THF 및 스판덱스 섬유에 대한 수요 증가
테트라하이드로푸란은 스판덱스의 소프트 부문인 폴리테트라메틸렌에테르글리콜로의 관문 분자로서의 지위를 유지하고 있습니다. BASF는 전 세계적으로 5개의 PolyTHF 공장을 운영하고 있으며, 2025년에는 아시아태평양의 산업용 섬유 테크니컬 등급에서 판매량이 두 자릿수 성장을 기록했습니다. 효순은 2025년에 출시한 ‘regen BIO’ 스판덱스에 바이오 BDO를 접목하여, 유럽 및 북미 의류 시장에서 10-15%의 가격 프리미엄을 실현하고 있습니다. 의류 제품의 재고 보충 주기는 내구재 수요보다 빠르게 정상화되기 때문에 THF는 거시경제적 충격에 대한 완충재 역할을 하고 있습니다. 섬유 분야 외에도 PTMEG 등급은 의료용 튜브 및 자동차 내장 필름에 사용되는 열가소성 폴리우레탄(TPU)으로 흘러 들어가며 수요 기반을 확대되고 있습니다.
EV 커넥터의 경량화가 PBT 채택을 뒷받침
고전압 전기차(EV) 플랫폼에는 난연성, 내가수분해성 및 치수 안정성을 갖춘 커넥터 하우징이 요구됩니다. BDO로 합성된 PBT는 이러한 요건을 충족하며, 400-800V 아키텍처에서 PA 6,6을 대체하고 있습니다. BASF의 ‘Ultradur’ 등급은 UL 94 V-0 시험을 통과했으며, 2025년에는 유럽 및 중국의 여러 OEM 제조업체로부터 채택 결정을 받았습니다. 5G 기지국 설치 대수와 데이터센터 건설이 증가함에 따라 고온용 차단기 하우징용 PBT 수요가 높아지고 있으며, 연평균 성장률(CAGR) 3.79%라는 전망이 더욱 확고해지고 있습니다.
산업 안전 보건상의 우려
1,4-부탄디올은 눈, 피부, 호흡기에 자극을 주며, 장기간 노출되면 중추 신경계를 억제합니다. 유럽화학물질청(ECHA) 및 ACGIH는 노출 기준치를 규정하고 있으며, 이로 인해 밀폐형 이송 시스템 및 증기 회수 시스템에 대한 투자가 촉진되고 있습니다. 규제 준수로 인해 운영 비용이 톤당 50-100달러 증가할 가능성이 있어, 자본력이 있는 생산자에게 유리하게 작용합니다. 2024년부터 2025년에 걸쳐 신장 및 산시성의 여러 공장이 환기 설비 개보수 공사로 인해 가동을 중단하면서, 지역별 공급이 일시적으로 부족해졌습니다.
부문별 분석
2025년에도 레페 공법을 이용한 아세틸렌 화학 공정은 총 생산량의 50.18%를 차지하고 있으며, 이는 수십 년에 걸친 기존 인프라의 축적을 반영합니다. 이러한 설비 기반 덕분에 레페 공정에 의존하는 1,4-부탄디올 시장 규모는 2031년까지 계속해서 큰 규모를 유지할 것입니다. 그러나 탄소 인센티브로 인해 석탄 원료를 사용하는 프로젝트의 수익성이 저하되고 있는 것을 배경으로, 바이오 발효를 통한 생산은 연평균 7.52%의 속도로 성장하고 있습니다. 제노마티카(Genomatica)사의 GENO 기술은 BASF의 베르분트(Verbund) 생산 및 효손(Hyosung)의 베트남 복합 시설을 뒷받침하고 있으며, 발효법이 5만 톤 규모의 생산 라인까지 확대 가능하고, 수명 주기 배출량을 90% 감축할 수 있음을 입증하고 있습니다. 프로파일렌 옥사이드 및 부타디엔 경로는 변동 비용이 높고 라이선스 보유자가 제한적이어서 틈새 시장으로 남아 있습니다.
현재 공정의 경제성은 탄소 회계에 좌우되고 있습니다. 유럽에서 곧 시행될 ‘산업 배출 지침’ 개정으로 아세틸렌 플랜트에 대한 VOC(휘발성 유기 화합물) 배출 제한이 강화되어 규정 준수 비용이 상승하는 반면, 바이오 루트를 이용하면 아세틸렌 취급에 따른 위험성을 피할 수 있습니다. 중국의 2060년 탄소 중립 공약에 따라 지역 당국은 석탄으로 아세틸렌을 생산하는 설비의 확장을 억제해야 하는 압력을 받고 있으며, 레페(Leppe)사는 확고한 사업 기반을 보유하고 있음에도 불구하고 시장 점유율이 서서히 하락하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 생산량의 76.12%를 차지할 것으로 보이며, 2031년까지 연평균 성장률(CAGR) 3.94%로 성장할 전망입니다. 신장, 산서, 내몽골에 위치한 중국의 석탄 기반 아세틸렌 생산 클러스터가 이 지역 수요 대부분을 공급하고 있지만, 에너지 집약도와 안전성 감사가 엄격해지면서 간헐적인 가동 중단이 발생하고 있습니다. 효성의 10억 달러 규모 베트남 복합 단지는 동남아시아가 프리미엄 저탄소 공급 시장에 진입했음을 보여주며, 향후 중국의 수출 지배력을 완화할 것으로 보입니다. 인도 수요는 섬유 및 자동차 산업의 확대를 배경으로 두 자릿수 성장을 보이고 있지만, 국내 생산 능력이 부족하여 한국이나 중동으로부터의 수입에 의존하고 있습니다.
북미와 유럽 양 지역에서는 CBAM(탄소국경조정조치)에 따른 제재 및 스코프 3 목표에 대응하기 위해 바이오 BDO 생산 능력 확충이 진행되고 있습니다. BASF, Qore, Novamont 등 3개사는 2024년부터 2026년에 걸쳐 발효를 통한 생산 능력을 연간 총 10만 톤 이상 증강했습니다. 현지 수요는 고부가가치 TPU, PBT, 의약품 중간체로 이동하고 있으며, 이를 통해 생산자들은 원료 가격 변동에 대한 이익의 완충 장치를 확보하고 있습니다.
사우디아라비아의 Sipchem사는 저비용 에탄과 통합된 연산 5만 톤 규모의 공장을 가동 중이며, 폴리우레탄 및 용제 시장을 목표로 하고 있습니다. 브라질은 자동차 및 섬유 분야를 통해 남미의 소비를 주도하고 있지만, 물류 및 환율 장벽이 신규 투자의 걸림돌이 되고 있습니다. 아프리카 수요는 남아프리카공화국의 폴리우레탄 코팅을 중심으로 아직 초기 단계이지만, 인프라 부족이 여전히 장벽으로 작용하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the 1,4 butanediol market size is estimated at 2.66 million tons in 2026, and is expected to reach 3.18 million tons by 2031, at a CAGR of 3.64% during the forecast period (2026-2031).
This report is Segmented by Production Process (Reppe, Davy, Butadiene-Based, Propylene Oxide-Based, and More), Derivative (Tetrahydrofuran (THF) and More), End-User Industry (Automotive, Electrical & Electronics, Healthcare & Pharmaceuticals, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East & Africa). Market Forecasts are Provided in Terms of Volume (tons).
Global 1,4 Butanediol Market Trends and Insights
Rising Demand for THF and Spandex Fibers
Tetrahydrofuran remains the gateway molecule to polytetramethylene ether glycol, the soft segment in spandex. BASF operates five PolyTHF plants worldwide and reported double-digit volume growth in Asia-Pacific technical-textile grades during 2025. Hyosung integrated bio-BDO into its regen BIO spandex, launched in 2025, and is realizing 10-15% price premiums in European and North American apparel markets. Apparel restocking cycles normalize faster than durable-goods demand, giving THF a buffer against macro shocks. Beyond textiles, PTMEG grades flow into thermoplastic polyurethane (TPU) used in medical tubing and automotive interior films, broadening the demand base.
Light-Weighting of EV Connectors Spurring PBT Uptake
High-voltage electric-vehicle platforms require connector housings with flame-retardant, hydrolysis-resistant, and dimensional stability. PBT synthesized from BDO meets these criteria and is displacing PA 6,6 in 400-800 V architectures. BASF's Ultradur grades passed UL 94 V-0 testing and secured design wins at several European and Chinese OEMs in 2025. Rising 5 G base-station installations and data-center construction intensify PBT demand for high-temperature circuit-breaker housings, reinforcing its 3.79% CAGR outlook.
Occupational Health and Safety Concerns
1,4 Butanediol is an eye, skin, and respiratory irritant, and prolonged exposure depresses the central nervous system. The European Chemicals Agency and ACGIH enforce exposure thresholds, prompting investments in closed-loop transfer systems and vapor recovery. Compliance can add USD 50 to USD 100 per ton to operating costs, favoring well-capitalized producers. Several Xinjiang and Shanxi plants halted operations in 2024-2025 for ventilation retrofits, temporarily tightening regional supply.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Polyurethane Applications
- Government Subsidies for Bio-BDO Capacity
- Volatile Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Reppe acetylene chemistry retained 50.18% of total output in 2025, reflecting decades of brownfield infrastructure. The installed base ensures that the 1,4 Butanediol market size tied to Reppe plants remains substantial through 2031. Even so, bio-fermentation grows 7.52% annually, propelled by carbon incentives that tilt project economics away from coal feedstocks. Genomatica's GENO technology underpins BASF's Verbund output and Hyosung's Vietnam complex, proving that fermentation can scale to 50,000-ton trains with 90% lower life-cycle emissions. Propylene-oxide and butadiene routes stay niche because of higher variable costs and limited license holders.
Process economics now hinge on carbon accounting. Europe's forthcoming Industrial Emissions Directive revision tightens VOC limits on acetylene plants, lifting compliance costs, while bio-routes sidestep acetylene-handling hazards. China's 2060 carbon-neutrality pledge pressures regional authorities to curb coal-to-acetylene expansions, gradually eroding Reppe's share despite its entrenched footprint.
Complete Report Scope:
- By Production Process
- Reppe Process
- Davy Process
- Butadiene-Based Process
- Propylene Oxide-Based Process
- Bio-fermentation Route
- By Derivative
- Tetrahydrofuran (THF)
- Polybutylene Terephthalate (PBT)
- Gamma-Butyrolactone (GBL)
- Polyurethane (PU)
- Other Derivatives
- By End-user Industry
- Automotive
- Textile
- Electrical and Electronics
- Healthcare and Pharmaceuticals
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 76.12% of global volume in 2025 and is set to grow at a 3.94% CAGR through 2031. China's coal-to-acetylene clusters in Xinjiang, Shanxi, and Inner Mongolia supply most regional needs but face tightening energy-intensity and safety audits, creating intermittent outages. Hyosung's USD 1 billion Vietnam complex marks Southeast Asia's entry into premium low-carbon supply and will eventually relieve Chinese export dominance. India's demand is climbing at double digits on the back of textile and automotive expansions, but lacks domestic capacity, relying on Korean and Middle-East imports.
North America and Europe, both regions, advance bio-BDO capacity to hedge CBAM penalties and Scope 3 targets. BASF, Qore, and Novamont collectively added more than 100,000 tpa of fermentation output between 2024 and 2026. Local demand tilts toward high-value TPU, PBT, and pharmaceutical intermediates, giving producers a margin buffer against feedstock volatility.
Saudi Arabia's Sipchem operates a 50,000 tpa unit integrated with low-cost ethane, targeting polyurethane and solvent markets. Brazil drives South American consumption across automotive and textile channels, yet logistical and currency hurdles slow new investment. Africa's demand is nascent, centered in South African polyurethane coatings, but infrastructure gaps remain a hurdle.
- Ashland
- BASF
- Chang Chun Group
- CJ CHEILJEDANG CORP.
- DCC
- Genomatica, Inc.
- Grupa Azoty
- Henan Kaixiang Fine Chemical Co. Ltd
- Jiangsu Hailun Petrochemical Co. Ltd
- LyondellBasell Industries Holdings B.V.
- Markor Chemicals Group Co. Ltd
- Mitsubishi Chemical Group Corporation
- NAN YA PLASTICS CORPORATION
- Novamont SpA
- Shandong Yuanli Science And Technology Co. Ltd
- Shanxi Sanwei Group Co. Ltd
- Sinochem Internation Corporation
- Sipchem Company
- SK Geocentric Co., Ltd.
- Xinjiang Blue Ridge Tunhe Sci.&Tech. Co., Ltd.
- Xinjiang Tianye (Group) Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for THF and spandex fibres
- 4.2.2 Light-weighting of EV connectors spurring PBT uptake
- 4.2.3 Expansion of polyurethane applications
- 4.2.4 Government subsidies for bio-BDO capacity
- 4.2.5 Cost-advantaged coal-to-acetylene integrations in inland China
- 4.3 Market Restraints
- 4.3.1 Occupational health and safety concerns
- 4.3.2 Volatile feedstock (acetylene, butadiene, propylene) prices
- 4.3.3 Carbon-border taxes raising cost of coal-based BDO exports
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Production Process
- 5.1.1 Reppe Process
- 5.1.2 Davy Process
- 5.1.3 Butadiene-Based Process
- 5.1.4 Propylene Oxide-Based Process
- 5.1.5 Bio-fermentation Route
- 5.2 By Derivative
- 5.2.1 Tetrahydrofuran (THF)
- 5.2.2 Polybutylene Terephthalate (PBT)
- 5.2.3 Gamma-Butyrolactone (GBL)
- 5.2.4 Polyurethane (PU)
- 5.2.5 Other Derivatives
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Textile
- 5.3.3 Electrical and Electronics
- 5.3.4 Healthcare and Pharmaceuticals
- 5.3.5 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information,Products and Services, and Recent Developments)}
- 6.4.1 Ashland
- 6.4.2 BASF
- 6.4.3 Chang Chun Group
- 6.4.4 CJ CHEILJEDANG CORP.
- 6.4.5 DCC
- 6.4.6 Genomatica, Inc.
- 6.4.7 Grupa Azoty
- 6.4.8 Henan Kaixiang Fine Chemical Co. Ltd
- 6.4.9 Jiangsu Hailun Petrochemical Co. Ltd
- 6.4.10 LyondellBasell Industries Holdings B.V.
- 6.4.11 Markor Chemicals Group Co. Ltd
- 6.4.12 Mitsubishi Chemical Group Corporation
- 6.4.13 NAN YA PLASTICS CORPORATION
- 6.4.14 Novamont SpA
- 6.4.15 Shandong Yuanli Science And Technology Co. Ltd
- 6.4.16 Shanxi Sanwei Group Co. Ltd
- 6.4.17 Sinochem Internation Corporation
- 6.4.18 Sipchem Company
- 6.4.19 SK Geocentric Co., Ltd.
- 6.4.20 Xinjiang Blue Ridge Tunhe Sci.&Tech. Co., Ltd.
- 6.4.21 Xinjiang Tianye (Group) Co. Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Advancements in Bio-Based Production Technologies