|
시장보고서
상품코드
2123058
바이오 유래 1,4-부탄디올 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Bio-based 1,4-Butanediol - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
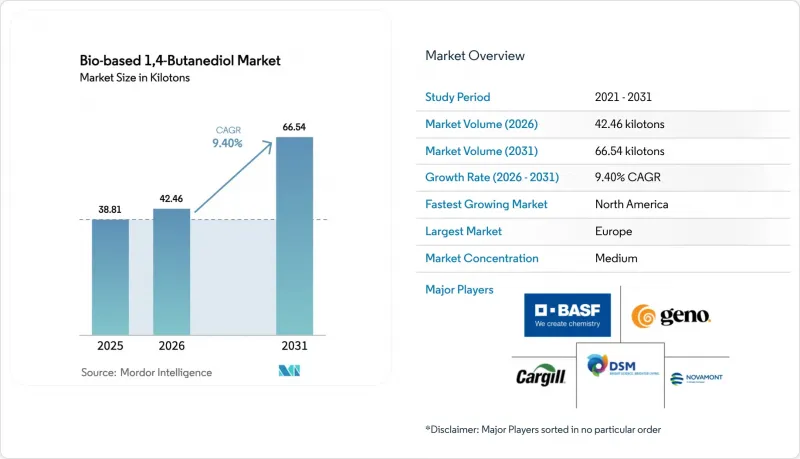
에 의하면, 바이오 유래 1,4-부탄디올 시장 규모는 2025년에 38.81 킬로톤, 2026년에는 42.46 킬로톤이 되어, 2031년까지 66.54 킬로톤에 이른다고 전망되고 있어 2026년부터 2031년까지 CAGR 9.40%를 나타낼 것으로 예측됩니다.
본 보고서는 용도별(테트라하이드로푸란(THF), 폴리부틸렌 테레프탈레이트(PBT), γ-부티로락톤(GBL) 등), 최종 사용자 산업별(자동차, 전기 및 전자,섬유 및 의류, 산업용 및 기타), 지역별(아시아태평양, 북미, 유럽, 기타 지역)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
전 세계 바이오 유래 1,4-부탄디올 시장 동향 및 인사이트
폴리부틸렌 테레프탈레이트(PBT)에 대한 수요 급증
전기차 아키텍처에서는 150°C를 초과하는 온도를 견딜 수 있는 PBT 소재의 커넥터, 배터리 하우징 및 충전 부품이 요구됩니다. 이 소재는 얇은 두께로 성형이 가능하기 때문에 부품의 무게를 최대 20%까지 줄일 수 있으며, 주행 거리가 중요한 배터리 플랫폼에서는 그 이점이 더욱 큽니다. 바이오 유래 BDO는 드롭인형 전구체로 기능하여, 변환업체는 주요 부품의 재인증 절차 없이도 재생 가능 원료 함유율 인증을 획득할 수 있습니다. BASF의 REDcert2 인증을 받은 바이오물질 수지 BDO는 2024년부터 시판되고 있으며, 내재된 탄소 배출을 줄이면서도 동등한 기계적 성능을 실현합니다. 5G 확산과 데이터센터 건설로 인해 2030년까지 PBT 수요가 연평균 8% 증가할 것으로 예상에 따라, 전자 분야도 성장의 호재로 작용하고 있습니다.
세계 및 지역 차원의 엄격한 탄소 감축 규제
EU의 탄소국경조정메커니즘(CBAM)은 배출량이 많은 수입품에 탄소세를 부과하는 제도로, 2026년에 유기화학제품이 적용 대상에 포함되면 석탄 유래 BDO의 도착 비용이 1톤당 150-200유로 상승하게 됩니다. 캘리포니아주의 저탄소 연료 기준(LCFS) 및 미국의 인플레이션 억제법(IRA)에서는 거래 가능한 크레딧이나 생산세 감면이 제공되어, 대상인 바이오 BDO의 생산 비용을 1Kg당 0.20-0.30달러 절감합니다. 2060년까지 탄소 중립을 목표로 하는 중국의 ‘이산화탄소 배출 정점 달성 및 탄소 중립’ 전략에서는 석탄 유래 BDO 신규 설비 인가를 제한하고, 바이오 유래 제조 경로를 우선시하고 있습니다. 또한, RED II에 따라 유럽에서는 재생 가능 연료 첨가제로서의 THF 수요가 증가하고 있습니다.
원유 가격 변동에 따른 화석 유래 BDO와의 가격 차이
바이오 BDO 가격은 포도당이나 자당의 원가에 연동되어 있어 수확 부진 시 이러한 원가가 급등하지만, 반면 화석 유래 BDO는 나프타나 천연가스의 가격 주기에 좌우됩니다. 2024년 말 원유 가격이 배럴당 70달러 아래로 떨어졌을 때, 바이오 BDO의 프리미엄은 25%까지 확대되었습니다. 중국의 석탄 유래 BDO는 1kg당 1.60-1.80달러에 판매되어 바이오 유래 대체품보다 최대 30% 저렴했기 때문에 지속가능성 조항이 없는 가공업체에 압박을 가했습니다.
부문별 분석
테트라하이드로푸란(THF)은 2025년 판매량의 48.40%를 차지하며, 애슬레저 및 속옷 분야의 스판덱스 수요 호조에 힘입어 2031년까지 연평균 성장률(CAGR) 9.62%를 기록할 전망입니다. Qore의 바이오 BDO를 사용한 스판덱스의 출시로 탄소 발자국이 44% 감소함에 따라, THF는 바이오 유래 1,4-부탄디올 시장의 주요 용도로 자리 잡았습니다. 그 다음으로 PBT 용도가 꼽히며, 이는 전기차용 커넥터 수요와 2030년까지 8% 증가할 것으로 예상되는 자동차용 PBT 수요에 힘입고 있습니다. 감마-부티로락톤은 특수 용제를 뒷받침하는 한편, 폴리우레탄 엘라스토머는 친환경 건축 및 저VOC 추세를 반영하고 있습니다. 효성TNC의 베트남 복합 단지 같은 수직 통합 프로젝트는 자사 수요를 통해 PTMEG 수요를 확보하고, 원료 가격 변동으로부터 THF 공급망을 보호하는 동시에, 2026년 중반까지 5만 톤 규모의 스판덱스 생산 능력에 해당하는 물량 확보를 확정지었습니다.
두 번째 용도 분야는 여전히 틈새 시장이지만 수익성이 높습니다. GBL은 농약 중간체의 원료로 사용되며, 규제 당국의 승인에 있어 검증된 바이오 유래 경로가 우선시되고 있습니다. PU(폴리우레탄)가 경질 단열재 분야로 진출함에 따라 시장 범위가 확대되고 있습니다. 이러한 다양한 판매 경로가 결합되어, 바이오 유래 1,4-부탄디올 시장은 단일 산업의 경기 침체에 대한 내성을 강화하고, 공급업체가 다년간의 계약을 통해 생산 포트폴리오의 균형을 맞추는 데 기여하고 있습니다.
지역별 분석
2025년, 유럽은 전 세계 생산량의 75.01%를 차지했습니다. 이는 BASF의 REDcert2 인증을 획득한 바이오물질 수지 BDO와 Novamont의 전용 30킬로톤 규모 공장에 힘입은 결과입니다. 탄소 국경 조정 메커니즘(CBAM)에 따라 2026년 이후 수입되는 화석 유래 BDO의 비용은 톤당 150-200유로 상승하여, 사실상 해당 지역의 바이오 유래 생산을 지원하게 될 것입니다. 독일, 영국, 프랑스, 이탈리아는 자동차용 PBT 소비와 대규모 섬유 가공 거점에 힘입어 유럽 수요의 60% 이상을 차지하고 있습니다. 북유럽 국가들에서는 임업 잔여물을 원료로 활용하는 노력이 진행되고 있는 반면, 튀르키예의 수출 지향형 섬유 부문에서는 EU 브랜드의 사양을 충족하기 위해 바이오 PTMEG에 대한 수요가 발생하고 있습니다.
북미는 2026년부터 2031년까지 연평균 성장률(CAGR) 9.87%를 기록하며 가장 빠른 성장 궤도를 그리고 있습니다. 아이오와주에 위치한 Qore의 65킬로톤 규모 시설은 2026년부터 상업적 규모의 출하를 시작하여, 미국 내 LYCRA의 스판덱스 생산 라인에 원료를 공급할 예정입니다. ‘인플레이션 억제법(Inflation Reduction Act)’에 따른 인센티브로 바이오 BDO의 현금 비용이 낮아지면서 새로운 발효 프로젝트가 유치되고 있습니다. 캘리포니아주의 LCFS 크레딧과 캐나다의 청정 연료 규제는 연료 첨가제용 THF 분자 생산을 뒷받침하고 있습니다. 멕시코의 자동차 생산 거점은 바이오 PBT를 주도하며, 국경을 초월한 공급망을 통합함으로써 지역 성장을 뒷받침하고 있습니다.
아시아태평양은 전 세계 생산 능력의 대부분을 차지하고 있으며, 중국의 생산자들은 옥수수 및 카사바 원료를 경쟁력 있는 비용으로 활용하고 있습니다. Hyosung TNC의 10억 달러 규모 베트남 공장 건설은 자사 수요를 확보하고 공급 위험을 줄여줍니다. 일본의 대기업인 도레이와 미쓰비시는 보다 광범위한 폴리에스터 및 나일론 사업으로 통합될 셀룰로오스계 당 제조 경로를 추진하고 있습니다. 한국의 LG화학은 자동차 및 전자 분야를 위한 바이오 BDO를 포지셔닝하고 있으며, 동남아시아의 섬유 산업 클러스터는 유럽 및 미국 브랜드 수요를 충족하기 위해 재생 가능한 PTMEG를 조달하고 있습니다. 세계 기타 지역은 수입에 의존하고 있지만, 수출 경쟁력을 유지하기 위해 저탄소 원료가 필요한 중동 및 남미의 섬유 산업이 확대됨에 따라 성장의 조짐이 보이고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.09According to Mordor Intelligence, the bio-based 1,4-Butanediol market size is projected to be 38.81 kilotons in 2025, 42.46 kilotons in 2026, and reach 66.54 kilotons by 2031, growing at a CAGR of 9.40% from 2026 to 2031.
This report is Segmented by Application (Tetrahydrofuran (THF), Polybutylene Terephthalate (PBT) Gamma-Butyrolactone (GBL), and More), End-User Industry (Automotive, Electrical and Electronics, Textile and Apparel, and Industrial and Others), and Geography (Asia-Pacific, North America, Europe, and Rest of the World). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Bio-based 1,4-Butanediol Market Trends and Insights
Surging Demand for Polybutylene Terephthalate (PBT)
Electric-vehicle architectures require PBT connectors, battery housings, and charging components able to endure temperatures above 150 °C. The material's thin-wall moldability drops part weight by up to 20%, a benefit amplified in range-sensitive battery platforms. Bio-based BDO acts as a drop-in precursor, letting converters certify renewable content without requalifying critical parts. BASF's REDcert2-approved biomass-balance BDO, commercial since 2024, enables identical mechanical performance while trimming embedded carbon. The electronics sector adds upside as 5G rollouts and data-center buildouts fuel 8% annual PBT demand growth to 2030.
Stringent Global and Regional Carbon-Reduction Mandates
The EU Carbon Border Adjustment Mechanism levies carbon fees on high-emission imports, raising the landed cost of coal-derived BDO by EUR 150-200 per ton once organic chemicals join the scope in 2026. California's Low Carbon Fuel Standard and U.S. Inflation Reduction Act award tradable credits and production tax relief that shave USD 0.20-0.30 per kilogram from qualifying bio-BDO output. China's dual-carbon pathway, aiming for neutrality by 2060, curtails approvals for new coal-based BDO units while prioritizing bio-routes, and RED II lifts demand for THF as a renewable fuel additive in Europe.
Price Gap Versus Fossil BDO Amid Crude Volatility
Bio-BDO tracks glucose and sucrose costs, which surge during poor harvests, while fossil peers ride naphtha and natural-gas cycles. When crude slipped below USD 70 per barrel in late 2024, bio premiums widened to 25%. Chinese coal-based BDO sold at USD 1.60-1.80 per kilogram, undercutting bio alternatives by up to 30%, pressuring converters lacking sustainability clauses.
Other drivers and restraints analyzed in the detailed report include:
- Brand-Owner Net-Zero Commitments Across CPG and Automotive
- Rapid Cost Declines in Bio-Fermentation Technologies
- Limited Large-Scale Fermentation Capacity Outside Asia-Pacific
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Tetrahydrofuran (THF) secured 48.40% of 2025 volume and is on track for a 9.62% CAGR through 2031, buoyed by brisk spandex demand in athleisure and intimate apparel. The spandex launch using Qore's bio-BDO cut carbon footprints by 44%, turning THF into the flagship application within the bio-based 1,4-butanediol market. PBT applications follow, driven by electric-vehicle connector needs and a predicted 8% rise in automotive PBT demand to 2030. Gamma-butyrolactone supports specialty solvents, while polyurethane elastomers tap into green-building and low-VOC trends. Vertical integration projects such as Hyosung TNC's Vietnam complex secure captive PTMEG demand, insulating THF supply chains from feedstock volatility and locking in offtake for 50,000 tons of spandex capacity by mid-2026.
Second-tier applications remain niche yet profitable. GBL feeds agrochemical intermediates where regulatory approvals favor validated bio routes. PU's move into rigid insulation broadens market scope. These diverse outlets collectively reinforce the bio-based 1,4-butanediol market's resilience against single-industry downturns and help suppliers balance production portfolios over multi-year contracts.
Complete Report Scope:
- By Application
- Tetrahydrofuran (THF)
- Polybutylene Terephthalate (PBT)
- Gamma-Butyrolactone (GBL)
- Polyurethane (PU)
- Other Applications
- By End-user Industry
- Automotive
- Electrical & Electronics
- Textile and Apparel
- Industrial and Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Nordic Countries
- Turkey
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Indonesia
- Malaysia
- Thailand
- Vietnam
- Rest of Asia-Pacific
- Rest of the World
- Middle-East and Africa
- South America
- North America
Geography Analysis
Europe held 75.01% of global volume in 2025, underpinned by BASF's REDcert2-approved biomass-balance BDO and Novamont's dedicated 30-kiloton plant. The Carbon Border Adjustment Mechanism lifts imported fossil BDO costs by EUR 150-200 per ton from 2026, effectively subsidizing regional bio output. Germany, the United Kingdom, France, and Italy contribute more than 60% of European demand, driven by automotive PBT consumption and a large textile converting base. Nordic initiatives exploit forestry residues as feedstock, while Turkey's export-oriented textile sector draws bio-PTMEG to meet EU brand specifications.
North America posts the fastest 2026-2031 trajectory at 9.87% CAGR. Qore's 65-kiloton Iowa facility ships commercial volumes from 2026, feeding LYCRA's U.S. spandex lines. Inflation Reduction Act incentives drop bio-BDO cash costs and attract new fermentation proposals. California's LCFS credits and Canada's Clean Fuel Regulations spur THF molecules for fuel additives. Mexico's vehicle production hub pulls bio-PBT, integrating cross-border supply chains and undergirding regional growth.
Asia-Pacific commands the bulk of global capacity, with Chinese producers leveraging corn and cassava streams at competitive cost. Hyosung TNC's USD 1 billion Vietnam build secures captive demand and lowers supply risk. Japanese majors Toray and Mitsubishi advance cellulosic sugar routes that integrate into wider polyester and nylon programs. South Korea's LG Chem positions bio-BDO for automotive and electronics accounts, and Southeast Asian textile clusters source renewable PTMEG to satisfy Western brands. The rest of the world leans on imports, yet growth pockets appear in Middle Eastern and South American textile expansions that require low-carbon feedstocks to preserve export competitiveness.
- BASF
- DSM
- Genomatica Inc.
- Cargill, Incorporated
- Novamont S.p.A.
- Global Bio-chem Technology Group Co. Ltd.
- Shandong Landian Biological Technology Co. Ltd
- Yuanli Science & Technology
- Toray Industries
- Mitsubishi Chemical Group
- Susteen Technologies
- Dairen Chemical Corporation
- LanzaTech Global
- Green Biologics Ltd.
- Asahi Kasei Corporation
- Corbion N.V.
- Lanxess AG
- LG Chem
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for polybutylene terephthalate (PBT)
- 4.2.2 Stringent global and regional carbon-reduction mandates
- 4.2.3 Brand owners' net-zero commitments across CPG and automotive
- 4.2.4 Rapid cost declines in bio-fermentation technologies
- 4.2.5 Commercialisation of lignocellulosic feedstocks (non-food)
- 4.3 Market Restraints
- 4.3.1 Price gap vs. fossil BDO amid crude volatility
- 4.3.2 Limited large-scale fermentation capacity outside Asia-Pacific
- 4.3.3 Strain IP litigation slowing tech-transfer deals
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Patent Analysis
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Application
- 5.1.1 Tetrahydrofuran (THF)
- 5.1.2 Polybutylene Terephthalate (PBT)
- 5.1.3 Gamma-Butyrolactone (GBL)
- 5.1.4 Polyurethane (PU)
- 5.1.5 Other Applications
- 5.2 By End-user Industry
- 5.2.1 Automotive
- 5.2.2 Electrical & Electronics
- 5.2.3 Textile and Apparel
- 5.2.4 Industrial and Others
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Russia
- 5.3.2.7 Nordic Countries
- 5.3.2.8 Turkey
- 5.3.2.9 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 South Korea
- 5.3.3.5 Indonesia
- 5.3.3.6 Malaysia
- 5.3.3.7 Thailand
- 5.3.3.8 Vietnam
- 5.3.3.9 Rest of Asia-Pacific
- 5.3.4 Rest of the World
- 5.3.4.1 Middle-East and Africa
- 5.3.4.2 South America
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 BASF
- 6.4.2 DSM
- 6.4.3 Genomatica Inc.
- 6.4.4 Cargill, Incorporated
- 6.4.5 Novamont S.p.A.
- 6.4.6 Global Bio-chem Technology Group Co. Ltd.
- 6.4.7 Shandong Landian Biological Technology Co. Ltd
- 6.4.8 Yuanli Science & Technology
- 6.4.9 Toray Industries
- 6.4.10 Mitsubishi Chemical Group
- 6.4.11 Susteen Technologies
- 6.4.12 Dairen Chemical Corporation
- 6.4.13 LanzaTech Global
- 6.4.14 Green Biologics Ltd.
- 6.4.15 Asahi Kasei Corporation
- 6.4.16 Corbion N.V.
- 6.4.17 Lanxess AG
- 6.4.18 LG Chem
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment