

|
시장보고서
상품코드
2121367
증발 냉각 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Evaporative Cooling - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
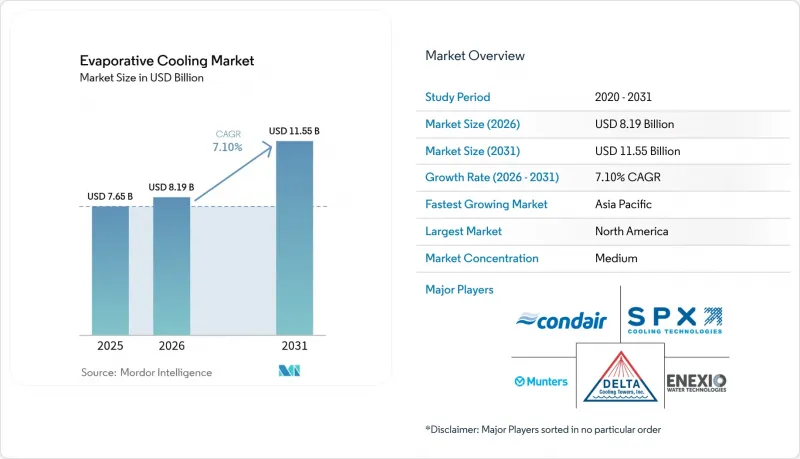
에 따르면 증발 냉각 시장 규모는 2025년 76억 5,000만 달러에서 2026년에는 81억 9,000만 달러로 확대되고, 2026년부터 2031년까지 CAGR 7.10%를 기록하며 2031년에는 115억 5,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 냉각 방식(직접식 증발 냉각, 간접식 증발 냉각 등), 용도(주거용, 상업 시설 등), 냉각 용량(CFM)(5,000 CFM 이하, 그 이상), 구성요소(냉각 패드, 팬·송풍기 등), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 증발 냉각 시장의 동향 및 인사이트
높은 비용 대비 효과로 산업 분야 도입 촉진
미국의 건조한 주에 위치한 제조 공장에서는 기계식 냉동 시스템에 비해 운영비가 60-80% 저렴하며, 전기 요금 상승에 따라 2년 이내에 투자 회수가 가능합니다. 일반적으로 습구 온도가 78°F 미만인 조건에서는 냉수 시스템의 10분의 1에 해당하는 전력으로 기온을 15-20°F 낮출 수 있습니다. 텍사스주와 애리조나주의 양계장에서는 열 스트레스로 인한 사망률이 25% 감소하고 냉각 비용이 70% 절감된 것으로 보고되고 있습니다.
데이터센터는 PUE 최적화를 위해 증발 냉각을 도입
하이퍼스케일 사업자는 간접식·2단계식 설계를 채택함으로써 PUE를 1.06까지 낮추었으며, 이는 기존 평균치인 1.4-1.6을 크게 상회하는 수치입니다. EU의 에너지 효율 지침에서는 IT 부하가 500kW를 초과하는 시설에 대해 2025년까지 폐열 회수를 의무화하고 있으며, 증발 냉각 기술은 해당 지침을 준수할 수 있게 해주는 수단으로 자리매김하고 있습니다. 마이크로소프트의 애리조나 캠퍼스에서는 최종 단열 공조 전에 흡기 공기를 예냉함으로써 사막 기후에서도 연중 운영이 가능함을 입증하고 있습니다.
기후에 대한 의존도가 지리적 확장을 제한
주변 습도가 60%를 초과하면 효율이 50% 미만으로 떨어지기 때문에 열대 지역에서의 단독 도입은 제한됩니다. 미국 남동부 시설에서는 계절에 따른 성능 변동이 보고되고 있으며, 하이브리드형 HVAC 도입이 필요하기 때문에 초기 투자 비용이 30-40% 증가하고 있습니다. 각 제조사는 2단계 방식이나 흡습제 보조형 등 다양한 방식으로 대응하고 있지만, 여전히 높은 비용이 중소규모 상업 구매자의 도입을 가로막고 있습니다.
부문 분석
2025년에는 설치 비용이 3,000-8,000달러로 저렴하기 때문에 직접식 증발 냉각 설계가 매출의 66.20%를 차지했습니다. 한편, 2단계식 솔루션은 주변 습도가 75%까지 올라가도 쾌적한 송풍을 유지할 수 있어 연평균 성장률(CAGR) 7.72%를 기록할 것으로 예측됩니다. 혼합 습윤 기후에 위치한 데이터센터와 학교가 쾌적성을 해치지 않으면서 효율성을 우선시함에 따라, 2단계식 유닛의 증발 냉각 시장 규모는 2031년까지 2배로 증가할 것으로 예측됩니다. 각 제조사는 설치된 직접식 유닛을 2단계식 구성으로 전환하는 모듈식 업그레이드를 제공함으로써 위험을 분산하고, 습도 요건이 변화할 때까지 막대한 설비 투자를 미루고 있습니다.
대형 소매점이나 물류 센터에 설치되는 패키지형 옥상 유닛 내에서는 간접식 증발 냉각 모듈에 대한 수요가 증가하고 있습니다. 에어사이드 이코노마이저는 차가운 외부 공기를 공조 공간과 전혀 접촉하지 않는 폴리머 재질의 열교환기를 통과시킴으로써 실내 공기질을 보호하면서 프리 쿨링 시간을 확보합니다. 각 통합 업체들은 레지오넬라균에 대한 우려를 해소하기 위해 자외선 램프와 항균 코팅을 결합하여, 기존 덕트에 통합할 수 있는 턴키 키트를 제조하고 있습니다. 그 결과, 증발 냉각 시장에서는 기존의 패드와 신기술인 폴리머 막 및 고표면적 히트 파이프 간의 융합이 지속적으로 진행되고 있습니다.
주거용 설치는 2025년 매출의 71.05%를 차지하고 있으며, 이는 미국 선벨트 지역과 호주에서의 광범위한 도입에 기인합니다. 전력 소비량이 적기 때문에 주택 소유자는 옥상 태양광발전으로 전력 수요를 상쇄할 수 있으며, 500-2,000달러에 달하는 전력 회사의 인센티브를 통해 실질 비용이 더욱 절감됩니다. 그럼에도 불구하고, 하이퍼스케일 클라우드 사업자가 신규 용량의 대부분을 늘릴 것으로 예상되어 이 부문은 연평균 성장률(CAGR) 9.05%로 확대될 전망입니다. PUE(전력 사용 효율) 보고 및 폐열 재사용을 의무화하는 관할 구역이 늘어남에 따라, 데이터센터에서 증발 냉각의 시장 점유율은 급격히 상승할 것으로 예상됩니다.
상업 시설에서는 지붕 설치형 증발식 프리쿨러를 도입하여 압축기 가동 시간을 단축하고, 1kWh당 0.35달러에 달할 수도 있는 피크 수요 요금을 피하고 있습니다. 양계장이나 온실에서는 동물 복지 및 작물 보호를 목적으로 증발 냉각 패드가 도입되고 있으며, 폭염 시 사망률이 25% 감소하고 수확량이 15% 향상되는 것으로 확인되었습니다. 이러한 산업 전반에 걸친 범용성 덕분에 증발 냉각 업계는 주택 건설 경기 변동의 영향을 덜 받게 되었습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 38.20%를 차지했으며, 그 중심은 미국 남서부였습니다. 이 지역에서는 낮 동안의 습구 온도가 높기 때문에 증발 냉각이 가장 경제적인 선택지입니다. 캘리포니아주의 ‘타이틀 24’ 에너지 규제에서는 압축기 용량을 줄이는 데 따른 준수 크레딧이 할당되어 있어, 이를 통해 증발 냉각 시장이 사실상 지원받고 있습니다. 네바다주와 애리조나주의 전력 회사가 운영하는 인센티브 프로그램에서는 주택 1채당 설치 시 최대 2,000달러의 환급이 이루어지고 있어, 주택 담보 대출 금리가 높은 상황에서도 수요를 뒷받침하고 있습니다. 그러나 장기화되는 가뭄으로 인해 정책은 여전히 유동적인 상태입니다. 2022년부터 2023년에 걸친 물 부족 사태 당시, 일부 전력 회사는 리베이트 지급을 일시 중단하고 물 재순환 설계 및 대체 수원의 필요성을 시사했습니다.
아시아태평양은 연평균 성장률(CAGR) 8.10%로 가장 빠르게 성장하는 지역이 될 것으로 예측되며, 이 지역의 증발 냉각 시장 규모는 2031년까지 2배로 커질 것으로 전망됩니다. 사우디아라비아의 NEOM 프로젝트만 해도, 계획 중인 주택의 80%에 대해 건축 기준상 단열 공조가 의무화되어 있어, 평생에 걸쳐 20억 달러 규모의 비즈니스 기회가 예상됩니다. 호주에서는 가속 감가상각 제도가 도입되었으며, 인도 그린 빌딩 협의회(IGBC)는 IGBC 평가 기준에서 증발식 예냉 포인트를 인증하기 시작했습니다. 급속한 도시화와 전력 예비력의 부족으로 인해 저에너지 HVAC가 필수적이며, 각 주 정부는 물 재사용 패드 및 처리된 폐수 순환 시스템을 검토해야 하는 상황에 직면해 있습니다.
유럽에서는 그 추진력에 차이가 보입니다. 북부 기후대에서는 아일랜드와 북유럽 국가들의 데이터센터에 간접식 증발 이코노마이저가 도입되어, 연간 80%의 기간 동안 시원한 외부 공기를 이용하여 프리 쿨링을 실현하고 있습니다. 남유럽은 습도가 높아 도입 속도가 더딘 편이지만, 스페인의 물류 단지에서는 상대 습도 60%의 환경에서도 공급 온도를 75°F 이하로 유지하도록 보장하는 2단계 시스템이 도입되었습니다. 중동에서는 수자원이 부족한 상황임에도 불구하고 고효율 패드와 염수 내성 소재의 도입이 진행되고 있습니다. 남미는 여전히 발전 단계에 있지만 미래가 기대되며, 특히 브라질에서는 자동차 도장 부스에서 단열식 냉각기를 채택하여 에너지 소비를 70% 절감하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the evaporative cooling market size is expected to grow from USD 7.65 billion in 2025 to USD 8.19 billion in 2026 and is forecast to reach USD 11.55 billion by 2031 at 7.10% CAGR over 2026-2031.
This report is Segmented by Cooling Principle (Direct Evaporative Cooling, Indirect Evaporative Cooling, and More), Application (Residential Buildings, Commercial Buildings, and More), Cooling Capacity - CFM ( Less Than or Equal To 5, 000 CFM, and More), Component (Cooling Pads, Fans and Blowers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Evaporative Cooling Market Trends and Insights
Cost-Effectiveness Drives Industrial Adoption
Manufacturing plants in dry U.S. states report operating expenses that are 60-80% lower than those of mechanical refrigeration, with capital recovery inside two years as electricity tariffs climb. Typical wet-bulb conditions below 78 °F enable 15-20 °F air temperature reductions using one-tenth the power of chilled-water systems. Texas and Arizona poultry farms cite 25% lower heat-stress mortality alongside 70% savings on cooling bills.
Data Centers Embrace Evaporative Cooling for PUE Optimization
Hyperscale operators use indirect and two-stage designs to achieve PUE as low as 1.06, far outperforming traditional averages of 1.4-1.6. The EU Energy Efficiency Directive obliges facilities above 500 kW IT load to recover waste heat by 2025, positioning evaporative technology as a compliance enabler. Microsoft's Arizona campus proves all-year viability even in desert climates by pre-cooling intake air before final adiabatic conditioning.
Climate Dependence Limits Geographic Expansion
Efficiency drops below 50% when ambient humidity rises beyond 60%, limiting standalone adoption in tropical belts. Southeastern U.S. facilities report seasonal performance swings that necessitate hybrid HVAC, boosting upfront spending by 30-40%. Manufacturers respond with two-stage and desiccant-assisted variants, yet cost premiums still deter small commercial buyers.
Other drivers and restraints analyzed in the detailed report include:
- Construction Boom in Arid Regions Fuels Demand
- Environmental Regulations Accelerate Low-GWP Adoption
- Water Scarcity Challenges Adoption in Arid Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Direct evaporative designs retained 66.20% of revenue in 2025 because of low installed cost between USD 3,000 and USD 8,000. Yet two-stage solutions are forecast to deliver a 7.72% CAGR as they sustain comfortable supply air at ambient humidity up to 75%. The evaporative cooling market size for two-stage units is projected to double by 2031 as data centers and schools in mixed-humid climates prioritize efficiency without sacrificing comfort. Manufacturers hedge risk by offering modular upgrades that convert installed direct units into two-stage configurations, deferring large capital outlays until humidity demands change.
Demand for indirect evaporative modules grows inside packaged rooftop units that serve big-box retail and logistics centers. Air-side economizers route cool outdoor air through polymer heat exchangers that never contact conditioned space, protecting indoor air quality while capturing free cooling hours. Integrators bundle ultraviolet lamps and antimicrobial coatings to address Legionella fears, assembling turnkey kits that slot into existing ductwork. As a result, the evaporative cooling market continues to blend traditional pads with emerging polymer membranes and high-surface-area heat pipes.
Residential installations hold 71.05% of 2025 revenue, a legacy of widespread adoption across U.S. Sunbelt states and Australia. Low energy draw lets homeowners offset power needs with rooftop solar, and utility incentives of USD 500-2,000 cut net cost further. Still, hyperscale cloud operators will add the most new capacity, with the segment advancing at a 9.05% CAGR. The evaporative cooling market share for data centers is expected to rise sharply as more jurisdictions require PUE reporting and waste-heat reuse.
Commercial properties deploy roof-mounted evaporative pre-coolers to trim compressor runtime and dodge peak-demand tariffs that can reach USD 0.35 per kWh. Poultry houses and greenhouses integrate pads for animal welfare and crop protection, noting 25% mortality reductions and 15% yield gains during extreme heat. Such cross-sector versatility shields the evaporative cooling industry from cyclical swings in residential construction.
Complete Report Scope:
- By Cooling Principle
- Direct Evaporative Cooling
- Indirect Evaporative Cooling
- Two-stage Evaporative Cooling
- By Application
- Residential Buildings
- Commercial Buildings
- Industrial Facilities
- Confinement Farming
- Data Centers
- By Cooling Capacity - CFM
- less than or equal to 5,000 CFM
- 5,001-15,000 CFM
- above 15,000 CFM
- By Component
- Cooling Pads
- Fans and Blowers
- Water Pumps
- Control Systems and Sensors
- Other Components
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 38.20% of global revenue in 2025, anchored by the United States Southwest where daytime wet-bulb temperatures make evaporative cooling the most economical choice. Title 24 energy codes in California assign compliance credits that reduce compressor capacity, effectively subsidizing the evaporative cooling market. Incentive programs from Nevada and Arizona utilities reimburse up to USD 2,000 per residential install, sustaining demand amid high mortgage rates. Yet prolonged drought keeps policy fluid. During 2022-2023 shortages some utilities paused rebates, signaling a need for recirculating designs and alternative water sources.
Asia-Pacific is forecast to be the fastest-growing cluster at an 8.10% CAGR, and its evaporative cooling market size is projected to double by 2031. Saudi Arabia's NEOM alone represents a USD 2 billion lifetime opportunity as codes demand adiabatic conditioning for 80% of planned homes. Australia offers accelerated depreciation, while India's green-building council now recognizes evaporative pre-cooling points under its IGBC rating. Rapid urbanization and tight power reserves make low-energy HVAC essential, pushing state governments to explore water-recycling pads and treated wastewater loops.
Europe shows mixed momentum. Northern climates deploy indirect evaporative economizers in data centers across Ireland and the Nordics, leveraging cool ambient air for free cooling 80% of the year. Southern Europe is slower due to higher humidity, but Spain's logistics parks integrate two-stage systems that guarantee supply temperatures under 75 °F even at 60% relative humidity. The Middle East, despite water scarcity, moves ahead with high-efficiency pads and brackish-water tolerant materials. South America remains nascent but promising, led by Brazil where automotive paint booths adopt adiabatic coolers to save 70% on energy.
- Baltimore Aircoil Company Inc.
- SPX Cooling Technologies Inc.
- Delta Cooling Towers Inc.
- Condair Group AG
- Munters Group AB
- Seeley International Pty Ltd
- Symphony Limited
- Portacool LLC
- Phoenix Manufacturing Inc.
- Honeywell International Inc. (Honeywell Comfort)
- Colt Group Limited
- Cambridge Air Solutions Inc.
- Frigiking - Nortek Global HVAC LLC
- Bonaire - Climate Technologies Pty Ltd
- Hessaire Products Inc.
- Airgroup Australia Pty Ltd (Coolair)
- Oasis Coolers LLC
- Swiss Evaporative Systems AG
- Celsius Design Limited
- CFW Evapcool (CFW Industries Ltd.)
- ENEXIO Water Technologies GmbH
- Temperzone Ltd.
- SPIG S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for cost-effective cooling solutions
- 4.2.2 Data-center adoption for energy efficiency
- 4.2.3 Booming construction in arid regions
- 4.2.4 Environmental regulations favoring low-GWP cooling
- 4.2.5 Integration with off-grid solar-hybrid HVAC
- 4.2.6 Water-recapture pads cutting consumptive use
- 4.3 Market Restraints
- 4.3.1 Dependence on external climate conditions
- 4.3.2 High water footprint in water-stressed zones
- 4.3.3 Legionella and microbial health concerns
- 4.3.4 Sensor interoperability issues in smart buildings
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Evaporative-Cooling Hotspot Analysis
- 4.9 Comparative Analysis of Alternative/Substitute Cooling Technologies
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cooling Principle
- 5.1.1 Direct Evaporative Cooling
- 5.1.2 Indirect Evaporative Cooling
- 5.1.3 Two-stage Evaporative Cooling
- 5.2 By Application
- 5.2.1 Residential Buildings
- 5.2.2 Commercial Buildings
- 5.2.3 Industrial Facilities
- 5.2.4 Confinement Farming
- 5.2.5 Data Centers
- 5.3 By Cooling Capacity - CFM
- 5.3.1 less than or equal to 5,000 CFM
- 5.3.2 5,001-15,000 CFM
- 5.3.3 above 15,000 CFM
- 5.4 By Component
- 5.4.1 Cooling Pads
- 5.4.2 Fans and Blowers
- 5.4.3 Water Pumps
- 5.4.4 Control Systems and Sensors
- 5.4.5 Other Components
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Baltimore Aircoil Company Inc.
- 6.4.2 SPX Cooling Technologies Inc.
- 6.4.3 Delta Cooling Towers Inc.
- 6.4.4 Condair Group AG
- 6.4.5 Munters Group AB
- 6.4.6 Seeley International Pty Ltd
- 6.4.7 Symphony Limited
- 6.4.8 Portacool LLC
- 6.4.9 Phoenix Manufacturing Inc.
- 6.4.10 Honeywell International Inc. (Honeywell Comfort)
- 6.4.11 Colt Group Limited
- 6.4.12 Cambridge Air Solutions Inc.
- 6.4.13 Frigiking - Nortek Global HVAC LLC
- 6.4.14 Bonaire - Climate Technologies Pty Ltd
- 6.4.15 Hessaire Products Inc.
- 6.4.16 Airgroup Australia Pty Ltd (Coolair)
- 6.4.17 Oasis Coolers LLC
- 6.4.18 Swiss Evaporative Systems AG
- 6.4.19 Celsius Design Limited
- 6.4.20 CFW Evapcool (CFW Industries Ltd.)
- 6.4.21 ENEXIO Water Technologies GmbH
- 6.4.22 Temperzone Ltd.
- 6.4.23 SPIG S.p.A.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


