

|
시장보고서
상품코드
2122479
북미의 증발 냉각 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Evaporative Cooling - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
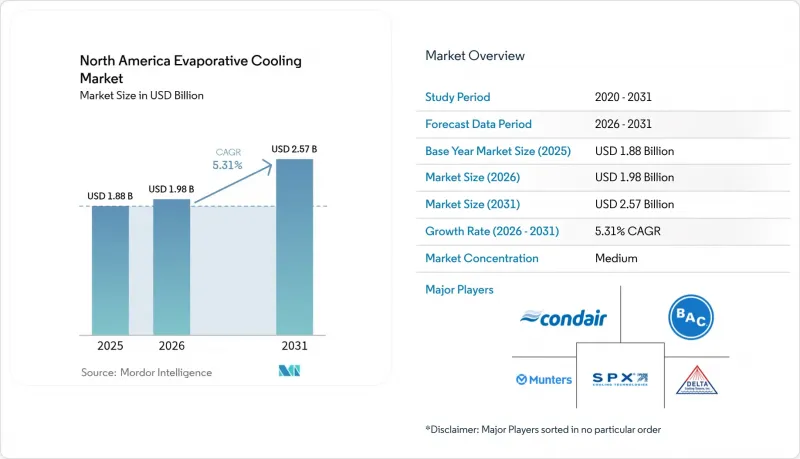
에 의하면, 북미의 증발 냉각 시장 규모는 2025년에 18억 8,000만 달러로 평가되었고, 2026년19억 8,000만 달러에서 2031년까지 25억 7,000만 달러에 이를 것으로 예측되며, 예측 기간(2026년-2031년) CAGR은 5.31%를 기록할 전망입니다.
본 보고서는 냉각 방식(직접식, 간접식, 2단식), 용도(주거용, 상업용, 산업용 등), 구성 부품(기기, 패드 및 미디어 등), 판매 채널(직접 판매, HVAC 계약업체/통합업체,유통·도매, 온라인 소매/전자상거래) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 증발 냉각 시장 동향 및 인사이트
데이터센터의 저 PUE 냉각으로의 전환
하이퍼스케일 사업자들은 응축기 입구 온도를 최대 40°F 낮추는 단열 예냉 모듈을 도입하고 있으며, 이를 통해 300 MW 규모의 캠퍼스에서 최대 14 MW의 IT 부하 전력을 확보하고 있습니다. 마이크로소프트의 폐쇄 루프식 제로 워터 설계와 NREL(국립재생에너지연구소)의 지하 열 에너지 저장 실증 실험은 물 사용량이 제로이며 전력 소비가 적은 아키텍처에 초점을 맞춘 생태계의 중요성을 부각시키고 있습니다. 볼티모어 에어코일(Baltimore Air Coil)이 라이선스를 부여하는 침지형 증발 냉각 타워는 액체 측과 공기 측 솔루션의 융합을 더욱 잘 보여줍니다. AI 워크로드로 인해 랙 밀도가 높아지는 가운데, 간접 및 직접 냉각 단계는 압축기를 통한 압력 상승 없이 더 좁은 열 대역을 실현하고 있으며, 이를 통해 증발 냉각은 디지털 인프라 확장의 핵심으로 자리 잡고 있습니다.
산업 및 상업 분야의 에너지 효율 관련 규제
캘리포니아주의 ‘타이틀 24’는 현재 8,000 MBH를 초과하는 증발 냉각식 커패시터에 대해 350 Btuh/W의 최저 성능 기준을 규정하고 있으며, 습구 온도에 따른 가변 속도 팬의 채택을 의무화하고 있습니다. GWP가 750을 초과하는 냉매를 단계적으로 폐지하는 연방 냉매 규제에 따라, 증발식 배열 장치로 공급 가능한 천연 냉매 시스템의 도입이 가속화되고 있습니다. 캐나다 천연자원부는 미국 기준치를 따르고 있어 국경을 초월한 장비 규격 조화가 가능합니다. 이러한 정책들이 맞물려, 직접 팽창식 칠러에 비해 75%의 에너지 절감 효과를 실현할 수 있는 단열식 또는 하이브리드식 냉각탑을 우대하는 최저 성능 기준이 확립되었습니다.
기후 습도에 대한 의존성
상대 습도가 60%를 초과하면 증발 냉각 효율이 급격히 떨어지기 때문에 미국 남동부 각 주에서는 건조제식과 증발식을 결합한 하이브리드 시스템에 의존할 수밖에 없습니다. 메히카리에서 실시한 시뮬레이션에서는 계절적인 저습도 기간에만 실용성이 확인되었으며, 피크 월에는 백업용 제습이 필요합니다. 이슬점 간접 냉각 단계를 도입함으로써 성능 범위는 확대되지만, 복잡성이 증가함에 따라 북미의 증발 냉각 시장의 우위를 결정짓는 설비 투자(Capex)의 차이가 줄어들고 있습니다.
부문 분석
2025년, 북미의 증발 냉각 시장에서 직접식 유닛은 63.20%의 점유율을 유지했습니다. 이는 건조한 서부 지역 시설에 수십 년간 도입되어 온 사실을 반영합니다. 간접식 타워는 23.70%의 점유율을 차지하고 있으며, 공기와 물의 직접 접촉이 금지된 식품 가공 및 제약 업계에서 선호되고 있습니다. 2단식 간접·직접 설계는 과도한 물 사용량 없이 이슬점 이하의 공기를 공급해야 하는 데이터센터 및 고열 발생 산업의 개보수 공사에 힘입어 5.69%라는 가장 높은 연평균 성장률(CAGR)을 기록했습니다.
천공식 이슬점 열교환기를 통해 간접 냉각 효율이 향상되고, 낮은 압력 손실을 유지하면서 급기 비율을 0.5 미만으로 억제할 수 있게 됨에 따라 성능 격차는 점차 줄어들고 있습니다. 이러한 요소들이 성숙해짐에 따라 설계 및 시공 사양에서 2단식 플랫폼이 1단식을 앞지르고 있으며, 이러한 추세로 인해 2031년까지 북미의 증발 냉각 시장에서 2단식 플랫폼의 점유율이 확대될 것으로 예측됩니다. 현재 각 공급업체들은 화학 약품을 사용하지 않는 수처리 기술과 항균 필름을 통합하고 있으며, 이를 통해 패드의 수명을 연장하고 대규모 캠퍼스 운영자가 직면한 인력 부족이라는 병목 현상을 완화하고 있습니다.
2025년 매출의 36.60%는 산업 플랜트가 차지할 것으로 보이며, 이는 견고한 가동과 에너지 절약을 우선시하는 식품, 화학 및 일반 제조업 수요에 의해 주도된 것입니다. 데이터센터는 규모는 작지만, AI의 보급으로 인해 랙의 열 밀도가 공조식 CRAC 유닛이 처리할 수 있는 범위를 넘어 증가하고 있어 연평균 성장률(CAGR) 5.34%로 성장하고 있습니다. 제어 환경 농업, 온실 및 폐쇄형 농업은 대마초 합법화와 수직 농업의 성장세에 힘입어 연평균 성장률(CAGR) 8.74%로 성장을 지속하고, 있습니다. 이에 따라 증발 냉각 솔루션은 압축기 코일을 대체하는 저에너지 및 습도 조절이 가능한 대안으로 자리매김하고 있습니다.
상업용 건물은 지속가능성 인증과 관련된 소매점 및 사무실 리모델링을 통해 24.30%의 점유율을 차지하고 있지만, 주거 부문에서의 도입은 5.12%라는 완만한 연평균 성장률(CAGR)로 진행되고 있으며, 그 범위는 주로 건조한 기후 지역에 국한되어 있습니다. 농업 분야의 도입은 생산자들이 고가의 제습 휠을 사용하지 않고도 작물의 증산 프로파일을 보호할 수 있는 저탄소·저수자원형 HVAC를 추구함에 따라, 2031년까지 북미의 증발 냉각 시장 점유율을 10.5% 이상으로 끌어올릴 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.03According to Mordor Intelligence, the North America evaporative cooling market size was valued at USD 1.88 billion in 2025 and estimated to grow from USD 1.98 billion in 2026 to reach USD 2.57 billion by 2031, at a CAGR of 5.31% during the forecast period (2026-2031).
This report is Segmented by Cooling Method (Direct, Indirect, and Two-Stage), Application (Residential, Commercial, Industrial, and More), Component (Equipment, Pads and Media, and More), Sales Channel (Direct, HVAC Contractors/Integrators, Distribution and Wholesale, and Online Retail/E-Commerce), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
North America Evaporative Cooling Market Trends and Insights
Data-center shift to low-PUE cooling
Hyperscale operators are deploying adiabatic precooling modules that shave condenser inlet temperatures by up to 40 °F, freeing as much as 14 MW for IT loads in a 300 MW campus. Microsoft's closed-loop zero-water designs and NREL's underground thermal energy storage trials highlight an ecosystem focused on water-neutral, power-lean architectures. Immersion-ready evaporative towers licensed by Baltimore Aircoil further illustrate convergence between liquid and air side solutions. As AI workloads heighten rack densities, indirect-direct stages deliver tighter thermal bands without compressor lift, placing evaporative cooling at the core of digital-infrastructure expansion.
Industrial and commercial energy-efficiency mandates
Title 24 in California now stipulates 350 Btuh/W minimums for evaporative-cooled condensers above 8,000 MBH and requires wet-bulb responsive variable-speed fans. Federal refrigerant rules that phase out GWP> 750 options accelerate the adoption of natural refrigerant systems feedable by evaporative rejectors. Natural Resources Canada mirrors U.S. thresholds, enabling cross-border equipment harmonization. Together, these policies lock in minimum performance levels that favor adiabatic or hybrid towers capable of 75% energy savings versus direct expansion chillers.
Climate humidity dependency
Evaporative effectiveness declines sharply when relative humidity climbs above 60%, leaving southeastern states reliant on hybrid desiccant-evaporative pairs. Simulations for Mexicali confirm viability only during seasonal low-humidity windows, necessitating backup dehumidification in peak months. Although dew-point indirect stages extend performance envelopes, added complexity narrows the Cap-ex gap that defines the North America evaporative cooling market advantage.
Other drivers and restraints analyzed in the detailed report include:
- CAP-ex advantage vs. compressor-based HVAC
- Renewable-microgrid + evaporative hybrid roll-outs
- Water-scarcity regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Direct units retained a 63.20% foothold in the North America evaporative cooling market in 2025, reflecting decades of installation across arid western facilities. Indirect towers held 23.70%, favored in food processing and pharmaceuticals that prohibit direct air-water contact. Two-stage indirect-direct designs recorded the fastest 5.69% CAGR, propelled by data-center and high-heat industrial retrofits that need sub-dewpoint delivery without excessive water draw.
Performance gaps are narrowing as perforated dew-point heat exchangers raise indirect effectiveness, enabling supply-air ratios below 0.5 while maintaining low pressure drops. As these materials mature, two-stage platforms are eclipsing single-stage gear in design-build specifications, a trend expected to lift their slice of the North America evaporative cooling market size by 2031. Vendors now integrate chemical-free water treatment and antimicrobial films, extending pad life and alleviating the labor bottleneck facing large campus operators.
Industrial plants generated 36.60% of 2025 revenue, driven by food, chemical, and general-manufacturing loads that prioritize robust operation and energy savings. Data centers, although smaller, are growing at a 5.34% CAGR as AI accelerates rack heat densities beyond what air-conditioned CRAC units can manage. Controlled-environment agriculture, greenhouses, and confinement farming chart a 8.74% CAGR, benefiting from the legalization of cannabis and vertical-farm momentum that positions evaporative solutions as low-energy, humidity-tunable alternatives to compressor coils.
Commercial buildings capture a 24.30% share through retail and office retrofits tied to sustainability certifications, while residential adoption advances at a modest 5.12% CAGR, largely confined to dry-climate locales. Agricultural uptake is expected to raise its chunk of the North America evaporative cooling market share beyond 10.5% by 2031 as growers seek low-carbon, low-water HVAC that protects crop transpiration profiles without costly desiccant wheels.
Complete Report Scope:
- By Cooling Method
- Direct
- Indirect
- Two-Stage (Indirect-Direct)
- By Application
- Residential
- Commercial (Retail, Offices, Hospitality)
- Industrial (Food and Beverage, Chemical, Manufacturing)
- Confinement Farming and Greenhouses
- Others
- By Component
- Equipment (Coolers and Towers)
- Pads and Media
- Water Distribution Systems
- Controls and Automation
- Services and Maintenance
- By Sales Channel
- Direct (Manufacturer to End-User)
- HVAC Contractors / Integrators
- Distribution and Wholesale
- Online Retail / E-Commerce
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Condair Group AG
- Baltimore Aircoil Company, Inc.
- Munters Group AB
- SPX Cooling Technologies, Inc.
- Delta Cooling Towers Private Limited
- Phoenix Manufacturing, Inc.
- Colt Group Holdings Limited
- Bonaire Pty Ltd
- Cambridge Engineering, Inc.
- Portacool, LLC
- EVAPCO, Inc.
- Seeley International Pty Ltd
- Symphony Limited
- Honeywell International India Private Limited
- Champion Cooler Corp.
- Mastercool, U.S.A., Inc.
- Excel Air Systems
- Air2O Cooling Limited
- The Chemours Company
- Hydro Cool Inc. (Anderson, SC)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Data-center shift to low-PUE cooling
- 4.2.2 Industrial and commercial energy-efficiency mandates
- 4.2.3 CAP-ex advantage vs. compressor-based HVAC
- 4.2.4 Renewable-microgrid + evaporative hybrid roll-outs
- 4.2.5 Cannabis and controlled-environment agriculture demand
- 4.2.6 Bio-based/hydrogel pads extending maintenance cycles
- 4.3 Market Restraints
- 4.3.1 Climate humidity dependency
- 4.3.2 Escalating water-scarcity regulations
- 4.3.3 Wildfire-smoke IAQ compliance hurdles
- 4.3.4 Skilled-labor shortages for scale-control and hygiene
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro-economic Impact
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Cooling Method
- 5.1.1 Direct
- 5.1.2 Indirect
- 5.1.3 Two-Stage (Indirect-Direct)
- 5.2 By Application
- 5.2.1 Residential
- 5.2.2 Commercial (Retail, Offices, Hospitality)
- 5.2.3 Industrial (Food and Beverage, Chemical, Manufacturing)
- 5.2.4 Confinement Farming and Greenhouses
- 5.2.5 Others
- 5.3 By Component
- 5.3.1 Equipment (Coolers and Towers)
- 5.3.2 Pads and Media
- 5.3.3 Water Distribution Systems
- 5.3.4 Controls and Automation
- 5.3.5 Services and Maintenance
- 5.4 By Sales Channel
- 5.4.1 Direct (Manufacturer to End-User)
- 5.4.2 HVAC Contractors / Integrators
- 5.4.3 Distribution and Wholesale
- 5.4.4 Online Retail / E-Commerce
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Condair Group AG
- 6.4.2 Baltimore Aircoil Company, Inc.
- 6.4.3 Munters Group AB
- 6.4.4 SPX Cooling Technologies, Inc.
- 6.4.5 Delta Cooling Towers Private Limited
- 6.4.6 Phoenix Manufacturing, Inc.
- 6.4.7 Colt Group Holdings Limited
- 6.4.8 Bonaire Pty Ltd
- 6.4.9 Cambridge Engineering, Inc.
- 6.4.10 Portacool, LLC
- 6.4.11 EVAPCO, Inc.
- 6.4.12 Seeley International Pty Ltd
- 6.4.13 Symphony Limited
- 6.4.14 Honeywell International India Private Limited
- 6.4.15 Champion Cooler Corp.
- 6.4.16 Mastercool, U.S.A., Inc.
- 6.4.17 Excel Air Systems
- 6.4.18 Air2O Cooling Limited
- 6.4.19 The Chemours Company
- 6.4.20 Hydro Cool Inc. (Anderson, SC)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and unmet-need assessment


