

|
시장보고서
상품코드
2121368
북미의 의료 시뮬레이션 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Medical Simulation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
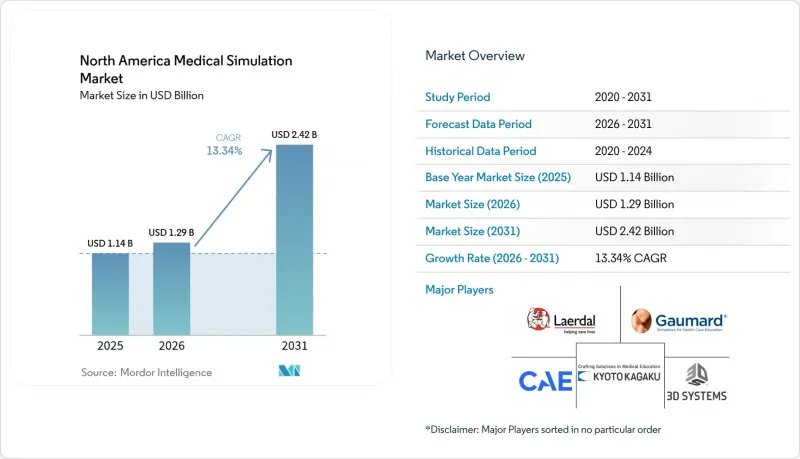
에 따르면 2026년 북미의 의료 시뮬레이션 시장 규모는 12억 9,000만 달러로 추정되고 있으며, 2025년 11억 4,000만 달러에서 확대하며, 2031년에는 24억 2,000만 달러에 달할 것으로 예측됩니다.
2026-2031년까지 연평균 성장률(CAGR) 13.34%로 성장할 것으로 전망됩니다.
이 보고서는 제품·서비스(제품, 서비스, 소프트웨어), 피델리티(고, 중 등), 최종사용자(학술·연구 기관, 병원·외과 센터 등), 제공 방식(온프레미스 시뮬레이션 랩, 클라우드), 지역(미국, 캐나다, 멕시코)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미 의료 시뮬레이션 시장의 동향 및 인사이트
최소 침습 수술 훈련에 대한 수요
복강경 수술, 로봇 수술, 내시경 수술 기술에는 기존의 수습 제도만으로는 대규모로 제공할 수 없는 정신운동 기술이 요구됩니다. 8,400달러 전후의 합리적인 가격의 로봇 수술 인터페이스 덕분에 자원이 제한된 교육 기관에서도 첨단 기술 훈련에 대한 접근성이 확대되었습니다. 햅틱 기능을 갖춘 가상현실은 수련생이 실제 수술실에 들어가기 전에 근육 기억을 기르고 시술에 대한 자신감을 높일 수 있게 해주며, 이러한 툴을 활용하는 프로그램에서는 수술 중 오류율이 크게 감소하고 있습니다. 외과 의사 부족을 보완하기 위한 로봇 플랫폼의 확대는 시뮬레이션을 일선 교육 기법으로 더욱 확고히 자리매김하게 하고 있습니다. 교육 과정에 반복 횟수가 높고 위험이 없는 실습 세션이 핵심 학습으로 통합됨에 따라 이 요인으로 인해 예측 연평균 성장률(CAGR)이 2.8퍼센트 포인트 상승하고 있습니다.
환자 안전 및 오류 감소 노력에 대한 관심 증가
시뮬레이션 기반 카테터 삽입 교육 과정을 통해 시설당 연간 9.95건의 혈류 감염이 감소하여 70만 달러 이상의 비용 절감과 7대 1의 ROI(투자 수익률)를 달성하고 있습니다. 이러한 실증 결과를 통해 시뮬레이션은 단순한 교육상의 부수적 비용에서 재무상의 필수 요건으로 그 위상이 변화하고 있습니다. 조인트 커미션(Joint Commission)과 같은 인증 기관은 현재 문서화된 역량 평가 지표를 요구하고 있으며, 시뮬레이션은 표준화된 시나리오와 자동 채점을 통해 이를 독보적인 형태로 제공합니다. 병원들은 이러한 지표를 활용하여 가치 기반 보상 제도의 요건을 충족하고, 의료 과실 위험을 줄이면서 치료의 질을 향상시키고 있습니다.
임상 교수진 부족이 시뮬레이션 시간 증가를 촉진
의과대학 학장의 84%가 임상 실습 부족을 지적하고 있으며, 이로 인해 각 의과대학은 시뮬레이션 할당 시간을 늘릴 수밖에 없는 상황입니다. 최신 시뮬레이션 센터에서는 적응형 시나리오와 분석 대시보드를 활용하여 한 명의 지도자가 여러 학습자를 감독할 수 있게 됨으로써, 지도의 범위를 확대하고 있습니다. COVID-19로 인한 혼란은 시뮬레이션이 단순한 보조 툴이 아니라 교육 과정의 근간을 이루는 요소라는 점을 입증했습니다. 따라서 장기적인 교원 부족으로 인해 팬데믹으로 인한 압박을 넘어 시뮬레이션에 대한 수요는 계속해서 높은 수준을 유지할 것입니다.
부문 분석
제품 부문은 학술기관 및 병원 실습실의 물리적 인프라로서 2025년 매출의 53.12%를 차지하고 있습니다. 이 총액 중 중재 및 외과용 시뮬레이터가 여전히 핵심을 이루고 있으며, 태스크 트레이너와 생리학적 마네킹이 이를 보완하고 있습니다. 그러나 서비스 부문은 자본 지출보다 턴키식의 구독 서비스를 선호하는 기관들의 수요에 힘입어 연평균 성장률(CAGR) 13.41%로 확대되고 있습니다. 클라우드 라이선싱, 커리큘럼 설계, 실험실 관리 서비스는 일회성 구매를 예측 가능한 운영 예산으로 전환시키고 있으며, 이는 의료 시뮬레이션 시장에 있으며, 매우 중요한 전환점이 되고 있습니다.
중재 시술용 시뮬레이터에 대한 수요는 로봇 수술 및 복강경 수술의 증가를 반영하고 있는 반면, 환자용 시뮬레이터는 실제 모니터링 기기와 연동되는 무선 방식의 생리학적 기능이 풍부한 모델로 진화하고 있습니다. 이러한 서비스의 성장세는 3B Scientific사의 ‘e Sono’와 같은 SaaS형 초음파 플랫폼에서 가장 두드러지게 나타나며, 이는 종량제 방식의 접근이 첨단 훈련을 얼마나 널리 보급하고 있는지를 보여줍니다. 지속적인 수익이 증가함에 따라 의료 시뮬레이션 업계는 과거 고충실도 하드웨어 분야의 가격이 너무 비싸 진입할 수 없었던 소규모 의료 기관으로도 대상을 확대하고 있습니다.
저충실도 툴은 저렴한 가격과 신속한 도입이 가능하다는 점 덕분에 2025년 지출의 46.92%를 차지하고 있습니다. 그럼에도 불구하고 실증 연구를 통해 현실성과 측정 가능한 학습 효과 간의 연관성이 입증됨에 따라 고충실도 시뮬레이터는 연평균 성장률(CAGR) 13.68%를 기록하고 있습니다. 고충실도 시뮬레이터 카테고리에는 현재 동적 폐 순응도 및 약물 인식 기능을 갖춘 Gaumard사의 HAL S3201과 같은 마네킹이 포함되어 있으며, 시뮬레이션 스위트와 실제 중환자실 병상 간의 격차를 해소하고 있습니다. 의료 기관들은 실수 감소를 통한 비용 절감 효과를 정량화함으로써 고액의 투자를 정당화하고 있으며, 그 결과 의료 시뮬레이션 시장에서 이 분야의 점유율이 확대되고 있습니다.
중간 충실도 시스템은 핵심 기술 훈련에 있으며, 여전히 중요하지만, 고급 프로그램에서는 생체 신호, 영상 진단, 전자 차트를 동기화한 몰입감 높은 경험으로 빠르게 전환되고 있습니다. 이러한 전환은 점점 더 복잡해지는 환자층에 대응할 수 있도록 임상의들을 더 적절히 준비시키는 ‘초현실적인’ 시뮬레이션으로 조달 예산이 장기적으로 이동하고 있음을 보여줍니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, north american medical simulation market size in 2026 is estimated at USD 1.29 billion, growing from 2025 value of USD 1.14 billion with 2031 projections showing USD 2.42 billion, growing at 13.34% CAGR over 2026-2031.
This report is Segmented by Products & Services (Products, Services & Software), Fidelity (High-Fidelity, Medium-Fidelity, and More), End User (Academic & Research Institutes, Hospitals & Surgical Centers, and More), Delivery Mode (On-Premise Simulation Labs, Cloud-Based), and Geography (United States, Canada, Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Medical Simulation Market Trends and Insights
Demand for Minimally-Invasive-Procedure Training
Laparoscopic, robotic, and endoscopic techniques demand psychomotor skills that traditional apprenticeship models cannot deliver at scale. Affordable robotic-surgery interfaces priced near USD 8,400 have widened access to advanced skills practice for resource-constrained schools. Haptic-enabled virtual reality fosters muscle memory and boosts procedural confidence before trainees enter live theaters, and programs using these tools record significant declines in intra-operative error rates. Growth of robotic platforms to offset surgeon shortages further cements simulation as a frontline training modality. The driver adds 2.8 percentage points to forecast CAGR as curricula embed high-repetition, risk-free practice sessions into core learning.
Rising Focus on Patient-Safety & Error-Reduction Mandates
Simulation-based catheter insertion curricula cut 9.95 bloodstream infections per facility each year, saving more than USD 700,000 and delivering a seven-to-one ROI. Such proof reframes simulation from educational overhead to financial imperative. Accrediting bodies like the Joint Commission now require documented competency metrics, which simulation uniquely provides through standardized scenarios and automated scoring. Hospitals leverage these metrics to satisfy value-based reimbursement schemes, shrinking malpractice exposure while elevating care quality.
Shortage of Clinical Faculty Driving Simulation Hours
Eighty-four percent of deans cite clerkship shortages, forcing schools to raise simulation quotas. Modern centers let one instructor oversee multiple learners via adaptive scenarios and analytics dashboards, multiplying teaching reach. The COVID-19 disruption validated simulation's role as curricular backbone rather than ancillary tool. Long-term faculty gaps therefore sustain elevated demand well beyond pandemic pressures.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of VR/AR Hardware Breakthroughs in Simulators
- High Upfront Capital & Maintenance Cost of High-Fidelity Units
- VR-Induced Cybersickness Impacting Learner Acceptance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Products commanded 53.12% of 2025 revenue as the physical backbone of academic and hospital labs. Within that total, interventional and surgical simulators remain the cornerstone, supplemented by task trainers and physiologic manikins. Yet the services category is expanding at a 13.41% CAGR, propelled by institutions favoring turnkey subscriptions over capital outlay. Cloud licensing, curriculum design, and managed-lab services convert episodic purchases into predictable operating budgets, a pivotal shift for the medical simulation market.
Interventional simulator demand mirrors the growth of robotic and laparoscopic procedures, while patient simulators evolve toward wireless, physiology-rich models that integrate with real monitoring devices. Services momentum is most evident in SaaS ultrasound platforms such as 3B Scientific's e Sono, which illustrates how pay-as-you-go access democratizes advanced training. As recurring revenue rises, the medical simulation industry expands its addressable audience to smaller institutions once priced out of the high-fidelity hardware segment.
Low-fidelity tools hold 46.92% of 2025 spend thanks to affordability and quick deployment. Nevertheless, high-fidelity simulators are logging a 13.68% CAGR as empirical studies tie realism to measurable learning gains. The high-fidelity cohort now includes manikins like Gaumard's HAL S3201 with dynamic lung compliance and drug recognition, bridging the gap between simulation suites and real ICU beds. Institutions justify higher outlays by quantifying error-reduction savings, thereby growing this share of the medical simulation market size.
Medium-fidelity systems remain important for core skills drills, but advanced programs are fast-tracking toward high-immersion experiences that synchronize vitals, imaging, and electronic records. That migration signals a long-run pivot of procurement budgets toward ultra-realism that better prepares clinicians for increasingly complex patient populations.
Complete Report Scope:
- By Products & Services
- Products
- Interventional/Surgical Simulators
- Laparoscopic
- Robotic & Endoscopic
- Orthopaedic
- Patient Simulators
- Task Trainers
- Other Products
- Interventional/Surgical Simulators
- Services & Software
- Web-based Simulation
- Simulation Software Licences
- Training & Consulting Services
- Products
- By Fidelity
- High-fidelity
- Medium-fidelity
- Low-fidelity
- By End User
- Academic & Research Institutes
- Hospitals & Surgical Centres
- Military & Defence Organisations
- Medical-device & Pharma Companies
- By Delivery Mode
- On-premise Simulation Labs
- Cloud-based /Remote Platforms
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- CAE
- Laerdal Medical AS
- Gaumard Scientific Company, Inc.
- 3D Systems
- Simulab
- Surgical Science Sweden
- Intelligent Ultrasound Group plc
- Mentice
- SimX, Inc.
- VirtaMed
- Operative Experience
- Inovus Medical Ltd.
- Limbs & Things Ltd.
- TruCorp Ltd.
- IngMar Medical, Ltd.
- KavoKerr Group (Dental Simulators)
- VRPatient, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for minimally-invasive-procedure training
- 4.2.2 Rising focus on patient-safety & error-reduction mandates
- 4.2.3 Adoption of VR/AR hardware breakthroughs in simulators
- 4.2.4 Shortage of clinical faculty driving simulation hours
- 4.2.5 AI-driven adaptive simulation analytics (under-reported)
- 4.2.6 ESG-linked "zero-harm" corporate training targets (under-reported)
- 4.3 Market Restraints
- 4.3.1 High upfront capital & maintenance cost of high-fidelity units
- 4.3.2 Lack of interoperability standards across simulation platforms
- 4.3.3 Limited faculty training & change-management bandwidth
- 4.3.4 VR-induced cybersickness impacting learner acceptance (under-reported)
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Products & Services
- 5.1.1 Products
- 5.1.1.1 Interventional/Surgical Simulators
- 5.1.1.1.1 Laparoscopic
- 5.1.1.1.2 Robotic & Endoscopic
- 5.1.1.1.3 Orthopaedic
- 5.1.1.2 Patient Simulators
- 5.1.1.3 Task Trainers
- 5.1.1.4 Other Products
- 5.1.1.1 Interventional/Surgical Simulators
- 5.1.2 Services & Software
- 5.1.2.1 Web-based Simulation
- 5.1.2.2 Simulation Software Licences
- 5.1.2.3 Training & Consulting Services
- 5.1.1 Products
- 5.2 By Fidelity
- 5.2.1 High-fidelity
- 5.2.2 Medium-fidelity
- 5.2.3 Low-fidelity
- 5.3 By End User
- 5.3.1 Academic & Research Institutes
- 5.3.2 Hospitals & Surgical Centres
- 5.3.3 Military & Defence Organisations
- 5.3.4 Medical-device & Pharma Companies
- 5.4 By Delivery Mode
- 5.4.1 On-premise Simulation Labs
- 5.4.2 Cloud-based /Remote Platforms
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 CAE Inc.
- 6.3.2 Laerdal Medical AS
- 6.3.3 Gaumard Scientific Company, Inc.
- 6.3.4 3D Systems Corporation
- 6.3.5 Simulab Corporation
- 6.3.6 Surgical Science Sweden AB
- 6.3.7 Intelligent Ultrasound Group plc
- 6.3.8 Mentice AB
- 6.3.9 SimX, Inc.
- 6.3.10 VirtaMed AG
- 6.3.11 Operative Experience, Inc.
- 6.3.12 Inovus Medical Ltd.
- 6.3.13 Limbs & Things Ltd.
- 6.3.14 TruCorp Ltd.
- 6.3.15 IngMar Medical, Ltd.
- 6.3.16 KavoKerr Group (Dental Simulators)
- 6.3.17 VRPatient, Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


