

|
시장보고서
상품코드
2121369
스테아르산 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Stearic Acid - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 스테아르산 시장 규모는 2025년에 998만 톤으로 평가되었고, 2026년 1,051만 톤에서 2031년까지 1,359만 톤에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.31%를 기록할 전망입니다.
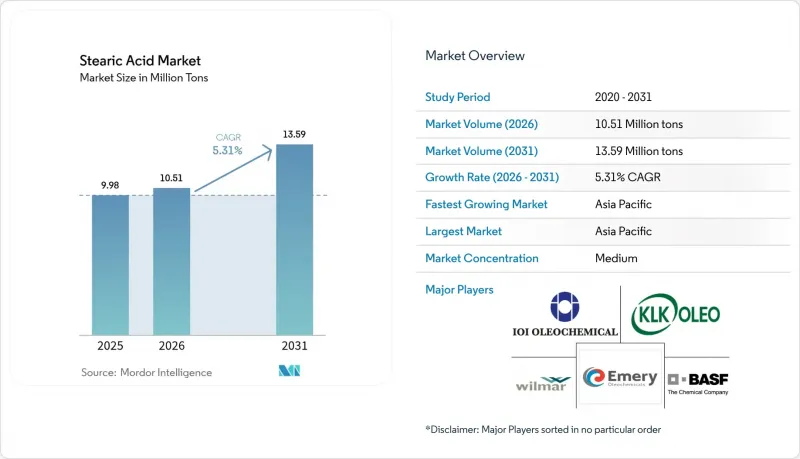
본 보고서는 원료(동물성 및 식물성), 등급(3회 압착 스테아린산, 고무용 스테아린산, 식품 등급 스테아린산, 화장품·의약품 등급 스테아린산), 용도(플라스틱, 비누 및 세제 등),지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 수량(톤) 단위로 표시되어 있습니다.
세계 스테아린산 시장 동향 및 인사이트
퍼스널케어용 원료 수요 증가
클린 라벨 트렌드에 따라 고순도 스테아린산 등급의 채택이 급속히 확대되고 있습니다. BASF의 기후 변화에 대응한 미용 제품 포트폴리오에서는 재생 가능한 유화제가 소개되어 있으며, 퍼스널케어 제품의 제형 개발자들이 석유화학 유래 왁스를 식물 유래 지방산으로 대체하고 있는 실제 사례를 보여주고 있습니다. SMIngredients와 같은 원료 개발 기업들은 ‘식물성 오일 파우더’로 표기 가능한 스테아린산 유도체를 추진하고 있으며, 뉴트라슈티컬(영양 보조 식품)용 정제에서의 수용 범위를 넓히고 있습니다. 다국적 기업들은 인증된 공급망을 확보하고 있습니다. 카오(Kao)는 2024년에 농장 수준까지의 추적 가능성을 87% 달성하여 산림 파괴 위험을 줄이는 동시에 프리미엄층 소비자에게 안심감을 제공합니다. 미국 FDA의 GRAS(일반적으로 안전하다고 인정되는) 인증은 화장품 및 외용 용도에 대한 신뢰를 지속적으로 뒷받침하고 있습니다. 이러한 요인들이 결합되어, 스테아린산 시장에서 화장품용 및 의약품용 등급 원료의 판매량 성장이 확실시되고 있습니다.
세계 세제 시장의 확대
신흥국의 가정용 세탁 시장 성장이 비누 및 계면활성제 수요를 끌어올리고 있습니다. 아시아태평양은 도시화 진전과 가처분 소득 증가에 힘입어 여전히 수량 기준으로 최대의 세제 시장을 형성하고 있습니다. 필리핀에서 새로운 설폰화 생산 설비가 가동됨에 따라 세제 중간체의 연간 공급량이 4만 톤 증가하여, 해당 지역에서 지방산 원료에 대한 수요가 높아지고 있습니다. 의류 관리 효과와 향의 지속성을 내세우는 고급 세제 제품에는 더 많은 스테아린산이 배합되어 있어 톤당 가치를 높이고 있습니다. 또한, 브랜드 소유자들이 ‘친환경’이라는 판매 포인트의 어필력을 높이기 위해 석유 유래 계면활성제를 바이오 유래 대체재로 대체하고 있는 점도 스테아린산 시장에 추가적인 혜택을 가져다주고 있습니다. 장기적으로는 세제 시장이 견인차 역할을 하여, 특히 트리플 프레스 등급에서 예측 가능한 기본 소비량을 확보하게 될 것입니다.
동물성 지방 및 팜유 가격 변동
인도네시아와 말레이시아의 바이오디젤 의무화 및 공급 부족이 겹치면서, 2025년 초까지 팜유 선물 가격은 톤당 4,000-4,600 링깃 범위에서 형성되고 있습니다. 바이오연료 생산자들이 원료 확보 경쟁을 벌이는 가운데, 동물성 지방 및 사용 후 식용유 가격에도 유사한 변동이 발생하여 유지 화학제품의 이익률을 압박하고 있습니다. 운임 변동이 비용의 불확실성을 더욱 증폭시키고 있습니다. 2025년 4월에는 FAO 식물성 기름 지수가 하락했고, 해상 운송비도 감소했습니다. 스테아린산 제조업체들은 코로나19 팬데믹 이후 원유, 대두, 팜유 가격 간의 상관관계가 약화되어 예측 정확도가 떨어졌기 때문에 헤지 전략 수립에 어려움을 겪고 있습니다. 원자재 리스크가 높아짐에 따라 현물 시장에서의 구매가 위축되고, 하류 프로젝트의 가동이 지연되고 있으며, 이는 스테아린산 시장의 성장을 저해하고 있습니다.
부문별 분석
2025년, 스테아린산 시장에서 식물 유래 원료의 점유율은 66.42%를 차지하고 있으며, 주요 생산자들이 RSPO 인증 팜 스테아린에 대한 투자를 강화하고 있는 만큼, 2031년까지 연평균 성장률(CAGR) 5.47%로 출하량이 증가할 것으로 예측됩니다. 식물 유래 원료의 스테아린산 시장 규모는 예측 기간 동안 245만 톤 증가할 것으로 예상되며, 동물성 지방 유래 제품을 상회하는 성장률을 보일 전망입니다. 말레이시아 및 인도네시아의 통합형 가공업체들은 인접한 농장,정제소, 유지화학 공장을 활용하여 추적성을 확보하는 동시에 물류 비용을 최소화하고 있습니다. 티센크루프 우데(ThyssenKrupp Ude)와 노보네시스(Novonesis)가 개발한 효소 에스테르화 기술은 에너지 사용량을 60% 절감하여 지속가능성 노력을 강화하고 있습니다.
고무 첨가제 분야에서 역사적으로 주류를 이루었던 동물 유래 제조 방식은 추적 가능성 및 질병 위험과 관련된 이미지상의 과제에 직면해 있습니다. 그러나 특정 사슬 길이 분포가 필요한 용도나, 렌더링 산업을 통해 동물성 지방을 쉽게 입수할 수 있는 지역에서는 여전히 틈새 시장으로서의 중요성을 유지하고 있습니다. 동물 유래 잔류 동물용 의약품에 대한 규제가 강화됨에 따라 시장 점유율의 추가적인 하락은 억제될 가능성이 있지만, 그 보급은 제한적인 수준에 그칠 것으로 보입니다. 발효 유래 지질 기술이 성숙해짐에 따라, 스테아르산 업계에서는 향후 10년 동안 원료의 다양화가 더욱 진행될 가능성이 있지만, 현재 시점에서 상업적 생산량은 여전히 제한적입니다.
지역별 분석
아시아태평양은 2025년에 스테아르산 시장의 71.78%를 차지할 것이며, 해당 지역 각국 정부가 특수 화학제품의 부가가치 향상을 우선시하고 있는 만큼 2031년까지 연평균 성장률(CAGR) 5.69%를 나타낼 것으로 예측됩니다. 말레이시아의 ‘화학 산업 로드맵’은 2030년까지 국내총생산(GDP) 기여율을 4.5%로 높이는 목표를 제시하고 있으며, 해당국의 유지화학 클러스터 전반에 걸친 생산 능력 향상과 기술 도입을 지원하고 있습니다. 인도네시아의 B40 바이오디젤 추진은 국내 팜유 수요를 증가시키고 원료 가격을 끌어올리는 한편, 지방산 생산에 이익을 가져다주는 정제소의 하류 통합도 촉진하고 있습니다.
북미는 FDA의 엄격한 규정 준수 및 인증된 원재료에 대해 소비자가 기꺼이 대가를 지불하려는 태도에 힘입어 프리미엄 구매 기반으로 자리매김하고 있습니다. 정밀 발효를 통한 지질에 대한 투자는 향후 현지 공급을 보장해 주겠지만, 현재로서는 이 지역이 범용 제품 및 고품질 원료 모두에서 동남아시아산 수입에 의존하고 있습니다. 유럽에서는 지속가능성을 중시하는 시장 환경이 유지되고 있습니다. EU의 스테아르산 시장 규모는 화장품 및 식품 규제 당국이 순도 및 추적성 요건을 강화함에 따라 완만하지만 꾸준히 확대되고 있으며, 고수익률의 인증 등급을 위한 시장이 형성되고 있습니다.
남미, 중동 및 아프리카는 신흥 성장 지역입니다. 브라질의 대규모 농업 및 산업 기반이 국내 지방산 에스테르 생산 능력을 뒷받침하고 있으며, 이 나라는 플라스틱 및 세제 분야에서 수입품을 대체할 수 있는 입장에 있습니다. 걸프 지역에서는 새로운 석유화학 단지에 수입된 팜 스테아린을 사용하는 유지 화학 공장이 통합되어, 지역의 세제 수요를 흡수하고 있습니다. 도시 인구 증가, 1인당 소득 상승, 그리고 투자를 촉진하는 우대 조치 덕분에 이 지역들은 스테아린산 시장의 제2차 확장을 위한 매력적인 시장이 되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the stearic acid market size was valued at 9.98 Million tons in 2025 and estimated to grow from 10.51 Million tons in 2026 to reach 13.59 Million tons by 2031, at a CAGR of 5.31% during the forecast period (2026-2031).
This report is Segmented by Feedstock (Animal-Based and Vegetable-Based), Grade (Triple-Pressed Stearic Acid, Rubber-Grade Stearic Acid, Food-Grade Stearic Acid, and Cosmetic-/Pharma-Grade Stearic Acid), Application (Plastics, Soaps and Detergents, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Stearic Acid Market Trends and Insights
Growth of Personal-Care Ingredients Demand
Clean-label trends drive strong uptake of high-purity stearic acid grades. BASF's climate-adaptive beauty portfolio showcases renewable emulsifiers that illustrate how personal-care formulators substitute petrochemical waxes with vegetable-based fatty acids. Ingredient developers such as SMIngredients promote stearic-acid derivatives that allow "vegetable oil powder" labelling, widening acceptance in nutraceutical tablets. Multinationals secure certified supply chains; Kao achieved 87% traceability to plantation level in 2024, lowering deforestation risks and reassuring premium consumers. The US FDA's GRAS affirmation continues to underpin confidence in cosmetic and topical use. Together these factors lock in volume growth for cosmetic- and pharma-grade material within the stearic acid market.
Expansion of Global Detergents Sector
Household-laundry growth in emerging economies elevates soap and surfactant demand. Asia-Pacific remains the largest detergent market by volume, supported by rising urbanization and disposable incomes. New sulfonation capacity in the Philippines adds 40,000 t annual supply of detergent intermediates, increasing regional pull for fatty-acid raw materials. Premium detergent formats that promise fabric care and fragrance longevity incorporate higher stearic acid loadings, lifting value per ton. The stearic acid market benefits further as brand owners replace petroleum-based surfactants with bio-based alternatives to gain "green" shelf appeal. Over the long run, the detergents driver secures predictable baseline consumption, especially for triple-pressed grades.
Volatility in Tallow and Palm-Oil Prices
Palm-oil futures hover between MYR 4,000 and 4,600 per t through early 2025 as tight supply meets biodiesel mandates in Indonesia and Malaysia. Similar swings in tallow and used-cooking-oil values arise as biofuel producers compete for feedstock, eroding oleochemical margins. Freight-rate fluctuations compound cost unpredictability; the FAO vegetable-oil index fell in April 2025 while ocean-shipping prices also declined. Stearic acid producers struggle to hedge because post-COVID correlations between crude, soybean, and palm prices weakened, reducing forecast accuracy. Elevated raw-material risk restricts spot-market buying and delays downstream project launches, restraining the stearic acid market.
Other drivers and restraints analyzed in the detailed report include:
- Capacity Additions by Southeast-Asian Oleochemical Plants
- Shift Toward RSPO-Certified Palm Stearin Feedstocks
- ESG-Driven Capital Flight from Palm-Based Supply Chains
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vegetable-based inputs held 66.42% share of the stearic acid market in 2025, and volumes are forecast to rise at 5.47% CAGR through 2031 as major producers double down on RSPO-certified palm stearin. The stearic acid market size for vegetable feedstock is projected to grow by 2.45 million tons over the forecast, outpacing animal-fat counterparts. Integrated processors in Malaysia and Indonesia leverage contiguous plantations, refineries, and oleochemical units to minimize logistics costs while ensuring traceability. Enzymatic esterification developed by thyssenkrupp Uhde and Novonesis cuts energy use by 60%, enhancing sustainability credentials.
Animal-based routes, historically dominant in rubber additives, face image challenges over traceability and disease risk. Yet they retain niche relevance in applications requiring specific chain-length distributions and in regions where tallow is readily available from rendering industries. Regulatory tightening on veterinary drug residues could limit further share loss, but uptake will stay modest. As fermentation-based lipids mature, the stearic acid industry may witness a broader diversification of feedstock in the next decade, though commercial volumes remain limited today.
Complete Report Scope:
- By Feedstock
- Animal-based
- Vegetable-based
- By Grade
- Triple-Pressed Stearic Acid
- Rubber-Grade Stearic Acid
- Food-Grade Stearic Acid
- Cosmetic-/Pharma-Grade Stearic Acid
- By Application
- Soaps and Detergents
- Personal Care
- Plastics
- Rubber Processing
- Textiles
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated the stearic acid market in 2025 with 71.78% share and is forecast to grow at 5.69% CAGR to 2031 as regional governments prioritize specialty-chemical value addition. Malaysia's Chemical Industry Roadmap targets a 4.5% contribution to national GDP by 2030, supporting capacity upgrades and technology adoption across its oleochemical cluster. Indonesia's push toward B40 biodiesel increases local palm-oil demand, lifting feedstock prices but also encouraging refinery downstream integration that benefits fatty-acid output.
North America ranks as a premium buyer base, driven by strict FDA compliance and consumer readiness to pay for certified inputs. Investments in precision-fermentation lipids promise future local supply, but today the region depends on imports from Southeast Asia for both commodity and high-grade material. Europe maintains a sustainability-led market environment. The stearic acid market size in the EU grows modestly yet consistently as cosmetics and food regulators tighten purity and traceability demands, creating a market for high-margin certified grades.
South America and the Middle-East and Africa are emerging growth territories. Brazil's large agro-industrial base underpins domestic fatty-acid ester capacity, positioning the country to substitute imports in plastics and detergents. In the Gulf, new petrochemical parks integrate oleochemical trains that use imported palm stearin, capturing regional detergent demand. Rising urban populations, higher per-capita income, and supportive investment incentives make these geographies attractive for second-wave expansion in the stearic acid market.
- 3F Industries Ltd
- Acme-Hardesty
- Adani Wilmar Ltd
- BASF SE
- Croda International Plc
- Emery Oleochemicals
- Godrej Industries Limited
- IOI Oleochemical
- Kao Corporation
- KLK OLEO
- New Japan Chemical Co. Ltd
- Oleon NV
- Pacific Oleochemicals Sdn Bhd
- Procter and Gamble
- PT SMART Tbk
- Twin Rivers Technologies, Inc.
- VVF Ltd
- Wilmar International Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of Personal-Care Ingredients Demand
- 4.2.2 Expansion of Global Detergents Sector
- 4.2.3 Capacity Additions by Southeast-Asian Oleochemical Plants
- 4.2.4 Shift Toward RSPO-Certified Palm Stearin Feedstocks
- 4.2.5 Rapid Scale-Up of 3-D-Printed Biodegradable Plastics Using Stearic-Acid Lubricants
- 4.3 Market Restraints
- 4.3.1 Volatility in Tallow and Palm Oil Prices
- 4.3.2 Toxicity Concerns at High Concentrations
- 4.3.3 ESG-Driven Capital Flight from Palm-Based Supply Chains
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value and Volume)
- 5.1 By Feedstock
- 5.1.1 Animal-based
- 5.1.2 Vegetable-based
- 5.2 By Grade
- 5.2.1 Triple-Pressed Stearic Acid
- 5.2.2 Rubber-Grade Stearic Acid
- 5.2.3 Food-Grade Stearic Acid
- 5.2.4 Cosmetic-/Pharma-Grade Stearic Acid
- 5.3 By Application
- 5.3.1 Soaps and Detergents
- 5.3.2 Personal Care
- 5.3.3 Plastics
- 5.3.4 Rubber Processing
- 5.3.5 Textiles
- 5.3.6 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 3F Industries Ltd
- 6.4.2 Acme-Hardesty
- 6.4.3 Adani Wilmar Ltd
- 6.4.4 BASF SE
- 6.4.5 Croda International Plc
- 6.4.6 Emery Oleochemicals
- 6.4.7 Godrej Industries Limited
- 6.4.8 IOI Oleochemical
- 6.4.9 Kao Corporation
- 6.4.10 KLK OLEO
- 6.4.11 New Japan Chemical Co. Ltd
- 6.4.12 Oleon NV
- 6.4.13 Pacific Oleochemicals Sdn Bhd
- 6.4.14 Procter and Gamble
- 6.4.15 PT SMART Tbk
- 6.4.16 Twin Rivers Technologies, Inc.
- 6.4.17 VVF Ltd
- 6.4.18 Wilmar International Ltd
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Application Upside in Metal Cleaning and Sustainable Candle Waxes


