|
시장보고서
상품코드
2121388
전기 수술 기기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Electrosurgical Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
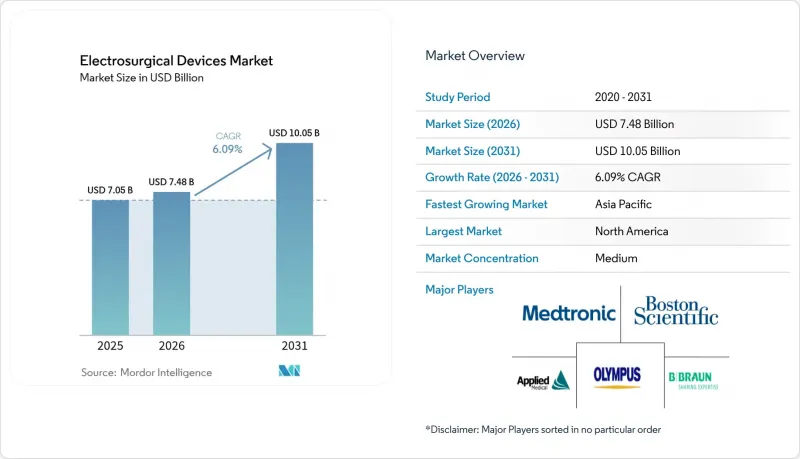
에 의하면, 전기 수술 기기 시장 규모는 2025년에 70억 5,000만 달러로 평가되었고, 2026년 74억 8,000만 달러에서 2031년까지 100억 5,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 6.09%를 기록할 전망입니다.
본 보고서는 제품별(전기 수술용 발전기, 기구 및 부속품(양극식 기구 등), 기타), 용도별(일반외과, 뇌신경외과, 기타), 에너지 방식별(단극 고주파, 양극 고주파, 기타), 최종 사용자별(병원, 외래수술센터(ASC), 기타), 지역별(북미, 유럽, 아시아태평양, 기타)로 분류되어 있습니다.
세계 전기 수술 기기 시장 동향 및 인사이트
만성 질환 증가와 고령화
세계 평균 수명의 연장에 따라, 여러 기저 질환을 앓고 있는 환자가 수술실에 늘어나고 있으며, 당뇨병 유병률의 상승에 따라 심혈관계 수술 건수만으로도 급증할 것으로 예측됩니다. 따라서 외과의사는 취약하고 합병증이 동반된 조직 영역 내에서 지혈을 제어할 수 있는 양극 및 초음파 플랫폼을 필요로 합니다. 지능형 에너지 콘솔은 와트 수를 정밀하게 조절하여 열 확산을 최소화함으로써, 생리적 예비 능력이 제한된 고령 환자층의 우려를 완화합니다. 이와 유사한 인구 통계학적 추세로 인해 관절 치환술 재수술 및 종양 절제술 건수가 증가하고 있으며, 이로 인해 전기 수술 기기 시장의 잠재 고객 기반이 확대되고 있습니다. 북미 및 서유럽의 병원들은 조직 임피던스 모니터링 기능이 통합된 발전기로의 업그레이드에 주력하고 있으며, 이를 통해 조직 온도의 의도파관 않은 상승을 밀리초 단위로 감지하고 시정할 수 있게 되었습니다. 장기적으로는 고령화와 만성 질환의 복합적인 영향으로 인해 전체 연평균 성장률(CAGR) 예측치에 1.8퍼센트 포인트의 긍정적 요인이 더해질 것입니다.
최소 침습 수술에 대한 선호
보험사 및 의료 제공업체들은 입원 기간 단축과 조기 직장 복귀를 주요 가치 지표로 점점 더 중요하게 여기고 있습니다. 복강경, 흉강경, 내시경 수술은 그 특성상 슬림하고 발열이 적은 기구에 의존하고 있으며, 이것이 저침습 수술실의 설비 투자 예산에서 첨단 양극식 및 초음파 시어가 주류를 이루고 있는 이유입니다. 이동식 타워 아래에 설치할 수 있도록 설계된 소형 전기 수술용 발전기는 비좁은 수술실 내의 귀중한 공간을 효율적으로 활용합니다. 아시아태평양에서 미세 절개 수술의 보급은 과거 미국 특유의 성장 곡선에 가까워지고 있으며, 통합형 연기 흡입 장치 및 온도 제어형 RF 전극의 수익 가능성을 넓히고 있습니다. 최근 4년간의 경제 모델에 따르면, 온도 제어형 고주파 기기는 계획 기준 2,000만 달러의 비용 절감과 치료받은 환자 1인당 3,531달러의 비용 절감을 가져온 것으로 나타나, ‘가치 기반 지불’의 근거를 뒷받침하고 있습니다.
숙련된 전기외과 전문의 부족
SAGES의 FUSE 프로그램과 같은 시뮬레이션 기반 교육 과정 덕분에 지식 평가 점수는 향상되었지만, 완전한 자격을 갖춘 전기 외과 의사에 대한 수요는 여전히 공급을 초과하고 있습니다. 저·중소득 국가에서는 많은 수술실에서 지도 의사가 부족하여, 그 결과 병원 측은 직원의 역량이 향상될 때까지 발전기 교체를 미룰 수밖에 없는 상황에 처해 있습니다. 2023년 관찰자 맹검 연구에 따르면, 수련의가 루프식 전기외과적 절제술을 자신 있게 수행할 수 있게 되기까지 지도 하에 10회의 실습을 받은 후에야 비로소 향상이 나타났습니다고 보고되어, 학습 곡선이 가파르다는 점을 여실히 보여주고 있습니다. 기술 부족으로 인해 전기 외과 기기 시장의 연평균 성장률(CAGR) 예측치는 1.1퍼센트 포인트 하향 조정되었습니다.
부문 분석
기기 및 부속품은 2025년 매출의 54.42%를 차지하며, 이 부문에서 전기 수술 기기 시장 규모를 38억 4,000만 달러로 뒷받침하고 있습니다. 일회용 양극성 겸자, 초음파 구동식 절단기 및 연기 흡입 펜슬은 계절적 수술 건수 변동을 완화하는 지속적인 매출을 창출하는 원동력이 되고 있습니다. 수술의 복잡성이 증가함에 따라, 열 센서가 내장되어 10밀리초 이내에 임피던스 데이터를 발전기로 전송하는 능동형 전극이 현재 주목받고 있습니다. 이러한 지능형 칩을 구매하는 병원은 일반적으로 독자적인 케이블 생태계에 묶이게 되며, 이는 브랜드 충성도를 더욱 공고히 하여 공급업체의 고객 생애 가치(LTV) 향상으로 이어지고 있습니다. 초음파 및 하이브리드 RF-초음파 블레이드는 기존의 단극 아크로 인해 신경 손상 위험이 있는 경구 및 로봇 보조 갑상선 절제술과 같은 틈새 시장에서 점유율을 확대되고 있습니다.
능동형 전극은 가장 빠르게 성장하는 하위 부문으로, 외과의들이 촉각 피드백과 누설 전력을 줄여주는 자동 정지 기능을 요구함에 따라 연평균 성장률(CAGR) 7.58%로 확대되고 있습니다. 전문용 액세서리 시장에서 전기 수술 기기의 점유율은 감염 관리 담당자들이 완전한 추적 가능성이 없는 재처리된 전극의 사용을 점점 더 금지하고 있기 때문에 센서가 탑재된 일회용 팁으로 전환될 것으로 예측됩니다. 발전기 수요는 견조한 추세를 보이고 있지만, 2016년 이전에 제조된 콘솔에는 현장에서 업그레이드 가능한 펌웨어 슬롯이 탑재되어 있지 않아 교체 주기가 가속화되고 있습니다. 한편, 연기 흡입용 캡처 패드가 통합된 액세서리 번들은 각 주의 ‘무연 수술실’ 의무화 요건을 충족하기 위해 미국 외래 진료 분야의 조달 절차를 빠르게 통과하고 있습니다.
일반외과는 2025년 매출의 30.25%를 차지하며, 표준화된 에너지 설정에 의존하는 충수 절제술, 탈장 수술, 담낭 절제술 등 광범위한 수술 사례를 반영하고 있습니다. 이러한 견고한 기반을 통해 선택적 정형외과 수술이나 미용 성형 수술 건수가 감소하더라도 예측 가능한 현금 흐름을 확보할 수 있습니다. 이와 동시에, 선택적 미용 성형 수술에 대한 수요 증가가 미용·성형외과 분야를 견인하고 있으며, 해당 분야는 연평균 성장률(CAGR) 7.92%로 견조한 추세를 보일 것으로 예측됩니다. 이 분야의 환자들은 흉터를 최소화하고 응고를 제어할 수 있는 점을 중요시하기 때문에 초음파 해부기나 미세한 끝부분을 가진 바이폴라 집게가 선호되는 기구입니다.
심혈관외과 및 뇌신경외과 팀은 핸드피스를 교체하지 않고도 1 MHz 바이폴라 실링에서 47 kHz 초음파 절개 모드로 전환할 수 있는 듀얼 모달리티 콘솔을 선호하여 채택하고 있습니다. 부인과 종양 전문의들은 복강경 자궁 적출술 시 장막 손상을 줄이기 위해 열 센서가 장착된 시어를 사용하고 있습니다. 다학제 팀이 단일의 모든 기능을 갖춘 발전기 플랫폼을 선호함에 따라, 하이브리드 전문 수술실에서 파생된 전기 수술 기기 시장 규모는 꾸준히 확대될 것으로 예측됩니다. 또한, 임플란트 삽입 전에 관절강을 최적화하기 위해 RF(고주파)를 이용한 피막 절개를 시행하는 정형외과 재수술도 향후 시술 건수 증가에 기여할 전망입니다.
지역별 분석
북미는 2025년 매출의 41.60%를 차지했습니다. 이는 미국 병원들이 견실한 보험 환급 제도와 광범위한 ASC(외래수술센터(ASC)) 네트워크를 활용하여 AI 지원 에너지 콘솔로 장비를 업그레이드했기 때문입니다. 캐나다의 단일 지불자 제도는 예산 제약 하에 있으며, 새로 제정된 산업 안전 기준을 충족하기 위해 통합형 연기 배출 시스템으로 업그레이드했습니다. 멕시코의 민간 병원은 의료 관광 경쟁력을 높이기 위해 고급 양극성·초음파 하이브리드 장비에 투자했습니다. 미국 내 공급망 현지화 지원으로 인해 인쇄 회로 기판 및 페라이트 코어의 리드타임이 단축되었으며, 이는 연방 정부의 회복탄력성 목표에 부합하는 것입니다.
아시아태평양은 가장 빠르게 성장하는 시장으로, 2031년까지 연평균 성장률(CAGR)이 8.55%를 나타낼 것으로 예측됩니다. 중국은 야심 찬 병원 현대화 추진 정책과 ‘중국 제조 2025’ 인센티브를 통해 국내 OEM 제조업체들이 대학과 공동으로 지능형 에너지 플랫폼을 개발하도록 장려하고 있으며, 이는 지역 수요를 뒷받침하고 있습니다. 세계에서 가장 급속한 고령화에 직면한 일본에서는 복강경 대장 절제술용 정밀 초음파 메스 시스템이 도입되고 있습니다. 인도의 민간 병원 체인은 국제 의료 관광객을 대상으로 투명한 일괄 가격으로 제공되는 턴키 수술 패키지에 전기 메스 타워를 포함시키고 있습니다. 호주와 한국은 증가하는 비만 수술 및 종양 수술 건수에 대응하기 위해 첨단 양극 실링 장치를 수입하고 있으며, 이로 인해 태평양 연안 지역 전체의 전기 메스 장치 시장 규모가 더욱 확대되고 있습니다.
유럽에서는 독일, 프랑스, 영국이 EU-MDR 문서화 관련 과제를 극복하며 수술실을 업그레이드하고 있어, 안정적인 한 자릿수 중반의 성장률을 기록하고 있습니다. 남유럽 국가들은 배연·배가스 여과 시스템 설비 구입 비용을 일부 보조하는 EU 부흥 기금의 혜택을 받고 있습니다. 데이터가 풍부한 수술 플랫폼을 조기에 도입한 북유럽 병원에서는 발전기에서 나오는 데이터 스트림을 국가 수술 품질 등록 제도에 통합하여, 근거 기반의 조달을 강화하고 있습니다. 동유럽 및 GCC(걸프협력회의) 국가들의 성장은 여전히 기회에 좌우되지만, 사우디아라비아의 ‘비전 2030’과 아랍에미리트(UAE)의 의료 프리존 내 대규모 인프라 계획이 프리미엄 에너지 플랫폼을 위한 새로운 길을 열어주고 있습니다. 남미와 아프리카는 현재로서는 합쳐서 미미한 점유율에 불과하지만, 보편적 의료 보장 확대가 진행됨에 따라 상승 잠재력을 지니고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the electrosurgical devices market size was valued at USD 7.05 billion in 2025 and estimated to grow from USD 7.48 billion in 2026 to reach USD 10.05 billion by 2031, at a CAGR of 6.09% during the forecast period (2026-2031).
This report is Segmented by Product (Electrosurgical Generators, Instruments and Accessories [Bipolar Instruments, and More], and More), by Application (General Surgery, Neurosurgery, and More), by Energy Modality (Monopolar Radio-Frequency, Bipolar Radio-Frequency, and More), by End User (Hospitals, Ambulatory Surgical Centers, and More), by Geography (North America, Europe, Asia-Pacific, and More).
Global Electrosurgical Devices Market Trends and Insights
Rise in Chronic Diseases & Ageing Population
Global longevity gains mean more poly-morbid patients entering operating rooms, and cardiovascular procedures alone are projected to climb sharply as diabetes incidence rises. Surgeons therefore require bipolar and ultrasonic platforms capable of controlled hemostasis inside fragile, comorbid tissue fields. Intelligent energy consoles deliver precise wattage adjustments that minimize thermal spread, easing concerns in elderly cohorts with limited physiologic reserve. The same demographic trend is escalating volume in joint-replacement revisions and oncologic resections, extending the addressable base of the electrosurgical devices market. Hospitals in North America and Western Europe are doubling down on generator upgrades that embed tissue-impedance monitoring so that any inadvertent rise in tissue temperature is recognized and corrected within milliseconds. Over the long term, the compounding effect of aging and chronic illness adds a 1.8 percentage-point tailwind to overall CAGR projections.
Minimally-Invasive Surgery Preference
Payers and providers increasingly rank shorter length of stay and faster return-to-work as prime value metrics. Laparoscopic, thoracoscopic and endoscopic approaches inherently depend on slim, low-heat instruments, which explains why advanced bipolar and ultrasonic shears dominate capital budgets for minimally invasive suites. Compact electrosurgical generators designed to dock under mobile towers free up valuable real estate inside crowded ORs. Micro-incision adoption in Asia-Pacific is now approaching growth curves once unique to the United States, broadening revenue potential for integrated smoke evacuation and temperature-controlled RF electrodes. A recent four-year economic model showed that temperature-controlled radiofrequency instruments yielded plan-level savings of USD 20 million and USD 3,531 per treated patient, reinforcing pay-for-value arguments.
Shortage of Skilled Electrosurgeons
Simulation-based curricula such as SAGES' FUSE program have improved knowledge scores, yet demand for fully credentialed electrosurgeons still outstrips supply. In low- and middle-income countries, many operating rooms lack proctorship, causing hospitals to delay generator upgrades until staff competencies rise. A 2023 observer-blinded study documented that residents' comfort performing Loop Electrosurgical Excision jumped only after 10 guided practice sessions, underscoring the steep learning curve. Skill scarcity subtracts 1.1 percentage points from the electrosurgical devices market CAGR forecast.
Other drivers and restraints analyzed in the detailed report include:
- Technology Shift to Intelligent Energy Platforms
- Outpatient Surgery Center Boom (ASC Build-Outs)
- Stringent Device Re-Certification (EU-MDR)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Instruments and Accessories delivered 54.42% of 2025 revenue, anchoring the electrosurgical devices market size at USD 3.84 billion for the category. Disposable bipolar forceps, ultrasonically activated shears and smoke evacuation pencils create a recurring sales flywheel that cushions seasonal procedure swings. Rising procedure complexity now favors active electrodes embedded with thermal sensors that relay impedance data to generators in under 10 milliseconds. Hospitals purchasing these intelligent tips typically lock into proprietary cable ecosystems, which further entrenches brand loyalty and drives higher lifetime account value for vendors. Ultrasonic and hybrid RF-ultrasonic blades are gaining in niche domains such as trans-oral and robotic thyroidectomy where traditional monopolar arcs risk nerve damage.
Active Electrodes represent the fastest-growing subsegment, advancing at a 7.58% CAGR as surgeons seek tactile feedback and auto-stop features that mitigate stray energy. The electrosurgical devices market share within specialty accessories is expected to tilt toward single-use, sensor-enabled tips because infection-control officers increasingly bar reprocessed electrodes without full traceability. Generator demand remains steady; however, consoles built before 2016 lack field-upgradable firmware slots, accelerating replacement cycles. Meanwhile, accessory bundles that integrate smoke evacuation capture pads are moving rapidly through U.S. outpatient procurement pipelines, fulfilling state smoke-free OR mandates.
General Surgery generated 30.25% of 2025 sales, reflecting the breadth of appendectomy, hernia, and cholecystectomy cases that rely on standardized energy settings. This considerable base underpins predictable cash flow even when elective orthopedic or cosmetic volumes dip. In parallel, rising elective aesthetics demand lifts Cosmetic & Plastic Surgery, which is projected to clip along at an 7.92% CAGR. Patients in this segment prioritize low scarring and controlled coagulation, making ultrasonic dissectors and fine-tip bipolar forceps the instruments of choice.
Cardiovascular and Neurosurgery teams gravitate toward dual-modality consoles able to switch from 1 MHz bipolar sealing to 47 kHz ultrasonic dissection without changing handpieces. Gynecologic oncologists adopt thermal-sensor shears to reduce serosal injury during laparoscopic hysterectomy. The electrosurgical devices market size derived from hybrid specialty suites is expected to climb steadily because cross-disciplinary teams prefer a single, fully featured generator platform. Future procedure growth will also derive from orthopedic revisions that use RF-based capsular release to optimize joint space before implant insertion.
Complete Report Scope:
- By Product
- Electrosurgical Generators
- Active Electrodes
- Instruments and Accessories
- Bipolar Instruments
- Monopolar Instruments
- Ultrasonic & Advanced Energy
- Accessories (Cables, Tips, Smoke Evac)
- By Application
- General Surgery
- Neurosurgery
- Gynecology Surgery
- Cardiovascular Surgery
- Orthopedic Surgery
- Cosmetic & Plastic Surgery
- Other Specialized Procedures
- By Energy Modality
- Monopolar Radio-frequency
- Bipolar Radio-frequency
- Ultrasonic
- Hybrid/Advanced Bipolar-Ultrasonic
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics & Offices
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America secured 41.60% of 2025 revenue as U.S. hospitals leveraged robust reimbursement schemes and an expansive ASC network to refresh fleets with AI-enabled energy consoles. Canada's single-payer system, under budget constraint, nonetheless upgraded to integrated smoke evacuation to meet newly enacted occupational safety standards. Mexico's private hospitals invested in premium bipolar-ultrasonic hybrids to boost medical-tourism competitiveness. Supply-chain localization grants in the United States are shortening lead times for printed circuit boards and ferrite cores, aligning with federal resilience goals.
Asia-Pacific is the fastest-growing theatre, posting an 8.55% CAGR forecast through 2031. China anchors regional demand thanks to an ambitious hospital-modernization drive and Made-in-China 2025 incentives that nudge domestic OEMs to co-develop intelligent energy platforms with universities. Japan, burdened by the world's most rapidly aging population, sources precision ultrasonic scalpel systems for laparoscopic colectomy. India's private hospital chains package electrosurgery towers within turnkey surgical bundles offered to international medical tourists at bundled, transparent pricing. Australia and South Korea import advanced bipolar sealing devices to tackle rising bariatric and oncologic surgery volumes, further expanding the electrosurgical devices market size across the Pacific Rim.
Europe registers stable, mid-single-digit growth as Germany, France and the United Kingdom upgrade OR suites while steering through EU-MDR documentation hurdles. Southern European countries benefit from EU recovery funds that partially subsidize capital purchases of smoke evacuation and plume filtration systems. Nordic hospitals, early adopters of data-rich surgical platforms, integrate generator data streams into national surgical quality registries, reinforcing evidence-based procurement. Eastern European and GCC growth remains opportunistic; however, large infrastructure programs in Saudi Arabia's Vision 2030 and the United Arab Emirates' medical free-zones are opening fresh avenues for premium energy platforms. South America and Africa collectively contribute a modest share today but hold upside potential as universal healthcare expansions unfold.
- Medtronic
- Johnson & Johnson
- Olympus
- Conmed
- B. Braun
- Boston Scientific
- Stryker
- Smiths Group
- Applied Medical Resources
- Erbe Elektromedizin
- Kirwan Surgical Products
- Symmetry Surgical Inc. (Aspen Surgical Products, Inc.)
- Apyx Medical
- Utah Medical Products
- KLS Martin Group
- De Soutter Medical Ltd.
- Teleflex
- Steris plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in chronic diseases & ageing population
- 4.2.2 Minimally-invasive surgery preference
- 4.2.3 Technology shift to intelligent energy platforms
- 4.2.4 Outpatient surgery center boom (ASC build-outs)
- 4.2.5 AI-guided tissue sensing for precision cutting
- 4.2.6 Supply-chain localization incentives (USA, EU)
- 4.3 Market Restraints
- 4.3.1 Shortage of skilled electrosurgeons
- 4.3.2 Stringent device re-certification (EU-MDR)
- 4.3.3 Thermal injury litigation risk spike
- 4.3.4 Rare-earth & tungsten price volatility
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product
- 5.1.1 Electrosurgical Generators
- 5.1.2 Active Electrodes
- 5.1.3 Instruments and Accessories
- 5.1.3.1 Bipolar Instruments
- 5.1.3.2 Monopolar Instruments
- 5.1.3.3 Ultrasonic & Advanced Energy
- 5.1.3.4 Accessories (Cables, Tips, Smoke Evac)
- 5.2 By Application
- 5.2.1 General Surgery
- 5.2.2 Neurosurgery
- 5.2.3 Gynecology Surgery
- 5.2.4 Cardiovascular Surgery
- 5.2.5 Orthopedic Surgery
- 5.2.6 Cosmetic & Plastic Surgery
- 5.2.7 Other Specialized Procedures
- 5.3 By Energy Modality
- 5.3.1 Monopolar Radio-frequency
- 5.3.2 Bipolar Radio-frequency
- 5.3.3 Ultrasonic
- 5.3.4 Hybrid/Advanced Bipolar-Ultrasonic
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Specialty Clinics & Offices
- 5.4.4 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Medtronic plc
- 6.3.2 Johnson & Johnson (Ethicon)
- 6.3.3 Olympus Corporation
- 6.3.4 CONMED Corporation
- 6.3.5 B. Braun SE
- 6.3.6 Boston Scientific Corporation
- 6.3.7 Stryker Corporation
- 6.3.8 Smith & Nephew plc
- 6.3.9 Applied Medical Resources Corp.
- 6.3.10 ERBE Elektromedizin GmbH
- 6.3.11 Kirwan Surgical Products LLC
- 6.3.12 Symmetry Surgical Inc. (Aspen Surgical Products, Inc.)
- 6.3.13 Apyx Medical Corporation
- 6.3.14 Utah Medical Products Inc.
- 6.3.15 KLS Martin Group
- 6.3.16 De Soutter Medical Ltd.
- 6.3.17 Teleflex Incorporated
- 6.3.18 Steris plc
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment