

|
시장보고서
상품코드
2121410
방사선 탐지, 모니터링 및 안전 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Radiation Detection, Monitoring, And Safety - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
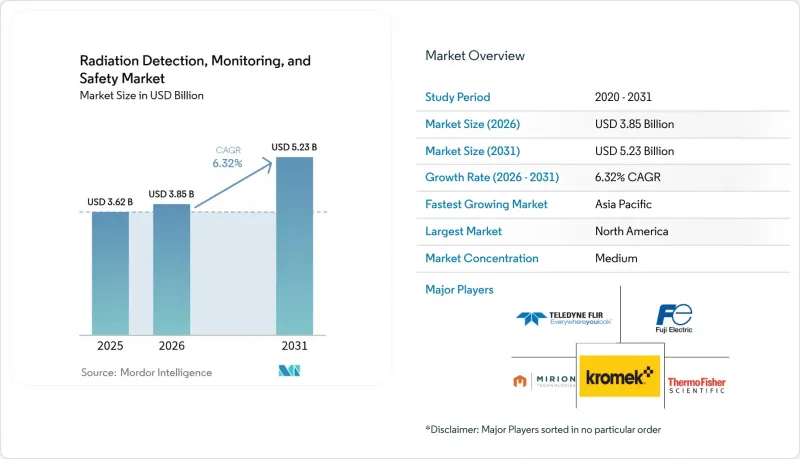
에 의하면, 2026년 방사선 탐지, 모니터링 및 안전 시장 규모는 38억 5,000만 달러로 추정되고, 2025년 36억 2,000만 달러에서 확대해, 2031년에는 52억 3,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 6.32%로 성장할 것으로 전망됩니다.
본 보고서는 제품 유형별(탐지, 모니터링 및 안전), 감지 기술별(가스 충전형, 신틸레이션 등), 최종 사용자 산업별(의료 및 헬스케어, 에너지 및 전력, 국토안보·국방, 산업 등), 지역별(북미, 남미, 유럽 등)로 세분화되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 방사선 탐지, 모니터링 및 안전 시장 동향 및 인사이트
암 및 만성 질환 발생률 증가
암 유병률은 2050년까지 전 세계적으로 3,500만 건에 달할 것으로 예상되며, 이에 따라 정밀 선량 측정 시스템의 대상 시장이 확대되고 있습니다. 현재 방사선 치료 분야에서는 1밀리초 미만의 빔 모니터링 정밀도가 요구되고 있으며, 선량률의 고주파 변동을 포착할 수 있는 반도체 검출기가 선호되고 있습니다. 적응형 치료 계획 플랫폼으로 인해 데이터 생성량이 증가하고 있으며, 임상의들은 분할 선량을 조정하기 위해 실시간 피드백 루프를 점점 더 많이 활용하고 있습니다. 이에 따라 의료 기관에서는 다중 채널 선량 검증 랙, 이중화된 필드 캘리브레이터, 클라우드 기반 선량 등록 소프트웨어에 대한 예산을 편성하고 있으며, 이러한 생태계가 방사선 탐지, 모니터링 및 안전 시장을 확대시키고 있습니다. 벤더들의 전략은 선형 가속기의 가동 시간을 향상시키는 모듈식 검출기 헤드와 AI를 활용한 품질 보증(QA) 대시보드에 중점을 두고 있습니다.
확대되는 핵의학 및 방사선 치료 시술
2024년, 악티늄 225 및 루테튬 177과 같은 세라노스틱 동위원소의 주도하에 핵의학 검사 건수는 전년 대비 12% 증가했습니다. 방사성 의약품 허브에서는 공기 중 알파 입자 모니터, 핫셀용 감마선 분광계, 시설의 LIMS 데이터베이스와 자동으로 동기화되는 개인용 선량계가 필요합니다. 환자층과 가까운 곳에 배치된 분산형 사이클로트론 네트워크로 인해, 차폐 캐비닛, 제염 포털, 누출 테스트 키트의 조달 거점이 증가하고 있습니다. 미국 FDA의 21 CFR Part 361에 따른 표준화로 인해 동위원소별 교정 프로토콜이 의무화되었으며, 이로 인해 검출기 재교정 서비스 제공업체에게 지속적인 아웃소싱 기회가 확보되고 있습니다. 이러한 동향은 ASP(평균 판매 가격)를 끌어올리고 애프터마켓의 수익 전망을 확대시킬 것입니다.
여러 관할 구역에 걸친 엄격한 규정 준수 부담
검출기 OEM 제조업체는 FDA 510(k) 신청 서류 승인 획득, IEC 60601-2-45의 성능 지표 달성, CE 마크 적합성 획득이 요구되며, 각각에 대해 개별적인 생체적합성 시험, EMC 시험, 방사선 패턴 시험이 필요합니다. 문서 작성만으로도 연구개발 예산이 불어나, 소규모 혁신 기업들을 라이선싱이나 틈새 학술 시장으로 몰아내고 있습니다. 병행되는 인증 절차는 실제 도입된 기기가 여러 국가에서 운영되게 되면 펌웨어의 신속한 업데이트를 방해하고 기능 배포를 지연시킵니다. 그 결과, 설계 채택까지의 주기가 4년을 넘을 정도로 장기화되어 신기술 투자에 대한 순현재가치(NPV)가 희석될 뿐만 아니라, 방사선 탐지, 모니터링 및 안전 시장에서의 단기적인 수익 확대 기세도 둔화되고 있습니다.
부문별 분석
감지 및 모니터링 시스템은 2025년 매출의 50.74%를 차지했으며, 선량 조건을 지속적으로 검증해야 하는 병원, 유틸리티체 및 국방 기관의 조달 예산의 기반을 이루고 있습니다. 방사선 탐지, 모니터링 및 안전 시장 규모 측면에서 감지 플랫폼은 예방적 유지보수 주기를 권장하는 예측 분석 모듈과 함께 성장할 것으로 예측됩니다. 납 차폐복, 제염 부스, 자동 봉쇄 도어 등을 포함한 안전 장비는 ISO 2919 보호 장비 표준의 조화에 힘입어 연평균 성장률(CAGR) 7.55%로 과거 평균을 상회하는 속도로 성장하고 있습니다. 실시간 감마선 프로브와 전동 차폐 커튼을 통합한 솔루션은 경보 발생부터 격리까지의 시간을 단축하고, ALARA(합리적으로 달성 가능한 최저 수준) 준수를 향상시킵니다. 각 벤더사는 교차 판매를 통한 시너지 효과를 활용하고 있습니다. 예를 들어, 신틸레이션 프로브를 주문하는 병원에서는 배지형 선량계 구독을 함께 계약하는 경우가 많으며, 원자로 운영 사업자에서는 주변 포털형 선량계와 쉘터 인 플레이스용 환기 시스템을 세트로 판매하고 있습니다. 규제상의 의무로 인해 조달의 시급성이 높아지고 있으므로 가격 탄력성은 여전히 제한적이며, 이로 인해 방사선 탐지, 모니터링 및 안전 업계 전반에서 프리미엄 SKU의 안정적인 판매가 보장되고 있습니다.
클라우드 대시보드의 기능 확장, 지오태그가 포함된 경보의 시각화, 역할 기반 접근 제어, 규정 준수 보고서의 자동 생성을 통해 감지 장비는 단순한 범용 제품의 범주를 넘어섰습니다. SaaS 오버레이는 상당한 매출 총이익률을 가져다주며, 하드웨어의 이익률을 상회하고 있어 하드웨어에 의존하지 않는 생태계 형성을 촉진하고 있습니다. 그 결과, 채널 파트너들은 NaI(Tl), CZT, 중성자 모듈을 하나의 모니터링용 HMI로 통합하는 멀티 프로토콜 게이트웨이의 재고를 선호하게 되었습니다. 실시간 분석을 통해 오감지 발생이 더욱 감소하여 비용이 많이 드는 대피 조치의 발생을 억제합니다. 이러한 고부가가치 솔루션은 보다 광범위한 방사선 감지·모니터링·안전 시장에서 감지 솔루션의 선도적 입지를 강화하고 있습니다.
지역별 분석
북미는 2025년에도 매출액 기준 30.05%로 1위를 유지했습니다. 이는 확고히 자리 잡은 원자력 발전소 군, 광범위한 국토 안보 인프라, 그리고 조기 도입이 진행되고 있는 의료 시스템을 반영한 것입니다. 미국의 국립 연구소는 CZT 검출기의 소형화를 위한 연구 개발 보조금을 지원하고 있으며, 한편 캐나다 NRCan(캐나다 천연자원부)의 틀 내에서 연구용 원자로의 환경 모니터링 업그레이드에 대한 보조금을 지원하고 있습니다. 멕시코에서의 방사성 의약품 수출 확대는 동위원소 생산용 핫셀 모니터에 대한 수요를 더욱 부추기고 있습니다. ANSI N42에 기반한 국경을 초월한 표준화를 통해 장비의 상호 운용성이 향상되었으며, 그 결과 해당 지역의 방사선 탐지, 모니터링 및 안전 시장에서 규모의 경제가 강화되고 있습니다.
아시아태평양은 2060년까지 150기의 원자로를 가동하겠다는 중국의 계획에 힘입어 연평균 성장률(CAGR) 8.05%라는 가장 빠른 성장 궤도를 기록하고 있습니다. 베이징의 ‘중국 제조 2025’ 정책에 포함된 현지 생산 의무화로 인해 CZT 웨이퍼 합작 제조 공장이 촉진되고, 수입 관세가 인하되며, 공급망의 취약성이 완화되고 있습니다. 일본의 후쿠시마 제1원전 사고 이후 규제 체제에서는 원자로 부지 주변 20km에 이르는 감마선 측정 네트워크 구축에 자금이 투입되고 있는 반면, 인도의 원자력부는 2급 도시의 암 치료 병동을 대상으로 저비용 방사선 측정기에 자금을 지원하고 있습니다. 한국에서는 18 MeV 사이클로트론 네트워크의 확대에 따라 대상 병원 수가 더욱 증가하고 있으며, 방사선 탐지, 모니터링 및 안전 시장에서 아시아태평양의 위상이 세계의 성장 동력으로서 더욱 공고해지고 있습니다.
유럽에서는 독일, 벨기에, 스페인의 원전 해체 프로젝트가 공기 중 알파선 모니터 및 폐기물 드럼 분석 시스템에 대한 전문적인 수요를 창출하며 균형 잡힌 성장을 보이고 있습니다. 원자력 발전 비중이 높은 프랑스에서는 ASN의 엄격한 지진 위험 기준을 충족해야 하는 운전 기간 연장 개보수에 주력하고 있습니다. 유로톰(Eurotom) 조약에 따라 조달 사양이 표준화되어, 다년간의 예산 주기를 활용한 국경을 초월한 대규모 계약이 가능해졌습니다. 중동유럽 국가들에서는 소련 시대의 연구용 원자로 현대화가 진행되고 있으며, 교육 서비스가 패키지화된 턴키 방식의 검출 시스템이 요구되고 있습니다.
아프리카은 아직 발전 단계에 있지만, 전략적 항구에 중성자 화물 스캐너를 도입하고 사이클로트론을 이용한 방사성 의약품 연구소의 가동을 시작함으로써, 신흥 지역의 방사선 탐지, 모니터링 및 안전 시장의 중기적 성장 조짐을 보이고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the radiation detection, monitoring, and safety market size in 2026 is estimated at USD 3.85 billion, growing from 2025 value of USD 3.62 billion with 2031 projections showing USD 5.23 billion, growing at 6.32% CAGR over 2026-2031.
This report is Segmented by Product Type (Detection and Monitoring and Safety), Detector Technology (Gas-Filled, Scintillation, and More), End-User Industry (Medical and Healthcare, Energy and Power, Homeland Security and Defence, Industrial, and More), and Geography (North America, South America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Radiation Detection, Monitoring, And Safety Market Trends and Insights
Rising Incidence of Cancer and Chronic Diseases
Cancer prevalence is climbing toward 35 million global cases by 2050, enlarging the addressable base for precision dosimetry systems.Radiotherapy departments now specify sub-millisecond beam-monitoring accuracy, favoring semiconductor detectors that capture high-frequency fluctuations in dose rate. Adaptive treatment planning platforms amplify data-generation volumes, and clinicians increasingly rely on real-time feedback loops to tune fractionated doses. Health systems, therefore, budget for multi-channel dose-verification racks, redundant field calibrators, and cloud-hosted dose-registry software, an ecosystem that broadens the radiation detection, monitoring, and safety market. Vendor strategies focus on modular detector heads and AI-assisted QA dashboards that enhance linear-accelerator uptime.
Expanding Nuclear Medicine and Radiotherapy Procedures
Nuclear medicine examinations grew 12% year-over-year in 2024, propelled by theranostic isotopes such as actinium-225 and lutetium-177.Radiopharmaceutical hubs require air-borne alpha-particle monitors, hot-cell gamma spectrometers, and personal dosimeters that auto-synchronize with facility LIMS databases. Decentralized cyclotron networks, positioned closer to patient populations, multiply procurement nodes for shielding cabinets, de-contamination portals, and leak-testing kits. Standardization under U.S. FDA 21 CFR Part 361 obliges isotope-specific calibration protocols, ensuring recurring outsourcing opportunities for detector-recalibration service providers. These trends elevate ASPs (average selling prices) and extend aftermarket revenue visibility.
Stringent Multi-Jurisdictional Compliance Burden
Detector OEMs must clear FDA 510(k) dossiers, satisfy IEC 60601-2-45 performance metrics, and attain CE marking conformity, each requiring discrete biocompatibility, EMC, and radiation pattern tests. Documentation alone inflates research and development budgets, steering smaller innovators toward licensing deals or niche academic markets. Parallel certification tracks hinder agile firmware updates once fielded devices enter multi-country footprints, slowing feature rollouts. The result is elongated design-win cycles that can exceed four years, diluting NPV on new technology investments and tempering near-term revenue acceleration within the radiation detection, monitoring, and safety market.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Real-Time Environmental Monitoring
- Miniaturization and IoT-Enabled Dosimeters
- Shortage of Certified Radiation Safety Officers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Detection and monitoring systems generated 50.74% of 2025 revenue, anchoring procurement budgets for hospitals, utilities, and defense agencies that must continuously validate dose conditions. Within the radiation detection, monitoring, and safety market size, detection platforms are projected to grow alongside predictive analytics modules that recommend proactive maintenance intervals. Safety equipment, encompassing lead-lined apparel, decontamination booths, and automated containment doors, is outpacing historical norms with a 7.55% CAGR, buoyed by harmonized ISO 2919 protective device standards. Integrated offerings that unite real-time g-ray probes with motorized shielding curtains shorten alarm-to-containment times and improve ALARA (as low as reasonably achievable) compliance. Vendors leverage cross-selling synergies: hospitals ordering scintillation probes often append badge-dosimetry subscriptions, while reactor operators bundle perimeter portals with shelter-in-place ventilation systems. Price elasticity remains modest, as regulatory obligations heighten procurement urgency, ensuring premium SKUs maintain a steady pull-through across the radiation detection, monitoring, and safety industry.
The expanded functionality of cloud dashboards, geo-tagged alarm visualization, role-based access, and automated compliance report generation pushes detection gear beyond commodity status. SaaS overlays carry significant gross margin, outstripping hardware rates and encouraging hardware-agnostic ecosystems. Consequently, channel partners favor stocking multi-protocol gateways that integrate NaI(Tl), CZT, and neutron modules under one supervisory HMI. Real-time analytics further reduces false-positive occurrences, trimming costly evacuation incidents. Such value-added solutions reinforce the leadership of detection solutions within the broader radiation detection, monitoring, and safety market.
Complete Report Scope:
- By Product Type
- Detection and Monitoring
- Safety
- By Detector Technology
- Gas-Filled (Geiger-Muller, Proportional, Ion-Chambers)
- Scintillation (NaI(Tl), CsI, LaBr3, Plastic)
- Semiconductor (HPGe, CZT, SiPM)
- Personal Dosimeters (TLD, OSL, Electronic)
- By End-user Industry
- Medical and Healthcare
- Energy and Power (Nuclear, Conventional)
- Homeland Security and Defence
- Industrial (Oil and Gas, Mining, Manufacturing)
- Research and Academic Laboratories
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained a 30.05% revenue lead in 2025, reflecting entrenched nuclear-power fleets, extensive homeland-security infrastructures, and early-adopter healthcare systems. U.S. national laboratories are funneling research and development grants into CZT detector miniaturization, while the Canadian NRCan framework is subsidizing environmental-monitoring upgrades at research reactors. Mexico's expanding radiopharmaceutical exports add incremental volume for isotope-production hot-cell monitors. Cross-border standardization under ANSI N42 enhances equipment interoperability, thereby reinforcing economies of scale within the regional radiation detection, monitoring, and safety market.
Asia-Pacific records the fastest trajectory at an 8.05% CAGR, underwritten by China's plan to commission 150 reactors before 2060. The localization mandate embedded in Beijing's Made-in-China 2025 policy promotes joint-venture fabrication plants for CZT wafers, reducing import tariffs and mitigating supply-chain fragility. Japan's post-Fukushima regulatory regime finances perimeter gamma-ray meshes extending 20 km around reactor sites, while India's Department of Atomic Energy funds low-cost survey meters for cancer-therapy wards in tier-two cities. South Korea's expanding 18-MeV cyclotron network further widens the addressable hospital count, reinforcing the Asia-Pacific region's status as the global growth engine for the radiation detection, monitoring, and safety market.
Europe exhibits balanced growth as decommissioning projects in Germany, Belgium, and Spain create specialized demand for alpha-in-air monitors and waste-drum assay systems. France, maintaining a strong nuclear-electricity share, focuses on life-extension upgrades that must meet ASN's stringent seismic-risk criteria. The Euratom treaty standardizes procurement specifications, enabling cross-border volume contracts that leverage multi-year budget cycles. Central and Eastern European nations, modernizing Soviet-era research reactors, seek turnkey detection suites bundled with training services.
The Middle East and Africa, although nascent, are deploying neutron-cargo scanners at strategic ports and commissioning cyclotron-based radiopharmacy labs, foreshadowing medium-term momentum for the radiation detection, monitoring, and safety market in emerging geographies.
- Mirion Technologies Inc.
- Thermo Fisher Scientific Inc.
- Teledyne FLIR LLC
- Fuji Electric Co., Ltd.
- Unfors RaySafe AB
- Arktis Radiation Detectors Ltd.
- Kromek Group plc
- Berthold Technologies GmbH & Co. KG
- Alpha-Spectra, Inc.
- Radiation Detection Company
- Centronic Ltd.
- Burlington Medical LLC
- Amray Group Ltd.
- Atomtex SPE
- Polimaster Ltd.
- Smiths Detection Group Ltd.
- Ludlum Measurements, Inc.
- Hitachi-Aloka Medical, Ltd.
- General Atomics Electronic Systems
- Else Nuclear s.r.l.
- Silena Group s.r.l.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising incidence of cancer and chronic diseases
- 4.2.2 Expanding nuclear medicine and radiotherapy procedures
- 4.2.3 Regulatory push for real-time environmental monitoring
- 4.2.4 Miniaturisation and IoT-enabled dosimeters
- 4.2.5 UAV-based wide-area radiation mapping
- 4.2.6 De-commissioning of ageing nuclear reactors worldwide
- 4.3 Market Restraints
- 4.3.1 Stringent multi-jurisdictional compliance burden
- 4.3.2 Shortage of certified radiation safety officers
- 4.3.3 High capex for spectroscopic-grade detectors
- 4.3.4 Supply-chain volatility for He-3 and scintillator crystals
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Detection and Monitoring
- 5.1.2 Safety
- 5.2 By Detector Technology
- 5.2.1 Gas-Filled (Geiger-Muller, Proportional, Ion-Chambers)
- 5.2.2 Scintillation (NaI(Tl), CsI, LaBr3, Plastic)
- 5.2.3 Semiconductor (HPGe, CZT, SiPM)
- 5.2.4 Personal Dosimeters (TLD, OSL, Electronic)
- 5.3 By End-user Industry
- 5.3.1 Medical and Healthcare
- 5.3.2 Energy and Power (Nuclear, Conventional)
- 5.3.3 Homeland Security and Defence
- 5.3.4 Industrial (Oil and Gas, Mining, Manufacturing)
- 5.3.5 Research and Academic Laboratories
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 Spain
- 5.4.3.4 Russia
- 5.4.3.5 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Egypt
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global overview, Market overview, Core Segments, Financials, Strategic Info, Market Share, Products and Services, Recent Developments)
- 6.4.1 Mirion Technologies Inc.
- 6.4.2 Thermo Fisher Scientific Inc.
- 6.4.3 Teledyne FLIR LLC
- 6.4.4 Fuji Electric Co., Ltd.
- 6.4.5 Unfors RaySafe AB
- 6.4.6 Arktis Radiation Detectors Ltd.
- 6.4.7 Kromek Group plc
- 6.4.8 Berthold Technologies GmbH & Co. KG
- 6.4.9 Alpha-Spectra, Inc.
- 6.4.10 Radiation Detection Company
- 6.4.11 Centronic Ltd.
- 6.4.12 Burlington Medical LLC
- 6.4.13 Amray Group Ltd.
- 6.4.14 Atomtex SPE
- 6.4.15 Polimaster Ltd.
- 6.4.16 Smiths Detection Group Ltd.
- 6.4.17 Ludlum Measurements, Inc.
- 6.4.18 Hitachi-Aloka Medical, Ltd.
- 6.4.19 General Atomics Electronic Systems
- 6.4.20 Else Nuclear s.r.l.
- 6.4.21 Silena Group s.r.l.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


