|
시장보고서
상품코드
2121479
유럽의 마케팅 자동화 소프트웨어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Marketing Automation Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
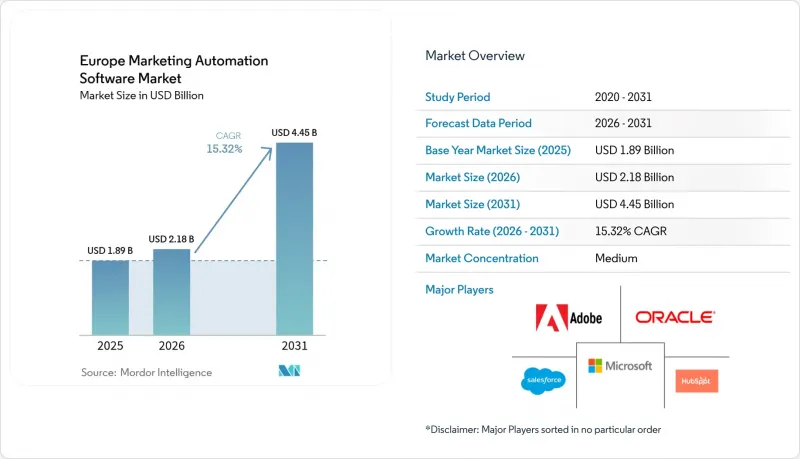
에 의하면, 유럽의 마케팅 자동화 소프트웨어 시장 규모는 2025년에 18억 9,000만 달러로 평가되었고, 2026년 21억 8,000만 달러에서 2031년까지 44억 5,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 15.32%를 기록할 전망입니다.
(1) 유럽연합 집행위원회, ‘디지털 유럽 프로그램’,europa.eu 2030년까지 클라우드 도입률 75%를 목표로 하는 EU의 디지털 단일 시장에 관한 지속적인 정책과, 79억 유로(85억 5,000만 달러) 규모의 ‘디지털 유럽 프로그램’은 중소기업의 SaaS 도입에 대한 지원을 통해 단기적인 시장 확대를 뒷받침하고 있습니다. 본 보고서는 구성 요소(소프트웨어, 서비스), 도입 형태(클라우드 기반, On-Premise형), 조직 규모(중소기업, 대기업), 채널/기능(이메일 마케팅, 소셜 미디어 마케팅, 캠페인 관리 등), 최종 사용자 산업(소매 및 전자상거래, BFSI 등) 및 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 단위로 제시되어 있습니다.
유럽의 마케팅 자동화 소프트웨어 시장 동향 및 인사이트
DACH 및 북유럽 국가의 전자상거래 분야에서 AI를 활용한 개인화의 급증으로 시장이 견인되고 있습니다.
AI 기반 엔진은 DACH 및 북유럽의 소매 업계에 널리 보급되어 있으며, 경영진의 65%가 2025년에 AI를 핵심 성장 동력으로 꼽고 있습니다. 마케팅 담당자들은 이 지역들이 보유한 선진적인 클라우드 인프라와 높은 데이터 공유 동의율을 활용하여 전환율을 향상시키는 추천 모델을 전개하고 있습니다. Telmore사는 AI 기반 개인화를 도입한 후 매출이 11% 증가한 것으로 나타났으며, 이는 동종 업계의 도입을 가속화할 수 있는 정량화 가능한 ROI를 보여줍니다. 기업의 80%가 AI 예산 증액을 계획하고 있는 반면, ROI를 입증한 기업은 고작 12%에 그치고 있어, 강력한 측정 프레임워크를 갖춘 조기 도입 기업들이 경쟁 우위를 점하고 있습니다. 독일의 실무 담당자들은 생성형 AI를 활용해 캠페인 제작 및 보고서 작성을 효율화하고, 반복적인 업무를 줄여 직원을 분석 업무에 재배치하고 있습니다. 그 결과, DACH 및 북유럽은 이후 유럽 전역으로 확산될 차세대 개인화 기능의 테스트베드 역할을 수행하고 있습니다.
EU의 디지털 단일 시장 이니셔티브가 중소기업의 SaaS 도입을 뒷받침
79억 유로(85억 5,000만 달러) 규모의 ‘디지털 유럽 프로그램’은 클라우드 규제의 조화를 도모하고, 실질적인 지침을 제공하는 ‘유럽 디지털 혁신 허브’에 자금을 지원함으로써 중소기업 시장 진입 장벽을 낮추고 있습니다. 표준화된 API는 데이터 이식성을 향상시키고, 서로 다른 마케팅 용도 간의 통합을 용이하게 하며, 벤더 종속 위험을 완화합니다. EU 기업의 클라우드 도입률은 41%이며, 2030년까지 75%에 달할 전망입니다. 이는 SaaS 기반 마케팅 자동화 솔루션에 있어 대규모 신규 고객층 확보로 이어질 것입니다. 이러한 정책적 호재 덕분에 중견 기업 구매자들에게 있어 규정 준수 관련 복잡성이 완화되면서, 유럽의 마케팅 자동화 소프트웨어 시장의 잠재 수요가 확대되고 있습니다.
GDPR(EU 개인정보보호규정)에 정통한 마케팅 자동화 아키텍트 부족
마테크에 대한 전문 지식과 법적 식견을 겸비한 전문가는 극히 일부에 불과하기 때문에 도입 프로젝트가 정체되는 사례가 늘고 있습니다. 2007년부터 2022년까지 기존 은행 업무 분야의 고용이 21% 감소함에 따라, 은행 업계의 인력 재편은 데이터 전문가를 둘러싼 업계 전반에 걸친 경쟁을 부각시키고 있습니다. 중소기업은 특히 큰 영향을 받고 있으며, 외부 매니지드 서비스에 대한 의존도가 높아지고 있습니다. 이것이 서비스 분야의 연평균 성장률(CAGR)이 16.1%에 달하는 이유입니다. 유럽의 디지털 혁신 허브가 운영하는 인증 제도가 일조하고 있지만, 단기적인 인력 부족이 소규모 경제권에서의 도입을 제약하고 있습니다.
부문 분석
2025년에도 소프트웨어는 유럽의 마케팅 자동화 소프트웨어 시장 매출의 71.30%를 계속 차지했으나, 매니지드 서비스는 2031년까지 연평균 성장률(CAGR)이 15.92%로 더 높아져, 기업들이 규정 준수 관련 전문 지식을 외부에 위탁하는 경향을 드러냈습니다. 서비스의 급증은 기업들이 기술적 실행과 규제적 검증을 핵심 기능만큼 중요하게 여기고 있음을 보여줍니다. 소프트웨어 분야에서는 데이터 개인정보 보호 감사 및 AI 모델 거버넌스에서 ‘단일 신뢰할 수 있는 정보원’을 원하는 구매자 수요로 인해 통합 제품군이 독립형 도구를 앞지르고 있습니다. 전문 서비스는 레거시 시스템 통합 및 GDPR(EU 개인정보보호규정) 격차 분석을 주축으로 번창하고 있으며, 컨설팅 회사와 시스템 통합사업자가 벤더 선정의 관문 역할을 하는 입지를 확고히 하고 있습니다.
AI 법에 따른 감독 강화로 인해, 설계 단계부터 감사 가능성을 내재한 솔루션 청사진이 중요시되고 있습니다. 각 벤더는 패키지 소프트웨어와 자문 계약을 결합하여 연금형 수익을 창출하고 있습니다. 따라서 유럽의 마케팅 자동화 소프트웨어 업계에서는 GDPR(EU 개인정보보호규정), PSD2 및 업계 고유의 규제 요건을 아우르는 역동적인 규칙 세트에 대응하기 위해, 소프트웨어의 수익성과 종합적인 서비스가 결합된 하이브리드 비즈니스 모델이 등장할 것으로 보입니다.
2025년, 유럽의 마케팅 자동화 소프트웨어 시장에서 클라우드 솔루션이 77.20%의 점유율을 차지했습니다. 이는 주권적이고 신뢰할 수 있는 클라우드 프레임워크에 대한 EU의 지원에 힘입은 결과입니다. 플랫폼의 지속적인 업데이트를 통해 고객은 자본 지출의 급증 없이 새로운 데이터 처리 의무를 준수할 수 있으므로, 클라우드 도입은 연평균 성장률(CAGR) 15.62%로 확대되고 있습니다. 마케팅 팀은 탄력적인 컴퓨팅을 활용하여 AI 모델을 실행하고, 고객 경험을 실시간으로 개인화하는 이점을 누리고 있습니다. On-Premise 환경이 유지되는 경우는 공공 부문이나 국방 관련 고객이 엄격한 데이터 거주 요건을 요구하는 경우로 한정됩니다.
규제 당국은 자동화된 동의 기록, 정보 유출 통지 및 암호화 관리를 지원하는 클라우드의 중앙 관리 체계를 선호합니다. 이러한 규제 준수는 인식되는 위험을 완화하고, 더 광범위한 클라우드 전환을 촉진하고 있습니다. EU를 위한 안전한 클라우드 리전을 구축하기 위한 Oracle과 파란티아의 제휴와 같은 사례는 하이퍼스케일 제공업체들이 주권 관련 요구 사항을 충족하기 위해 스택을 어떻게 현지화하고 있는지를 보여줍니다. 도입이 성숙해짐에 따라 클라우드 벤더들은 제로 트러스트 아키텍처나 사전 인증된 AI 샌드박스와 같은 부가가치 계층에서 경쟁을 펼칠 것입니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the Europe marketing automation software market size was valued at USD 1.89 billion in 2025 and estimated to grow from USD 2.18 billion in 2026 to reach USD 4.45 billion by 2031, at a CAGR of 15.32% during the forecast period (2026-2031).
[1] European Commission, "The Digital Europe Programme," europa.eu Ongoing EU Digital Single Market measures that target 75% cloud adoption by 2030, together with the EUR 7.9 billion (USD 8.55 billion) Digital Europe Programme, underpin near-term expansion by subsidizing SaaS adoption among small and medium-sized enterprises. This report is Segmented by Component (Software, Services), Deployment Mode (Cloud-Based, On-Premise), Organisation Size (Small and Medium Enterprises, Large Enterprises), Channel / Function (Email Marketing, Social Media Marketing, Campaign Management, and More), End-User Industry (Retail and E-Commerce, BFSI, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Marketing Automation Software Market Trends and Insights
AI-Powered Personalisation Surge in DACH and Nordics E-commerce Drives the Market
AI-enabled engines have permeated DACH and Nordic retail, with 65% of executives naming AI a core growth lever in 2025. Marketers exploit the regions' advanced cloud infrastructure and high data-sharing consent rates to roll out recommendation models that elevate conversion. Telmore recorded an 11% uplift in sales after adopting AI-driven personalization, illustrating quantifiable ROI that accelerates peer adoption. As 80% of companies earmark higher AI budgets yet only 12% prove ROI, early adopters with strong measurement frameworks gain competitive distance. German practitioners use generative AI to streamline campaign production and reporting, cutting repetitive tasks and redeploying staff toward analytics. Consequently, the DACH-Nordic corridor functions as a test bed for next-wave personalization capabilities that subsequently diffuse across Europe.
EU Digital Single-Market Initiatives Boosting SME SaaS Uptake
The EUR 7.9 billion (USD 8.55 billion) Digital Europe Programme lowers barriers for SMEs by harmonizing cloud regulations and funding European Digital Innovation Hubs that provide hands-on guidance. Standardized APIs improve data portability, easing integration among disparate marketing applications and mitigating vendor lock-in risks. Cloud adoption among EU enterprises stands at 41% and is slated to reach 75% by 2030, translating into a sizeable new customer pool for SaaS-based marketing automation. These policy tailwinds curtail compliance complexity for mid-market buyers and amplify addressable demand within the Europe marketing automation software market.
Scarcity of GDPR-Fluent Marketing-Automation Architects
Implementation projects increasingly stall because only a narrow cadre of professionals combines martech proficiency with legal insight. Banking workforce realignment illustrates cross-industry competition for data specialists after a 21% employment contraction in traditional roles between 2007 and 2022. SMEs are disproportionately affected, leading to a reliance on external managed services, which explains their 16.1% CAGR within the services component. Certification initiatives by European Digital Innovation Hubs provide relief, but near-term talent gaps constrain uptake within smaller economies.
Other drivers and restraints analyzed in the detailed report include:
- Account-Based Marketing Adoption in B2B Tech Hubs Drives the Market
- Open-Banking API Integration in European Financial Services Drives the Market
- High TCO for Multi-Language Personalisation Modules
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software continued to generate 71.30% of Europe marketing automation software market revenue in 2025, though managed services outpaced with a 15.92% CAGR to 2031, underscoring corporates' preference for outsourced compliance know-how. The services surge signals that enterprises consider technical execution and regulatory validation equally critical as core functionality. Within software, integrated suites eclipse point tools because buyers demand one source of truth for data privacy audits and AI model governance. Professional services thrive on legacy-system integration and GDPR gap analysis, positioning consultancies and system integrators as gatekeepers for vendor selection.
Heightened AI Act scrutiny places a premium on solution blueprints that embed auditability by design. Vendors combine packaged software with advisory retainers, generating annuity-style revenue. The Europe marketing automation software industry will therefore see blended business models, where software margins pair with high-touch services to address dynamic rule-sets spanning GDPR, PSD2, and sector-specific mandates.
Cloud options owned 77.20% of the Europe marketing automation software market in 2025, bolstered by EU backing for sovereign and trusted cloud frameworks. Cloud deployments are expanding at 15.62% CAGR because continuous platform updates help clients absorb new data-handling obligations without capex spikes. Marketing teams benefit from elastic compute to run AI models that personalize journeys in real time. On-premise persists only where public-sector or defense clients demand strict data residency.
Regulators favor cloud's centralized control planes that support automated consent logging, breach notification, and encryption management. This regulatory alignment reduces perceived risk, spurring broader cloud migration. Partnerships, such as Oracle's tie-up with Palantir for secure EU cloud regions, illustrate how hyperscale providers localize stacks to satisfy sovereignty narratives. As uptake matures, cloud vendors will compete on value-add layers like zero-trust architectures and pre-certified AI sandboxing.
Complete Report Scope:
- By Component
- Software
- Integrated Platforms
- Stand-Alone Tools
- Lead Management
- Social Media
- Email and Analytics
- Services
- Professional Services
- Managed Services
- Software
- By Deployment Mode
- Cloud-Based
- On-Premise
- By Organisation Size
- Small and Medium Enterprises
- Large Enterprises
- By Channel / Function
- Email Marketing
- Social Media Marketing
- Campaign Management
- Mobile / SMS Marketing
- Inbound and Content Marketing
- Other Channels
- By End-user Industry
- Retail and E-commerce
- BFSI (Banking, FinServ and Insurance)
- IT and Telecom
- Manufacturing
- Healthcare and Life-Sciences
- Media and Entertainment
- Government and Public Sector
- Other End-user Industries
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Netherlands
- Nordics
- Rest of Europe
List of Companies Covered in this Report:
- Salesforce, Inc.
- Adobe Inc.(Marketo Inc.)
- HubSpot Inc.
- Oracle Corporation
- Microsoft Corporation
- SAP SE
- SAS Institute Inc.
- Act-On Software, Inc.
- Dotdigital Group PLC
- Force24 Ltd.
- ActiveCampaign LLC
- Mailchimp (Intuit Inc.)
- Sendinblue SAS (Brevo)
- GetResponse Sp. z o.o.
- Zoho Corporation
- Pipedrive OU
- SugarCRM Inc.
- Acoustic LP
- Iterable Inc.
- Klaviyo Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-Powered Personalisation Surge in DACH and Nordics E-commerce Drives the Market
- 4.2.2 EU Digital Single-Market Initiatives Boosting SME SaaS Uptake
- 4.2.3 Account-Based Marketing Adoption in B2B Tech Hubs Drives the Market
- 4.2.4 Open-Banking API Integration in European Financial Services Drives the Market
- 4.2.5 Multi-Lingual Journey Orchestration Across Fragmented Markets
- 4.3 Market Restraints
- 4.3.1 Scarcity of GDPR-Fluent Marketing-Automation Architects
- 4.3.2 High TCO for Multi-Language Personalisation Modules
- 4.3.3 Stringent EU Anti-Spam Rules Impacting Email Deliverability
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Assessment of Macro Economic Trends on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Component
- 5.1.1 Software
- 5.1.1.1 Integrated Platforms
- 5.1.1.2 Stand-Alone Tools
- 5.1.1.2.1 Lead Management
- 5.1.1.2.2 Social Media
- 5.1.1.2.3 Email and Analytics
- 5.1.2 Services
- 5.1.2.1 Professional Services
- 5.1.2.2 Managed Services
- 5.1.1 Software
- 5.2 By Deployment Mode
- 5.2.1 Cloud-Based
- 5.2.2 On-Premise
- 5.3 By Organisation Size
- 5.3.1 Small and Medium Enterprises
- 5.3.2 Large Enterprises
- 5.4 By Channel / Function
- 5.4.1 Email Marketing
- 5.4.2 Social Media Marketing
- 5.4.3 Campaign Management
- 5.4.4 Mobile / SMS Marketing
- 5.4.5 Inbound and Content Marketing
- 5.4.6 Other Channels
- 5.5 By End-user Industry
- 5.5.1 Retail and E-commerce
- 5.5.2 BFSI (Banking, FinServ and Insurance)
- 5.5.3 IT and Telecom
- 5.5.4 Manufacturing
- 5.5.5 Healthcare and Life-Sciences
- 5.5.6 Media and Entertainment
- 5.5.7 Government and Public Sector
- 5.5.8 Other End-user Industries
- 5.6 By Country
- 5.6.1 United Kingdom
- 5.6.2 Germany
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Netherlands
- 5.6.7 Nordics
- 5.6.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Salesforce, Inc.
- 6.4.2 Adobe Inc.(Marketo Inc.)
- 6.4.3 HubSpot Inc.
- 6.4.4 Oracle Corporation
- 6.4.5 Microsoft Corporation
- 6.4.6 SAP SE
- 6.4.7 SAS Institute Inc.
- 6.4.8 Act-On Software, Inc.
- 6.4.9 Dotdigital Group PLC
- 6.4.10 Force24 Ltd.
- 6.4.11 ActiveCampaign LLC
- 6.4.12 Mailchimp (Intuit Inc.)
- 6.4.13 Sendinblue SAS (Brevo)
- 6.4.14 GetResponse Sp. z o.o.
- 6.4.15 Zoho Corporation
- 6.4.16 Pipedrive OU
- 6.4.17 SugarCRM Inc.
- 6.4.18 Acoustic LP
- 6.4.19 Iterable Inc.
- 6.4.20 Klaviyo Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment