|
시장보고서
상품코드
2121504
자동차용 반도체 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Semiconductor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
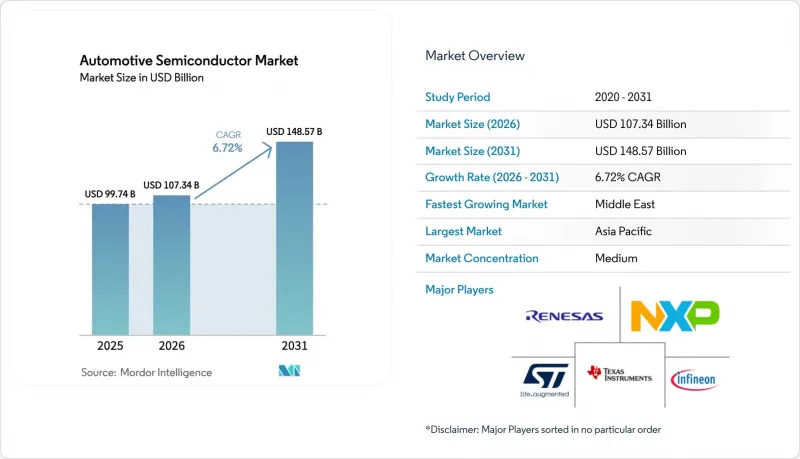
자동차용 반도체 시장 규모는 2025년 997억 4,000만 달러, 2026년 1,073억 4,000만 달러에서 2031년까지 1,485억 7,000만 달러로 확대될 것으로 예측되며, 2026년부터 2031년까지 기간의 CAGR은 6.72%가 될 전망입니다.
본 보고서는 디바이스 유형(디스크리트 반도체, 옵토일렉트로닉스 등), 차량 구동 방식(내연기관, 하이브리드 등), 용도(파워트레인 및 전동화, ADAS 및 자율주행 등), 비즈니스 모델(IDM, 팹리스, 파운드리), 지역(아메리카 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 자동차용 반도체 시장의 동향 및 인사이트
신흥국에서의 자동차 생산 대수 증가
2025년, 인도의 경차 생산 대수는 전년 대비 9% 증가한 580만 대에 달했으며, 동남아시아의 조립 대수는 320만 대를 넘어섰습니다. 이에 따라 현재는 안정성 제어 기능이나 기본적인 커넥티비티 기능이 기본 사양으로 탑재된 엔트리 모델용 반도체 수요가 증가하고 있습니다. 인도의 ‘생산 연계형 인센티브(PLI)’ 제도에 따른 새로운 조립 및 시험 능력 확장으로 인해 공급의 현지화가 진행되며 수입 비용이 절감되고 있습니다. 이러한 움직임은 멕시코와 걸프 국가들의 인센티브를 배경으로 한 투자에도 반영되고 있습니다. 이러한 움직임으로 인해 공급망이 단축되고, 설계 인력이 지역에 정착하며, 인증까지 걸리는 기간이 단축됩니다. 신흥 시장의 구매자들이 과거에는 프리미엄 부문에만 국한되었던 안전 기능을 요구함에 따라, 차량 1대당 반도체 탑재량은 지속적으로 증가하고 있습니다. 그 결과, 자동차용 반도체 시장은 전 세계 자동차 생산 대수의 성장률을 훨씬 상회하는 지속적인 구조적 확장을 이루고 있습니다.
첨단 안전·편의 시스템에 대한 수요 증가
유럽연합(EU)의 ‘일반 안전 규정’에서는 2024년 7월 이후 모든 신차 형식 인증에 대해 지능형 속도 지원, 첨단 긴급 제동, 운전자 모니터링을 의무화하여, 주류 모델에 레이더와 카메라 탑재를 사실상 표준화했습니다. 미국의 사고 감소 데이터는 이러한 비즈니스 사례를 뒷받침하고 있으며, 보험사는 자동 긴급 제동 장치가 탑재된 차량의 보험료를 인하할 수 있게 되어, 결과적으로 소비자의 도입을 촉진하고 있습니다. 중국의 신차 평가 프로그램(C-NCAP)은 2025년에 5성급 기준을 상향 조정하여, 국내 브랜드에 최대 100미터 앞까지 보행자를 감지할 수 있는 고해상도 센서 탑재를 권장하고 있습니다. 이러한 규제는 비용에 민감한 지역으로도 확대되고 있어, 소형차조차도 반도체의 평균 부품 원가(BOM)를 상승시키고 있습니다. 기능 안전 분야에서 확실한 실적을 보유한 Tier 1 공급업체는 ISO 26262 요건이 검증된 플랫폼에 유리하게 작용하기 때문에 유리한 입장에 있습니다.
첨단 기능을 탑재한 차량의 높은 비용
주류 차량에 레벨 2 운전 지원 기능을 장착하면, 미국에서는 평균 판매 가격이 4만 8,000달러를 초과하여 해당 부문의 표준 가격보다 22% 높아집니다. 이러한 기능 패키지에 포함된 반도체의 비용은 종종 1,000달러를 초과하며, 자동차 제조사는 연구개발비 및 검증 비용을 회수하기 위해 가격을 대폭 인상하고 있습니다. 가격 탄력성이 높은 신흥 시장에서는 그 영향이 가장 두드러지게 나타나고 있으며, 보급은 상위 등급으로 한정되고 있습니다. 또한, 규제 당국이 보행자 안전을 위해 ‘페일 오퍼레이셔널(고장 시에도 작동하는)’ 설계를 의무화하고 있어, 중복된 센서 구성이 비용을 더욱 상승시키고 있습니다. 공급업체들은 LiDAR에 대한 의존도를 낮추는 저비용 센서 융합 방안을 모색하고 있지만, 기능 안전상의 제약으로 인해 여전히 급격한 비용 절감이 어려워지고 있습니다.
부문 분석
자동차용 반도체 시장에서 집적회로의 시장 규모는 2025년에 정점을 찍었으며, 존형 및 집중형 아키텍처를 지원하는 마이크로컨트롤러, SoC, 메모리 덕분에 매출의 43.32%를 차지했습니다. 연산 밀도 향상, 임베디드 하드웨어 보안 및 무선 업데이트(OTA) 지원 덕분에 이러한 디바이스는 필수 불가결한 요소가 되었습니다. 시장 참여 기업들에 따르면, 최신 SoC는 이기종 CPU 클러스터, 그래픽 엔진, 신경망 프로세서를 통합하여 단일 패키지로 콕핏, 연결성, 저속 자율주행 워크로드를 처리할 수 있게 되었습니다. 지도 데이터와 신경망 가중치의 확대에 따라 임베디드 메모리에 대한 수요는 계속해서 급증하고 있습니다.
센서 및 마이크로 전자 기계 시스템(MEMS)은 디바이스 카테고리 중 가장 빠른 연평균 성장률(CAGR)인 17.61%를 기록할 것으로 예상됩니다. 레이더, 라이더, 카메라, 초음파, 관성 센서는 현재 법적으로 의무화된 안전 기능을 위해 360도 인식을 실현하기 위해 중복 어레이로 출하되고 있습니다. 텍사스 인스트루먼트의 코너 레이더용 칩은 RF 프론트엔드와 신호 처리를 하나의 다이에 통합하여 이러한 통합 추세를 상징하고 있습니다. 한편, 와이드밴드 갭(WBG) 전력 디스크리트 부품은 멀티칩 모듈로 전환되고 있으며, 디스크리트 부품의 성장세는 다소 둔화되고 있지만 평균 판매 가격은 상승하고 있습니다. 향후 전개에서는 센싱, 처리, 액추에이터를 통합 플랫폼에 융합할 수 있는 공급업체가 유리한 입지를 차지하게 되어, 자동차용 반도체 시장의 규모의 경제가 더욱 강화될 것입니다.
배터리식 전기자동차는 여전히 1대당 반도체 탑재액이 가장 높으며, 2025년 반도체 매출의 54.19%를 차지할 전망입니다. 마일드 하이브리드의 48V 시스템에서는 컨버터와 컨트롤러가 추가되기 때문에 완전 전동화에 이르기 전이라도 칩 탑재량은 증가하는 추세에 있습니다. 대조적으로, 내연기관 차량과 연계된 자동차용 반도체 시장의 규모는 기존 플랫폼에서도 전자화가 진행되고 있는 영향으로 연평균 성장률(CAGR) 17.49%로 확대될 것으로 예측됩니다. BEV(배터리식 전기자동차) 1대당 파워 일렉트로닉스만으로도 600-800달러의 가치를 지니며, 이는 내연기관 차량을 훨씬 상회합니다.
하이브리드 구성은 과도기적인 해결책을 제공하며, 듀얼 전원 관리 아키텍처가 필요하기 때문에 차량당 반도체 가치는 약 700달러로 상승합니다. 연료전지차는 여전히 틈새 시장이지만, 전용 고전압 컨버터가 필요하며, 수소 인프라가 성숙해지면 향후 성장이 기대됩니다. BYD와 스텔란티스 등의 자동차 제조업체들은 실리콘 카바이드 모듈에 크게 의존하는 표준화된 400볼트 및 800볼트 플랫폼을 발표하고 있어, 구동 방식의 선택과 반도체 부품 원가 간의 연관성이 더욱 강해지고 있습니다. 이 데이터는 단기적으로는 내연기관이 생산 대수를 주도하는 상황이 지속될 것으로 예상되지만, 가치의 성장은 전동화된 구동 시스템에 좌우된다는 점을 뒷받침하고 있습니다.
지역별 분석
아시아태평양은 중국의 전기자동차 판매량 900만 대와 신에너지차에 대한 25%의 국내 부품 사용률 의무화를 견인력으로 삼아 2025년 매출의 45.87%를 차지했습니다. 파운드리 및 조립 공장과 인접해 있어 비용 최적화를 목표로 한 설계 주기가 단축되고 맞춤형 디바이스의 신속한 인증이 가능해짐에 따라, 이 지역의 반도체 로드맵에 대한 영향력이 강화되고 있습니다. 한국의 주요 메모리 기업들은 2027년까지 300mm 웨이퍼 생산량의 15%를 자동차 업계 고객에 할당하겠다고 약속했으며, 이로 인해 공급망의 집적이 더욱 심화되고 있습니다.
북미와 유럽을 합치면 매출의 약 35%를 차지합니다. 적극적인 안전성 및 탈탄소화 목표가 계속해서 높은 반도체 수요를 견인하고 있는 한편, 미국의 ‘CHIPS and Science Act’와 유럽연합(EU)의 ‘Chips Act’에 따른 공공 인센티브로 인해 수십억 달러가 국내 팹에 투입되고 있습니다. 이러한 공장들은 2027년부터 2028년까지 본격 가동에 이르지 못하기 때문에 당분간 이 지역은 아시아에서의 수입에 의존하게 될 것입니다.
중동은 현재 규모는 작지만, 2031년까지 연평균 성장률(CAGR) 18.12%를 기록할 것으로 예상됩니다. 아랍에미리트(UAE)와 사우디아라비아의 국부펀드는 첨단 운전자 보조 시스템(ADAS) 및 배터리 관리 기능을 필수로 하는 전기자동차(EV) 도입 의무화와 현지 조립을 뒷받침하고 있으며, 이를 통해 전 세계 1차 공급업체들을 그린필드 사업 제휴로 끌어들이고 있습니다. 아프리카와 남미는 여전히 보급형 차량의 대량 판매 시장이지만, 전자식 안정성 제어(ESC) 및 타이어 공기압 모니터링 시스템에 대한 규제 도입으로 인해 칩 수요가 서서히 증가하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the automotive semiconductor market size is projected to expand from USD 99.74 billion in 2025 and USD 107.34 billion in 2026 to USD 148.57 billion by 2031, registering a CAGR of 6.72% between 2026 to 2031.
This report is Segmented by Device Type (Discrete Semiconductors, Optoelectronics, and More), Vehicle Propulsion (Internal Combustion Engine, Hybrid, and More), Application (Powertrain and Electrification, ADAS and Autonomous Driving, and More), Business Model (IDM, Fabless, and Foundry), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Semiconductor Market Trends and Insights
Increasing Vehicle Production in Emerging Economies
Light-vehicle output in India reached 5.8 million units in 2025, a 9% annual rise, while Southeast Asian assembly topped 3.2 million units, pushing semiconductor demand for entry-level models that now ship with stability control and basic connectivity as standard. New assembly and test capacity under India's Production-Linked Incentive scheme is localizing supply and trimming import costs, a shift mirrored by incentive-backed investments in Mexico and the Gulf states. These moves shorten supply chains, anchor design talent regionally, and accelerate time to qualification. As emerging-market buyers demand safety features once reserved for premium segments, chip volumes per vehicle continue to climb. The result is sustained structural expansion for the automotive semiconductor market well beyond global vehicle growth rates.
Rising Demand for Advanced Safety and Comfort Systems
The European Union's General Safety Regulation mandated intelligent speed assistance, advanced emergency braking, and driver monitoring for all new type approvals after July 2024, effectively standardizing radar and camera content across mainstream models. U.S. crash-reduction data have reinforced the business case, enabling insurers to lower premiums for vehicles fitted with automated emergency braking, which, in turn, spurs consumer uptake. China's New Car Assessment Program raised its five-star standard in 2025, prompting domestic brands to incorporate higher-resolution sensors capable of detecting pedestrians up to 100 meters away. These mandates are spreading to cost-sensitive regions, lifting average semiconductor bill-of-materials values for even compact cars. Tier-one suppliers with deep functional-safety pedigrees are well positioned, as ISO 26262 barriers favor proven platforms.
High Cost of Advanced-Feature Vehicles
Equipping a mainstream vehicle with Level 2 driver assistance pushes average transaction prices above USD 48,000 in the United States, making such cars 22% costlier than segment norms. Semiconductor content for these feature packs often exceeds USD 1,000, and automakers apply significant mark-ups to recover R&D and validation costs. Emerging markets with high price elasticity feel the effect most acutely, limiting penetration to upper trims. Redundant sensor architectures raise costs further because regulators insist on fail-operational designs for pedestrian safety. Although suppliers are exploring lower-cost sensor fusion that reduces lidar reliance, functional-safety ceilings still restrain rapid cost downs.
Other drivers and restraints analyzed in the detailed report include:
- Electrification Boosting Semiconductor Content per Vehicle
- Zonal E/E Architectures and Software-Defined Vehicles Spur High-End Processors
- Persistent Supply-Chain Constraints and Chip Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The automotive semiconductor market size for integrated circuits stood highest in 2025, capturing 43.32% revenue thanks to microcontrollers, SoCs, and memory that underpin zonal and centralized architectures. Growing compute density, embedded hardware security, and over-the-air update readiness make these devices indispensable. Market participants note that the latest SoCs combine heterogeneous CPU clusters, graphics engines, and neural processors, allowing a single package to handle cockpit, connectivity, and low-speed autonomy workloads. Demand for embedded memory continues to surge as map data and neural network weights expand.
Sensors and microelectromechanical systems are forecast to post a 17.61% CAGR, the fastest pace among device categories. Radar, lidar, camera, ultrasonic, and inertial units now ship in redundant arrays to deliver 360-degree perception for mandated safety functions. Texas Instruments' corner-radar chip, which integrates an RF front-end and signal processing on one die, typifies this consolidation trend. Meanwhile, wide-bandgap power discretes are migrating into multichip modules, slightly tempering discrete unit growth but lifting average selling prices. The pathway ahead favors suppliers that can blend sensing, processing, and actuation into integrated platforms, reinforcing scale advantages in the automotive semiconductor market.
Battery electric vehicles still deliver the highest semiconductor value per vehicle, giving them 54.19% of 2025 semiconductor revenue. Mild-hybrid 48-volt systems add converters and controllers, nudging chip content upward even before full electrification. In contrast, the automotive semiconductor market size tied to internal-combustion vehicles will expand at a projected 17.49% CAGR, influenced by increasing electronic content even in conventional platforms. Each battery electric car carries USD 600-USD 800 of power electronics alone, dwarfing combustion counterparts.
Hybrid configurations offer a bridge solution, demanding dual power-management architectures that lift per-vehicle chip value to roughly USD 700. Fuel-cell variants remain niche but command specialized high-voltage converters, hinting at future upside should hydrogen infrastructure mature. Automakers such as BYD and Stellantis have announced standardized 400-volt and 800-volt platforms that rely heavily on silicon-carbide modules, tightening the link between propulsion choice and semiconductor bill of materials. The data confirm that value growth will hinge on electrified drivetrains, even as combustion engines dominate production counts through the near term.
Complete Report Scope:
- By Device Type
- Discrete Semiconductors
- Diodes
- Transistors
- Power Transistors
- Rectifiers and Thyristors
- Other Discrete Devices
- Optoelectronics
- Light-Emitting Diodes (LEDs)
- Laser Diodes
- Image Sensors
- Optocouplers
- Other Optoelectronic Devices
- Sensors and MEMS
- Pressure Sensors
- Magnetic Field Sensors
- Actuators
- Acceleration and Yaw-Rate Sensors
- Temperature and Other Sensors
- Integrated Circuits
- By Integrated Circuit Type
- Analog
- Micro
- Microprocessors (MPU)
- Microcontrollers (MCU)
- Digital Signal Processors
- Logic
- Memory
- By Technology Node (Shipment Volume Not Applicable)
- < 3 nm
- 3 nm
- 5 nm
- 7 nm
- 16 nm
- 28 nm
- > 28 nm
- By Integrated Circuit Type
- Discrete Semiconductors
- By Vehicle Propulsion
- Internal Combustion Engine Vehicles
- Hybrid Vehicles
- Battery Electric Vehicles
- Fuel-Cell Electric Vehicles
- By Application
- Powertrain and Electrification
- Advanced Driver-Assistance Systems (ADAS) and Autonomous Driving
- Body Electronics and Comfort
- Infotainment and Connectivity
- Safety Systems
- By Business Model
- Integrated Device Manufacturer (IDM)
- Design / Fabless Vendor
- Foundry Service Provider
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- North America
Geography Analysis
Asia Pacific generated 45.87% of 2025 revenue, anchored by China's 9 million electric-vehicle sales and its 25% domestic-content mandate for new-energy vehicles. Proximity to foundries and assembly houses enables faster design-for-cost loops and the prompt qualification of custom devices, thereby strengthening the region's influence on semiconductor roadmaps. South Korea's memory giants have pledged to dedicate 15% of their 300-millimeter wafer output to automotive customers by 2027, thereby deepening the supply-chain cluster.
North America and Europe combined for roughly 35% of revenue. Aggressive safety and decarbonization targets continue to drive high semiconductor intensity, while public incentives under the United States CHIPS and Science Act and the European Union Chips Act channel billions of dollars into domestic fabs. Those plants will not fully ramp up until 2027-2028, leaving the regions reliant on Asian imports in the interim.
The Middle East, although a small base today, is expected to log an 18.12% CAGR through 2031. Sovereign funds in the United Arab Emirates and Saudi Arabia are backing electric fleet mandates and local assembly that specify advanced driver-assistance and battery-management features, pulling global tier-one suppliers into greenfield partnerships. Africa and South America remain volume markets for entry-level vehicles, yet regulatory adoption of electronic stability control and tire-pressure monitoring is gradually lifting chip demand.
- NXP Semiconductors N.V.
- Infineon Technologies AG
- Renesas Electronics Corporation
- STMicroelectronics N.V.
- Texas Instruments Inc.
- Toshiba Electronic Devices and Storage Corporation
- Micron Technology Inc.
- onsemi
- Analog Devices Inc.
- Robert Bosch GmbH, Semiconductor Division
- ROHM Co., Ltd.
- NVIDIA Corporation
- Qualcomm Technologies Inc.
- Intel Corporation (Mobileye)
- Samsung Electronics Co., Ltd., System LSI
- MediaTek Inc.
- BYD Semiconductor Co. Ltd.
- Semtech Corporation
- Diodes Incorporated
- Microchip Technology Inc.
- Melexis NV
- Elmos Semiconductor SE
- Allegro Microsystems, Inc.
- Skyworks Solutions, Inc.
- Ambarella Inc.
- Wolfspeed Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Vehicle Production in Emerging Economies
- 4.2.2 Rising Demand for Advanced Safety and Comfort Systems
- 4.2.3 Electrification Boosting Semiconductor Content per Vehicle
- 4.2.4 Zonal E/E Architectures and Software-Defined Vehicles Spur High-End Processors
- 4.2.5 Government Incentives for Auto-Grade Foundry Capacity Expansion
- 4.2.6 Adoption of SiC and GaN Power Devices in Electric Powertrains
- 4.3 Market Restraints
- 4.3.1 High Cost of Advanced-Feature Vehicles
- 4.3.2 Persistent Supply-Chain Constraints and Chip Shortages
- 4.3.3 Scarcity and Cost of Wide-Bandgap Substrates
- 4.3.4 Lengthy Automotive Qualification Cycles Slow Time-to-Market
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 RF Device Demand in Autonomous Vehicles
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment Analysis
- 4.10 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Device Type
- 5.1.1 Discrete Semiconductors
- 5.1.1.1 Diodes
- 5.1.1.2 Transistors
- 5.1.1.3 Power Transistors
- 5.1.1.4 Rectifiers and Thyristors
- 5.1.1.5 Other Discrete Devices
- 5.1.2 Optoelectronics
- 5.1.2.1 Light-Emitting Diodes (LEDs)
- 5.1.2.2 Laser Diodes
- 5.1.2.3 Image Sensors
- 5.1.2.4 Optocouplers
- 5.1.2.5 Other Optoelectronic Devices
- 5.1.3 Sensors and MEMS
- 5.1.3.1 Pressure Sensors
- 5.1.3.2 Magnetic Field Sensors
- 5.1.3.3 Actuators
- 5.1.3.4 Acceleration and Yaw-Rate Sensors
- 5.1.3.5 Temperature and Other Sensors
- 5.1.4 Integrated Circuits
- 5.1.4.1 By Integrated Circuit Type
- 5.1.4.1.1 Analog
- 5.1.4.1.2 Micro
- 5.1.4.1.2.1 Microprocessors (MPU)
- 5.1.4.1.2.2 Microcontrollers (MCU)
- 5.1.4.1.2.3 Digital Signal Processors
- 5.1.4.1.3 Logic
- 5.1.4.1.4 Memory
- 5.1.4.2 By Technology Node (Shipment Volume Not Applicable)
- 5.1.4.2.1 < 3 nm
- 5.1.4.2.2 3 nm
- 5.1.4.2.3 5 nm
- 5.1.4.2.4 7 nm
- 5.1.4.2.5 16 nm
- 5.1.4.2.6 28 nm
- 5.1.4.2.7 > 28 nm
- 5.1.4.1 By Integrated Circuit Type
- 5.1.1 Discrete Semiconductors
- 5.2 By Vehicle Propulsion
- 5.2.1 Internal Combustion Engine Vehicles
- 5.2.2 Hybrid Vehicles
- 5.2.3 Battery Electric Vehicles
- 5.2.4 Fuel-Cell Electric Vehicles
- 5.3 By Application
- 5.3.1 Powertrain and Electrification
- 5.3.2 Advanced Driver-Assistance Systems (ADAS) and Autonomous Driving
- 5.3.3 Body Electronics and Comfort
- 5.3.4 Infotainment and Connectivity
- 5.3.5 Safety Systems
- 5.4 By Business Model
- 5.4.1 Integrated Device Manufacturer (IDM)
- 5.4.2 Design / Fabless Vendor
- 5.4.3 Foundry Service Provider
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Australia
- 5.5.4.6 New Zealand
- 5.5.4.7 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Kenya
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 NXP Semiconductors N.V.
- 6.4.2 Infineon Technologies AG
- 6.4.3 Renesas Electronics Corporation
- 6.4.4 STMicroelectronics N.V.
- 6.4.5 Texas Instruments Inc.
- 6.4.6 Toshiba Electronic Devices and Storage Corporation
- 6.4.7 Micron Technology Inc.
- 6.4.8 onsemi
- 6.4.9 Analog Devices Inc.
- 6.4.10 Robert Bosch GmbH, Semiconductor Division
- 6.4.11 ROHM Co., Ltd.
- 6.4.12 NVIDIA Corporation
- 6.4.13 Qualcomm Technologies Inc.
- 6.4.14 Intel Corporation (Mobileye)
- 6.4.15 Samsung Electronics Co., Ltd., System LSI
- 6.4.16 MediaTek Inc.
- 6.4.17 BYD Semiconductor Co. Ltd.
- 6.4.18 Semtech Corporation
- 6.4.19 Diodes Incorporated
- 6.4.20 Microchip Technology Inc.
- 6.4.21 Melexis NV
- 6.4.22 Elmos Semiconductor SE
- 6.4.23 Allegro Microsystems, Inc.
- 6.4.24 Skyworks Solutions, Inc.
- 6.4.25 Ambarella Inc.
- 6.4.26 Wolfspeed Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment