

|
시장보고서
상품코드
2121641
폴리올레핀(PO) : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Polyolefin (PO) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 폴리올레핀 시장 규모는 2025년 2,404억 9,000만 달러에서 2026년에는 2,576억 1,000만 달러에 이르고, 2026-2031년 CAGR 7.12%로 성장을 지속하여 2031년에는 3,633억 9,000만 달러에 달할 것으로 예측됩니다.
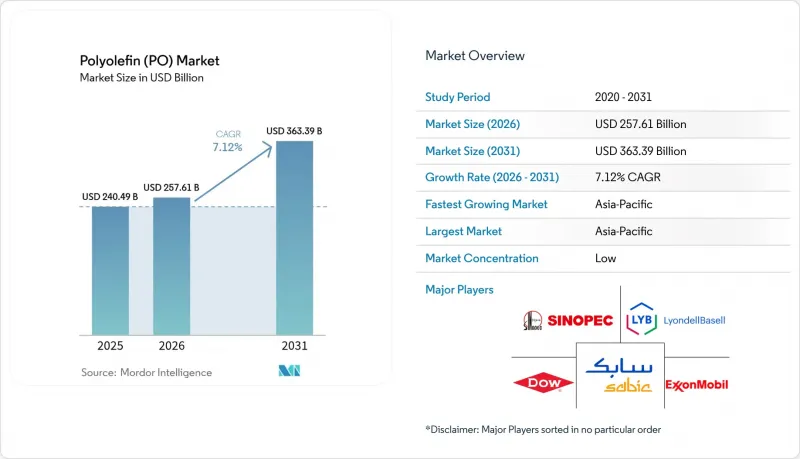
본 보고서는 소재 유형(폴리에틸렌(PE) 및 폴리프로필렌(PP)), 용도(필름 및 시트, 사출 성형, 블로우 성형, 압출 코팅, 섬유·라피아), 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 규모 및 전망은 상기 모든 부문에 대해 금액(달러) 기준으로 제시되어 있습니다.
세계 폴리올레핀(PO) 시장 동향 및 인사이트
경질 포장에서 연질 포장으로의 전환
브랜드 소유주들은 차단 성능 목표를 달성하면서 물류 비용을 절감할 수 있는 더 가볍고 유연한 솔루션으로 전환하고 있으며, 이러한 변화는 폴리올레핀 시장 전체에서 필름용 수지 수요의 확대로 이어지고 있습니다. 연포장재는 기존의 경질 용기에 비해 최대 70% 적은 재료로 제작될 수 있어, 운송 시 배출 가스와 창고 공간을 줄일 수 있습니다. 2024년공급망 혼란을 통해, 단층 폴리에틸렌 파우치는 유리나 금속 용기보다 효율적으로 운송될 수 있으며, 항만이 혼잡할 때에도 매장 내 상품 구색을 확보할 수 있음이 밝혀졌습니다. 현재 필름 가공업체들은 선형 저밀도 폴리에틸렌(LLDPE) 등급에 나노 배리어 코팅을 적용하여, 과거에는 다층 라미네이트로만 실현할 수 있었던 유통 기한을 달성하고 있습니다. 2028년까지 도입될 예정인 EU 차원의 ‘재활용을 고려한 설계(Design for Recycling)’ 기준은 이러한 단일 소재 구조를 권장하고 있으며, 제품의 교체 주기를 가속화할 것입니다.
비용 효율이 뛰어난 인테리어 제품 및 소비재에 대한 수요
인도, 인도네시아, 베트남의 중산층 가구에서는 엔지니어링 플라스틱 비용의 3분의 1에 불과한 가격으로 충분한 내구성을 제공하는 폴리프로필렌 소재의 가구 및 가전제품 외장을 점점 더 많이 선택하고 있습니다. OEM 업체들은 이 폴리머의 폭넓은 가공 범위 덕분에 성형 사이클 시간을 단축하고, 높은 전기 요금으로 어려움을 겪고 있는 공장의 전력 소비를 줄이고 있습니다. 자동차 부품 공급업체들도 도어 패널용 유리섬유 강화 ABS 부품을 내충격성이 향상된 폴리올레핀 블렌드로 대체하여, 고가의 탄소 복합재를 사용하지 않고도 차량의 경량화를 실현하고 있습니다. 또한, 개발 파이프라인에는 자외선에 견디는 탈크 충전 랜덤 코폴리머 등급도 포함되어 있어, 실외용 소비재에 적합합니다.
일회용 플라스틱 및 탄소세에 관한 규제 강화
EU는 2030년부터 1.5kg 미만의 경량 농산물용 봉투를 금지하여, 폴리에틸렌 필름 수요원인 80만 톤을 감축하게 될 것입니다. 동시에, 탄소세 도입으로 인해 유럽 크래커의 현금 비용이 에틸렌 환산 기준 톤당 75달러 상승하여, 세금 부담이 적은 지역의 수출업체에 비해 순수익이 압박받고 있습니다. 각 생산사는 소매점 진열을 유지하기 위해 재활용률 35%의 폐쇄형 포장(클로즈드 루프)으로 전환을 추진하고 있지만, 금지 대상이 된 품목으로 인한 판매량 감소를 만회하기까지는 시간이 걸릴 것입니다. 일부 필름 가공업체들은 과세를 피하기 위해 슬릿 롤 가공을 튀르키예나 이집트로 이전하고 있어, 폴리올레핀 시장 내 무역 흐름에 변화가 생기고 있습니다.
부문 분석
폴리에틸렌은 포장, 건설, 농업 분야에서 확고한 입지를 바탕으로 2025년 폴리올레핀 시장 점유율의 55.02%를 차지했습니다. 그러나 폴리프로필렌은 연평균 성장률(CAGR) 8.02%를 나타낼 것으로 예측되어, 2031년까지 폴리올레핀 시장 내 점유율이 크게 확대될 것입니다. 선형 저밀도 폴리에틸렌의 각 등급은 박막 필름 가공 업체에서 수요가 증가하고 있는 반면, 고밀도 등급은 세제 병이나 인도 전역에서 진행 중인 상수도 인프라 정비 붐으로 인해 수요가 증가하고 있는 내식성 파이프에 사용되고 있습니다. 저밀도 폴리에틸렌은 재활용 설계에 대한 압박에 직면하고 있지만, 액체용 카톤의 압출 코팅 분야에서는 여전히 확고한 입지를 유지하고 있습니다.
메탈로센 기술의 혁신으로 초박형 캐스트 필름과 폴리카보네이트 수준의 투명도에 근접한 고강성 폴리프로필렌 랜덤 코폴리머가 가능해졌습니다. 이러한 등급은 인발 및 열성형의 자유도를 넓혀 브랜드 소유자가 폴리스티렌이나 PVC에서 전환하는 것을 촉진하고 있습니다. 자동차 제조업체들은 프론트엔드 캐리어에 장섬유 강화 폴리프로필렌을 지정하고 있으며, 화학적 재활용 원료공급이 확대됨에 따라 컴파운더의 수익원은 기존의 범퍼 페시아를 넘어 확장되고 있습니다. 또한, 폴리에틸렌 및 폴리프로필렌 생산업체들은 재활용 원료를 50% 함유한 등급의 인증 획득을 목표로 하고 있으며, 이를 통해 고객 충성도를 강화하고 폴리올레핀 시장에서의 점유율을 지키려 하고 있습니다.
지역별 분석
아시아태평양은 2025년에 폴리올레핀 시장 점유율의 51.22%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 8.21%를 기록할 전망입니다. 중국의 물류 포장 현대화, 인도의 인프라 정비 추진, 그리고 아세안(ASEAN) 국가들의 소비 붐이 모두 수요 증가를 견인하고 있습니다. 정유시설와 화학 공장이 일체화된 복합 시설은 전환 비용을 낮게 억제할 수 있지만, 중국의 2026년 버진 플라스틱 소비량 상한선 설정 등 지속가능성 대책이 향후 생산 능력 선택에 영향을 미칠 것으로 전망됩니다.
북미는 비용 경쟁력이 있는 폴리에틸렌의 원료인 셰일 유래 에탄이 풍부하여 시장 점유율 2위를 차지하고 있습니다. 2024년에는 전자상거래 주문 처리 및 내구재 수주 회복에 힘입어 해당 지역의 폴리에틸렌 수요는 7%, 폴리프로필렌 수요는 4% 증가했습니다. 걸프 연안에서의 수지 수출은 국내 시장이 둔화될 때 생산자를 뒷받침하는 역할을 하고 있지만, 파나마 운하의 혼잡으로 인해 화물이 미국 동부 해안 항구를 경유하는 우회 경로를 택하게 되어 운송 시간이 길어지고 있습니다.
유럽에서는 가스 시장의 혼란으로 인해 에너지 비용이 미국의 3배에 달하는 문제에 직면해 있습니다. 그럼에도 불구하고, 화학 재활용 기술의 조기 도입으로 인해 이 지역은 순서큘러 폴리머 거래의 최전선에 서 있습니다. 생산자들은 수익성이 높은 특수 등급으로의 전환과, 추적 가능성이 있는 재활용 소재를 요구하는 브랜드 소유주와의 서비스 계약에 주력하고 있습니다. 중동에서는 2020년 이후 15% 증가한 가스 생산량을 활용하여 아시아와 아프리카에 경쟁력 있는 가격의 수지를 공급하고 있습니다. 반면, 남미는 수입 의존도가 높아 현지 가격이 높은 수준을 유지하고 있으며, 이는 브라질 내 신규 스팀 크래커 투자를 촉진하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the polyolefin market size is expected to grow from USD 240.49 billion in 2025 to USD 257.61 billion in 2026 and is forecast to reach USD 363.39 billion by 2031 at 7.12% CAGR over 2026-2031.
This report is Segmented by Material Type (Polyethylene (PE) and Polypropylene (PP)), Application (Films and Sheets, Injection Molding, Blow Molding, Extrusion Coating, and Fibers and Raffia), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Size and Forecasts are Provided in Terms of Value (USD) for all the Above Segments.
Global Polyolefin (PO) Market Trends and Insights
Shift from Rigid to Flexible Packaging
Brand owners migrate to lighter, flexible solutions that meet barrier targets while cutting logistics costs, a shift translating into larger film resin requirements across the polyolefin market. Flexible formats use up to 70% less material than legacy rigid containers, trimming freight emissions and warehouse space. Supply-chain disruptions in 2024 showed that mono-polyethylene pouches travel more efficiently than glass or metal options, ensuring on-shelf availability even during port congestion. Film converters now layer nano-barrier coatings on linear-low-density grades, matching shelf life once available only from multilayer laminates. EU-level design-for-recycling criteria due by 2028 favor these mono-material structures and will accelerate the replacement cycle.
Demand for Cost-efficient Interior and Consumer Goods
Middle-income households in India, Indonesia, and Vietnam increasingly opt for polypropylene furniture and appliance casings that deliver acceptable durability at one-third the cost of engineering plastics. OEMs reduce molding cycle time thanks to the polymer's broad processing window, cutting electricity consumption in factories strained by high power tariffs. Automotive suppliers are also swapping glass-fiber reinforced ABS parts with impact-modified polyolefin blends for door panels, shaving vehicle mass without expensive carbon composites. The development pipeline further includes talc-filled random-copolymer grades that withstand UV exposure, making them suitable for outdoor consumer goods.
Stricter Single-use-plastic and Carbon-tax Regulations
The EU bans lightweight produce bags under 1.5 kg beginning in 2030, eliminating a 0.8 million-tonne demand stream for polyethylene film. Simultaneously, carbon levies lift cash costs at European crackers by USD 75 per tonne ethylene equivalent, compressing netbacks relative to exporters from tax-lighter regions. Producers pivot to closed-loop packaging with 35% recycled content to retain retail shelves, yet volumes lost in banned skews take time to replace. Some film converters relocate slit-roll finishing to Turkey and Egypt to avoid levy exposure, altering trade flows within the Polyolefin market.
Other drivers and restraints analyzed in the detailed report include:
- Circular-economy Mandates Driving Chemical-recycling Grades
- Surging EV Lightweighting Needs for PP/POE Compounds
- Global Oversupply and Margin Pressure from Mega-crackers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene accounted for 55.02 of % Polyolefin market share in 2025, thanks to its entrenched role in packaging, construction, and agriculture. Yet polypropylene is forecast to post an 8.02% CAGR, meaning its slice of the polyolefin market size will expand meaningfully by 2031. Linear-low-density variants prosper as converters of down-gauge film, while high-density grades serve detergent bottles and corrosion-resistant pipes demanded by the water infrastructure boom across India. Low-density polyethylene faces design-for-recycling pressure, but maintains a foothold in extrusion-coating for liquid cartons.
Metallocene innovations enable ultra-thin cast films and high-stiffness polypropylene random copolymers that approach polycarbonate clarity. These grades unlock stretching and thermoforming latitude, helping brand owners migrate from polystyrene and PVC. Automakers specify long-glass polypropylene for front-end carriers, broadening revenue for compounders beyond traditional bumper fascia as chemical-recycling feedstock supply scales, polyethylene and polypropylene producers aim to certify grades with 50% circular content, reinforcing customer loyalty and protecting share in the polyolefin market.
Complete Report Scope:
- By Material Type
- Polyethylene (PE)
- High-Density PE (HDPE)
- Low-Density PE (LDPE)
- Linear Low-Density PE (LLDPE)
- Polypropylene (PP)
- Polyethylene (PE)
- By Application
- Films and Sheets
- Injection Molding
- Blow Molding
- Extrusion Coating
- Fibers and Raffia
- End-user Industry
- Packaging
- Automotive and Transportation
- Electrical and Electronics
- Building and Construction
- Other End-user Industries
- Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 51.22% polyolefin market share in 2025 and is tracking an 8.21% CAGR through 2031. China's modernization of logistics packaging, India's infrastructure push, and ASEAN's consumer boom all funnel incremental demand. Integrated refining-to-chemicals sites grant low conversion cost, but sustainability measures-such as China's 2026 cap on virgin-plastic consumption-will influence future capacity choices.
North America is the second-largest slice because of abundant shale-based ethane that yields cost-advantaged polyethylene. Regional demand rose 7% for polyethylene and 4% for polypropylene in 2024 due to e-commerce fulfillment and recovering durable goods orders. Resin exports from the Gulf Coast cushion producers during domestic slowdowns, though Panama Canal congestion reroutes cargo via U.S. East Coast ports, stretching transit times.
Europe wrestles with energy costs triple those in the U.S. following gas market upheaval. Nonetheless, early adoption of chemical-recycling technology positions the bloc at the forefront of circular polymer commerce. Producers pivot toward higher-margin specialty grades and service contracts with brand owners seeking traceable recycled content. The Middle East leverages a 15% rise in gas output since 2020 to supply competitively priced resin into Asia and Africa, while South America's import reliance keeps local prices high, incentivizing Brazilian investments in new steam crackers.
- Arkema
- BASF
- Borealis GmbH
- Braskem
- Chevron Phillips Chemical Company LLC
- PetroChina Company Limited
- China Petrochemical Corporation
- Daelim Co., Ltd.
- Dow
- Exxon Mobil Corporation
- Formosa Plastics Corporation
- INEOS
- Japan Polypropylene Corporation
- LG Chem
- LyondellBasell Industries Holdings B.V.
- Mitsubishi Chemical Group Corporation
- Mitsui Chemicals India Pvt. Ltd.
- NOVA Chemicals
- PetroChina Co. Ltd.
- Reliance Industries Limited
- SABIC
- Sasol Ltd.
- Tosoh Corporation
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift from Rigid to Flexible Packaging
- 4.2.2 Demand for Cost-efficient Interior and Consumer Goods
- 4.2.3 Circular-economy Mandates Driving Chemical-recycling Grades
- 4.2.4 Surging EV Lightweighting Needs for PP/POE Compounds
- 4.2.5 Metallocene-catalyst Boom Enabling Specialty PE/PP Grades
- 4.3 Market Restraints
- 4.3.1 Stricter Single-use-plastic and Carbon-tax Regulations
- 4.3.2 Global Oversupply and Margin Pressure from Mega-crackers
- 4.3.3 Volatility in Naphtha/propane Feedstock Prices
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material Type
- 5.1.1 Polyethylene (PE)
- 5.1.1.1 High-Density PE (HDPE)
- 5.1.1.2 Low-Density PE (LDPE)
- 5.1.1.3 Linear Low-Density PE (LLDPE)
- 5.1.2 Polypropylene (PP)
- 5.1.1 Polyethylene (PE)
- 5.2 By Application
- 5.2.1 Films and Sheets
- 5.2.2 Injection Molding
- 5.2.3 Blow Molding
- 5.2.4 Extrusion Coating
- 5.2.5 Fibers and Raffia
- 5.3 End-user Industry
- 5.3.1 Packaging
- 5.3.2 Automotive and Transportation
- 5.3.3 Electrical and Electronics
- 5.3.4 Building and Construction
- 5.3.5 Other End-user Industries
- 5.4 Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 Borealis GmbH
- 6.4.4 Braskem
- 6.4.5 Chevron Phillips Chemical Company LLC
- 6.4.6 PetroChina Company Limited
- 6.4.7 China Petrochemical Corporation
- 6.4.8 Daelim Co., Ltd.
- 6.4.9 Dow
- 6.4.10 Exxon Mobil Corporation
- 6.4.11 Formosa Plastics Corporation
- 6.4.12 INEOS
- 6.4.13 Japan Polypropylene Corporation
- 6.4.14 LG Chem
- 6.4.15 LyondellBasell Industries Holdings B.V.
- 6.4.16 Mitsubishi Chemical Group Corporation
- 6.4.17 Mitsui Chemicals India Pvt. Ltd.
- 6.4.18 NOVA Chemicals
- 6.4.19 PetroChina Co. Ltd.
- 6.4.20 Reliance Industries Limited
- 6.4.21 SABIC
- 6.4.22 Sasol Ltd.
- 6.4.23 Tosoh Corporation
- 6.4.24 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


