

|
시장보고서
상품코드
2121652
알루미늄 포일 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Aluminum Foil Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
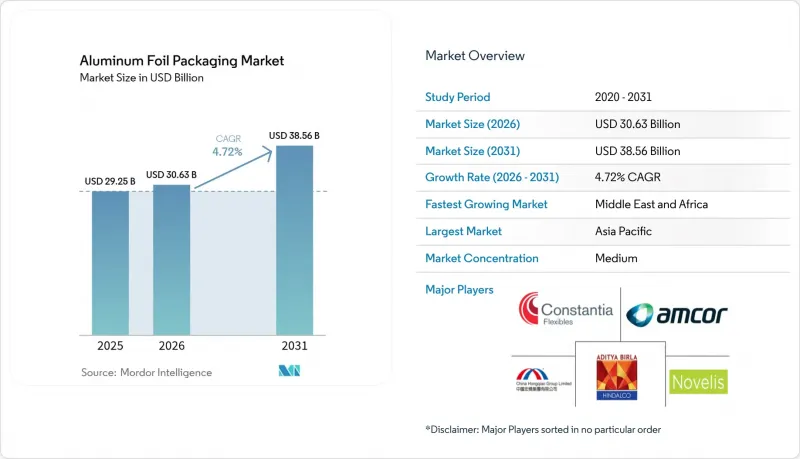
에 따르면 알루미늄 포일 포장 시장 규모는 2026년에 306억 3,000만 달러로 추정되며, 2025년 292억 5,000만 달러에서 확대되어 2031년에는 385억 6,000만 달러에 달할 것으로 예측됩니다.
2026년부터 2031년까지 연평균 성장률(CAGR) 4.72%로 성장할 것으로 전망됩니다.
본 보고서는 유형(압연 포일, 뒷면 합지 포일, 엠보싱·래커 도장 포일 등), 용도(컨버터용 포일, 용기용 포일, 가정용 포일 등), 포장 형태(랩, 파우치·소포장 등), 최종사용자(식품, 음료, 의약품, 화장품·퍼스널케어 등), 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 알루미늄 포일 포장 시장의 동향 및 인사이트
즉석 식품 및 편의 식품에 대한 수요 증가
편의성을 중시하는 라이프스타일로 인해, 가열하여 바로 먹을 수 있는 식사, 구운 과자, 델리 제품의 소비가 증가하고 있습니다. 알루미늄 포일의 열전도성 덕분에 200°C까지 균일하게 재가열이 가능해져, 식품 서비스 트레이, 뚜껑용 필름, 레토르트 파우치에 부가가치를 부여하고 있습니다. 사우디아라비아에서는 포장 식품 소매 매출액이 2028년까지 342억 달러에 달할 것으로 예측되며, 이는 2024년 수준보다 38% 증가한 수치입니다. 판매량 증가는 트레이 및 뚜껑용 알루미늄 포일의 톤수 증가로 직결됩니다. 북미 및 아시아태평양의 주요 가공업체들은 냉장·냉동 식품 제품 라인에 알루미늄 포일 트레이를 채택하고 있으며, 이로 인해 컨버터의 수주 잔고를 안정화시키는 대량 조달 계약이 강화되고 있습니다.
의약품 블리스터 수요 확대
두께 20-25마이크론의 냉간 성형 알루미늄 포일은 타의 추종을 불허하는 방습성 및 산소 차단성을 갖추고 있어, 가혹한 기후 조건에서도 의약품의 효능을 유지합니다. 미국 FDA가 안정성 데이터를 중시함에 따라, 연성이 있고 흠집이 잘 나지 않는 알루미늄 포일 등급이 필요한 더 깊은 심압 블리스터 형태의 채택이 촉진되고 있습니다. 인도 및 인도네시아와 같은 신흥 제네릭 의약품 거점에서는 새로운 블리스터 포장 라인이 가동을 시작하면서, 코팅 및 라미네이트 가공이 완료된 알루미늄 포일 릴의 주문량이 증가하고 있습니다. 이 분야의 프리미엄 가격 책정을 통해 각 컨버터 업체들은 금속 가격 변동 위험을 완화할 수 있게 되었습니다.
대안이 되는 바이오 기반 유연 소재
환경 의식이 높은 소비자를 타겟으로 하는 브랜드들은 종이와 포일을 결합한 하이브리드 소재나 퇴비화 가능한 배리어 필름을 모색하고 있습니다. 스낵이나 과자류는 적당한 산소 차단 성능만으로도 충분하기 때문에 부분적인 대체가 가능합니다. 바이오 필름은 현재로서는 포일의 완벽한 차단 성능에는 미치지 못하지만, 재생 가능성을 강조한 마케팅 메시지를 통해 유럽과 북미에서 시범 도입이 가속화되고 있습니다. 재활용 관련 법규에 따라 세제 혜택이나 표시상의 우대 조치를 통해 재생 가능한 원자재가 보상받게 된다면, 그 위협은 더욱 커질 것입니다.
부문 분석
2025년 매출의 52.05%를 차지한 ‘롤 포일’은 인쇄, 라미네이션, 성형 라인의 원료로서의 역할을 통해 알루미늄 포일 포장 시장의 기반을 이루고 있습니다. 생산 범위는 6마이크론의 가정용 시트부터 200마이크론의 산업용 등급에 이르기까지 다양하며, 공급업체는 최종 용도에 맞춰 두께를 조정할 수 있습니다. 컨버터의 활발한 수요로 인해 중국, 인도, 독일의 제련소는 가동률이 90% 가까이 유지되고 있습니다. ‘배면 코팅 포일’에 기인한 알루미늄 포일 포장 시장 규모는 제약 업계의 냉간 성형 및 고급 커피 캡슐 수요가 라미네이트 설계를 뒷받침함에 따라 연평균 성장률(CAGR) 4.98%로 확대될 것으로 예측됩니다.
엠보싱 가공이나 래커 도장이 적용된 제품은 장식용 과자 포장이나 위조 방지 뚜껑에 사용되며, 틈새 시장에서 가격 프리미엄을 창출하고 있습니다. 2024년 11월 레이놀즈 컨슈머 프로덕츠(Reynolds Consumer Products)가 출시한 홀리데이 디자인 알루미늄 포일 등 시즌 한정 디자인은 표면의 질감과 색상이 진열 시 매력을 얼마나 높이는지를 보여줍니다. 천공 처리된 통기성 알루미늄 포일이나 콘덴서용 알루미늄 포일 등의 ‘기타 유형’은 규모는 작지만 기술적으로 엄격한 요건이 요구되기 때문에 공급업체의 전문화를 촉진하고 있습니다.
컨버터용 포일은 2025년 매출의 41.01%를 차지하며, 알루미늄 포일 포장 시장의 중심적인 위치를 차지하고 있음이 확인되었습니다. 라미네이터 및 인쇄 업체들은 마스터 코일을 파우치, 소형 봉지, 카톤용 롤 스톡으로 변환하여 안정적인 톤수 흐름을 주도하고 있습니다. 무용제 접착제 및 전자빔 경화 기술의 채택 확대에 따라, 처리 능력을 희생하지 않고도 기능성 층의 형성이 개선되고 있습니다. 주로 트레이나 반경질 접시에 사용되는 용기용 포일은 즉석 식품이 신흥 중산층 도시 지역으로 확산됨에 따라 연평균 성장률(CAGR) 5.71%로 성장할 것으로 예측됩니다.
가정용 포일은 여전히 대표적인 상품으로, 레이놀즈 컨슈머 프로덕츠(Reynolds Consumer Products)의 사내 데이터에 따르면 미국 주방의 95%에 상비되어 있습니다. 성숙한 시장에서는 판매량이 정체되어 있지만, 아프리카와 남아시아에서는 가정용 포일 롤의 신규 구매자가 여전히 증가하고 있어 시장이 확대되고 있습니다. 산업용 및 단열용 포일의 수요는 HVAC(냉난방 및 공조) 및 지붕 자재의 반사 차단막을 규정하는 건축 에너지 기준과 밀접한 관련이 있으며, 건설 사이클에서는 틈새 시장이지만 꾸준한 수요원 역할을 하고 있습니다.
지역별 분석
아시아태평양은 2025년 시장 규모의 39.88%를 차지했습니다. 이는 중국의 제련소와 압연 공장을 통합한 클러스터, 그리고 인도의 Hindalco사가 배터리용 포일 생산 라인을 위해 실시한 100억 달러 규모의 생산능력 확장이 주도하고 있습니다. 운임 하락과 보크사이트 광산과의 근접성은 때때로 전력 가격이 급등함에도 불구하고 수출 경쟁력을 강화하고 있습니다. 이 지역의 알루미늄 포일 포장 시장 규모는 가공 식품 수요 확대와 백신 생산의 현지화에 힘입어 한 자릿수 중반대의 성장이 예상됩니다.
북미는 여전히 기술 주도형이며, 첨단 스크랩 선별 공장이 가동되고 있어 사용 후 알루미늄 포일의 회수율은 35%를 초과하고 있습니다. 미국의 소비는 냉장 식품 정기 구독 서비스와 유도 밀봉 용기에 담겨 출하되는 영양 보충제 액상 제품에 의해 견인되고 있습니다. 캐나다의 메이플 제품 부문도 마찬가지로, 운송 중량을 줄이기 위해 유리 용기에서 알루미늄 포일 라미네이트 파우치로 전환하고 있습니다.
유럽은 ‘포장 및 포장 폐기물에 관한 규정’에 따라 가장 엄격한 규제 감독을 받고 있습니다. 재활용 소재의 최소 함유율에 대한 의무적 목표에 따라, 재용해용 깨끗한 알루미늄을 회수하는 연속 열분해 설비 및 라커 제거 설비에 대한 투자가 촉진되고 있습니다. 규정 준수 비용이 중소 가공업체에 부담이 되고 있는 반면, 다국적 기업 그룹은 3개월 동안 500만 개를 회수한 오스트리아의 커피 캡슐 재활용 시범 사업과 같은 폐쇄형 순환 프로그램을 활용하고 있습니다. 연평균 성장률(CAGR) 6.78%로 확대되고 있는 중동 및 아프리카에서는 식품 가공 분야에 대한 외국인 직접 투자(FDI)와 사우디아라비아 및 이집트에서 급성장하고 있는 제약 클러스터가 주도적인 역할을 하고 있습니다. 이 지역에서는 고온 기후 하의 물류에 적합한 고차단성 포장이 요구되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the aluminum foil packaging market size in 2026 is estimated at USD 30.63 billion, growing from 2025 value of USD 29.25 billion with 2031 projections showing USD 38.56 billion, growing at 4.72% CAGR over 2026-2031.
This report is Segmented by Type (Rolled Foil, Backed Foil, Embossed and Lacquered, and More), Application (Converter Foils, Container Foils, Household Foils, and More), Packaging Format (Wraps, Pouches and Sachets, and More), End User (Food, Beverage, Pharmaceutical, Cosmetics and Personal Care, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Aluminum Foil Packaging Market Trends and Insights
Rising Demand for Ready-to-Eat and Convenience Foods
Convenience-oriented lifestyles elevate consumption of heat-and-eat meals, baked goods, and deli products. Aluminum foil's thermal conductivity enables uniform reheating up to 200 °C, adding value for foodservice trays, lidding films, and retort pouches. In Saudi Arabia, packaged food retail sales are projected to reach USD 34.2 billion by 2028, 38% above 2024 levels. Volume upticks translate directly into higher foil tonnage for trays and lidding. Major processors in North America and Asia-Pacific embed foil trays into chilled and frozen meal lines, reinforcing bulk procurement contracts that stabilize converter order books.
Growth in Pharmaceutical Blister Demand
Cold-form aluminum foil of 20-25 microns thickness offers unrivaled moisture and oxygen barriers, preserving drug potency across harsh climates. The U.S. FDA's emphasis on stability data propels the adoption of deeper-draw blister formats that require ductile, scratch-free foil grades. Emerging generics hubs in India and Indonesia commission new blister lines, raising call-off volumes for coated and laminated foil reels. Premium pricing in this segment cushions converters against metal price volatility.
Alternative Bio-Based Flexible Materials
Brands targeting eco-conscious consumers explore paper-foil hybrids and compostable barrier films. In snacks and confectionery, moderate oxygen protection suffices, allowing partial substitution. While bio-films cannot yet equal foil's full barrier profile, marketing narratives around renewability accelerate trials in Europe and North America. The threat intensifies once recycling legislation rewards renewable inputs through tax incentives or labeling advantages.
Other drivers and restraints analyzed in the detailed report include:
- Superior Barrier Properties and Shelf-Life Extension
- Induction Heat-Seal Liners for E-Commerce Liquids
- Raw Aluminum Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rolled Foil captured 52.05% of 2025 revenue, anchoring the aluminum foil packaging market through its role as feedstock for printing, laminating, and forming lines. The output spectrum spans 6-micron household sheets to 200-micron industrial grades, letting suppliers tailor gauge to end-use. Strong converter demand keeps mills in China, India, and Germany running near 90% capacity utilization. The aluminum foil packaging market size attributed to Backed Foil is projected to widen at a 4.98% CAGR as pharmaceutical cold-form and premium coffee capsule demand reward laminate designs.
Embossed and Lacquered variants address decorative confectionery wraps and tamper-evident lidding, generating niche price premiums. Seasonal patterns, such as holiday-pattern foil launched by Reynolds Consumer Products in November 2024, illustrate how surface texture and color enhance shelf appeal. Other Types, including perforated ventilation foils and capacitor foils, remain small but technically stringent, reinforcing supplier specialization.
Converter Foils generated 41.01% of 2025 sales, confirming their place at the center of the aluminum foil packaging market. Laminators and printers transform master coils into rollstock for pouches, sachets, and cartons, driving consistent tonnage flow. Rising adoption of solvent-free adhesives and electron-beam curing elevates functional layering without sacrificing throughput. Container Foils, mainly for trays and semi-rigid dishes, are forecast at a 5.71% CAGR as ready-to-eat meals penetrate emerging middle-income urban zones.
Household Foil remains a legacy staple, held in 95% of U.S. kitchens per Reynolds Consumer Products' internal data. Volume is flat in mature markets but expands in Africa and South Asia, where consumer foil rolls still gain first-time buyers. Industrial and Insulation Foils link demand to building energy codes that specify reflective barriers in HVAC and roofing, a niche yet resilient outlet during construction cycles.
Complete Report Scope:
- By Type
- Rolled Foil
- Backed Foil
- Embossed and Lacquered Foil
- Other Types
- By Application
- Converter Foils
- Container Foils
- Household Foils
- Industrial/Insulation Foils
- By Packaging Format
- Wraps
- Pouches and Sachets
- Blisters and Lids
- Trays and Containers
- Other Packaging Fomrats
- By End User
- Food
- Beverage
- Pharmaceutical
- Cosmetics and Personal Care
- Tobacco
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific contributed 39.88% of the 2025 value, driven by China's integrated smelter-converter clusters and India's USD 10 billion Hindalco capacity expansion aimed at battery foil lines. Lower freight costs and proximity to bauxite mines reinforce export competitiveness despite occasional power-price spikes. The aluminum foil packaging market size attached to the region is set for mid-single-digit growth, underpinned by processed food uptake and vaccine production localization.
North America remains technology-led, hosting advanced scrap-sorting plants that lift post-consumer foil recovery yields above 35%. U.S. consumption benefits from chilled-meal subscriptions and nutraceutical liquids shipped in induction-sealed jars. Canada's maple-products sector likewise shifts from glass to foil laminate pouches to trim freight weights.
Europe faces the tightest regulatory lens under the Packaging and Packaging Waste Regulation. Mandatory minimum recycled content targets spur investments in continuous pyrolysis and de-lacquering units that reclaim clean aluminum for remelt. While compliance costs strain small converters, multinational groups use closed-loop programs such as Austria's coffee-capsule recycling pilot that collected 5 million units in three months. The Middle East and Africa, expanding at 6.78% CAGR, leverages food-processing FDI and burgeoning pharmaceutical clusters in Saudi Arabia and Egypt that require high-barrier packs to suit hot-climate logistics.
- Amcor plc
- Constantia Flexibles Group GmbH
- Novelis Inc.
- Hindalco Industries Limited
- Alcoa Corporation
- Reynolds Consumer Products Inc.
- UACJ Corporation
- Hydro Aluminium AS
- United Company RUSAL Plc
- China Hongqiao Group Limited
- Laminazione Sottile S.p.A.
- Toyo Aluminium K.K.
- Carcano Antonio S.p.A.
- Hulamin Ltd.
- Henan Zhongfu Industrial Co., Ltd.
- Coppice Alupack Ltd.
- Ess Dee Aluminium Ltd.
- Penny Plate LLC
- Eurofoil S.A.
- Alufoil Products Pvt. Ltd.
- Zhangjiagang Goldshine Aluminium Foil Co., Ltd.
- Ningbo Times Aluminium Foil Tech Co., Ltd.
- Haomei Aluminium Co., Ltd.
- RCA Converters
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for ready-to-eat and convenience foods
- 4.2.2 Growth in pharmaceutical blister demand
- 4.2.3 Superior barrier properties and shelf-life extension
- 4.2.4 Induction heat-seal liners for e-commerce liquids
- 4.2.5 EV battery pouch-foil adoption
- 4.2.6 Vertical-farming reflective foil demand
- 4.3 Market Restraints
- 4.3.1 Alternative bio-based flexible materials
- 4.3.2 Raw aluminum price volatility
- 4.3.3 Stricter EU recycling targets on foil scrap
- 4.3.4 ESG risks from energy-intensive smelting
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Rolled Foil
- 5.1.2 Backed Foil
- 5.1.3 Embossed and Lacquered Foil
- 5.1.4 Other Types
- 5.2 By Application
- 5.2.1 Converter Foils
- 5.2.2 Container Foils
- 5.2.3 Household Foils
- 5.2.4 Industrial/Insulation Foils
- 5.3 By Packaging Format
- 5.3.1 Wraps
- 5.3.2 Pouches and Sachets
- 5.3.3 Blisters and Lids
- 5.3.4 Trays and Containers
- 5.3.5 Other Packaging Fomrats
- 5.4 By End User
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceutical
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Tobacco
- 5.4.6 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Constantia Flexibles Group GmbH
- 6.4.3 Novelis Inc.
- 6.4.4 Hindalco Industries Limited
- 6.4.5 Alcoa Corporation
- 6.4.6 Reynolds Consumer Products Inc.
- 6.4.7 UACJ Corporation
- 6.4.8 Hydro Aluminium AS
- 6.4.9 United Company RUSAL Plc
- 6.4.10 China Hongqiao Group Limited
- 6.4.11 Laminazione Sottile S.p.A.
- 6.4.12 Toyo Aluminium K.K.
- 6.4.13 Carcano Antonio S.p.A.
- 6.4.14 Hulamin Ltd.
- 6.4.15 Henan Zhongfu Industrial Co., Ltd.
- 6.4.16 Coppice Alupack Ltd.
- 6.4.17 Ess Dee Aluminium Ltd.
- 6.4.18 Penny Plate LLC
- 6.4.19 Eurofoil S.A.
- 6.4.20 Alufoil Products Pvt. Ltd.
- 6.4.21 Zhangjiagang Goldshine Aluminium Foil Co., Ltd.
- 6.4.22 Ningbo Times Aluminium Foil Tech Co., Ltd.
- 6.4.23 Haomei Aluminium Co., Ltd.
- 6.4.24 RCA Converters
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


